


Brink's trades around US$104.75 after a long stretch of mixed returns, and the question now is whether that price is properly supported by the earnings the business is generating. With fresh news around its expanding services and pending acquisition activity, the issue for investors is how much of that earnings story is already embedded in the share price.
- Over the past 5 years the stock is up 87.8%, which puts a lot of weight on whether current and future profits can back up that kind of long haul performance.
- Recent updates around organic growth in services and expectations for higher profitability suggest the earnings base may support more investment in the business without immediately stressing the balance sheet.
- There is a second opinion on Brink's worth weighing. See what analysts think Brink's's shares could be worth.
The stock's next move may depend on whether Brink's current earnings, judged against a Fair Ratio benchmark, make the recent share price look well supported or stretched.
If you want to stress test this same earnings question beyond Brink's and across a broader opportunity set, scan companies in the 33 high quality undervalued stocks.
Does Brink's Look Undervalued on Earnings?
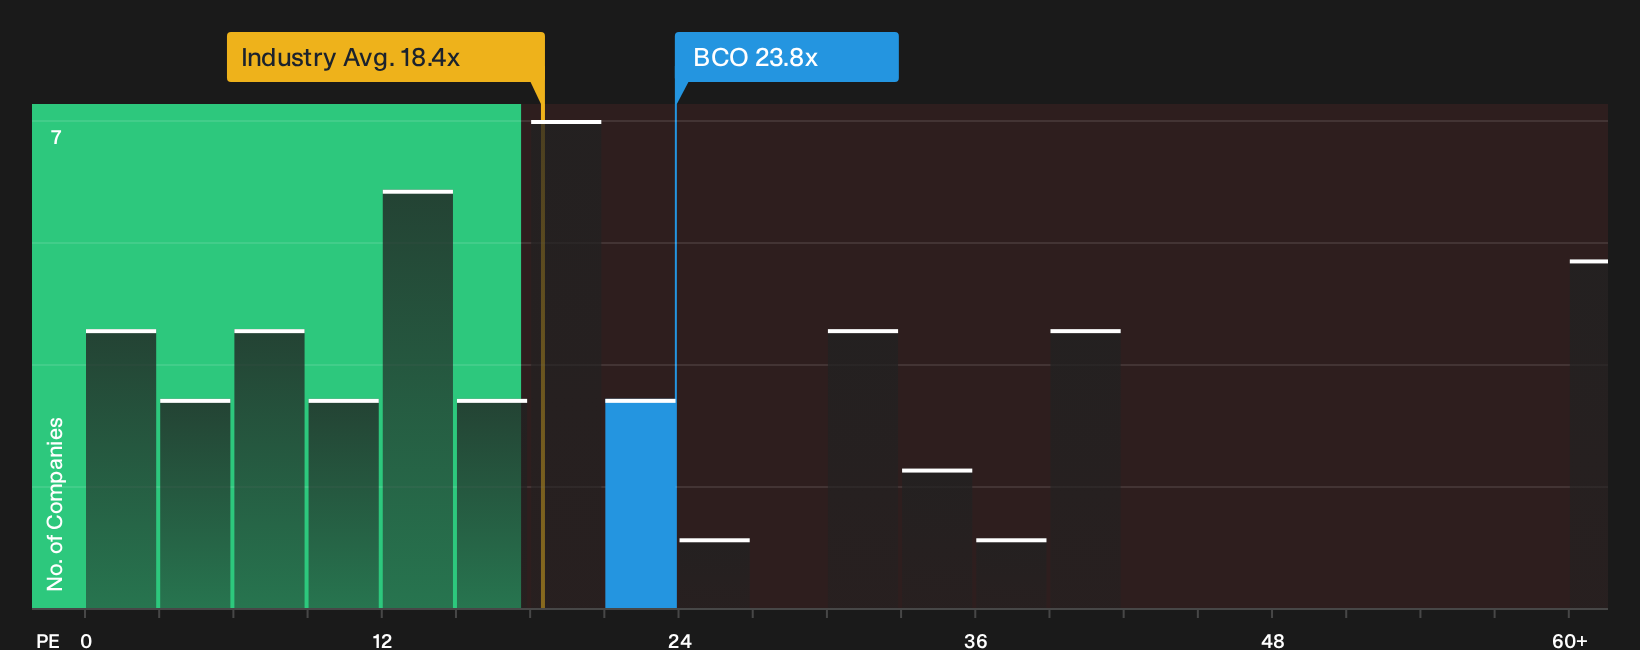
The P/E ratio is a useful measure for Brink's because the business is primarily assessed on the earnings power of its service contracts. Brink's trades on a P/E of about 23.8x, which is almost level with the peer average near 24.1x and higher than the wider Commercial Services sector around 18.4x. Against those broad groups, the stock does not appear especially cheap on headline earnings.
A more tailored yardstick, the Fair Ratio, indicates that Brink's is undervalued on this metric, since the current P/E sits below the level that might be expected once its growth profile, profitability, scale and risk factors are considered together. Because recent Q2 2026 results and the NCR Atleos progress have already highlighted better profit expectations to the market, the gap between the current multiple and that Fair Ratio suggests investors may not be fully reflecting that earnings story in the price. Explore the numbers behind Brink's's P/E valuation.
The Brink's Narrative: What Would Justify Today's Price?
Narratives for Brink's pick up where this valuation puzzle leaves off. They explain what kind of path for growth, margins and earnings would need to occur for the share price to look meaningfully higher or lower from here. Each scenario links its numbers back to a clear view on how Brink's expansion prospects, profitability and risk profile might evolve, giving you something concrete to revisit as fresh information comes through.
One of the top community narratives on Brink's: 28% undervalued
"The current valuation suggests that Brink's share price does not fully reflect the company’s larger post Atleos scale, higher free cash flow generation…"
Discover why this Narrative puts Brink's at 28% undervalued.
For Brink's, the people in charge may matter as much as the numbers
Before deciding how comfortable you feel with Brink's valuation story, it is worth checking who is steering the business, how their incentives are set up, and whether those rewards really line up with your interests. See who runs Brink's and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com