


CareTrust REIT has built a solid long term track record. The real question for anyone looking at the stock today is whether its current price makes sense relative to the earnings that support it. With the share price recently closing at US$36.55, the conversation now shifts from past gains to what that figure implies about the strength and durability of CareTrust REIT's profit stream.
- Over the past 5 years the stock has returned 118.4%. This puts real pressure on investors to judge whether the underlying earnings profile has kept pace with that kind of share price climb.
- The business model relies on rental income from healthcare properties, so rent coverage, lease terms and tenant stability can heavily influence how much of that earnings base ultimately supports shareholders over time.
- There is a second opinion on CareTrust REIT worth weighing. See what analysts think CareTrust REIT's shares could be worth.
The issue now is whether CareTrust REIT's current share price is adequately grounded in the earnings it generates today and what investors expect those profits to look like over time.
If you want to stress test whether CareTrust REIT's earnings based valuation question applies elsewhere, scan a wider field of income focused real estate players through 8 dividend fortresses
Does CareTrust REIT Look Undervalued on Earnings?
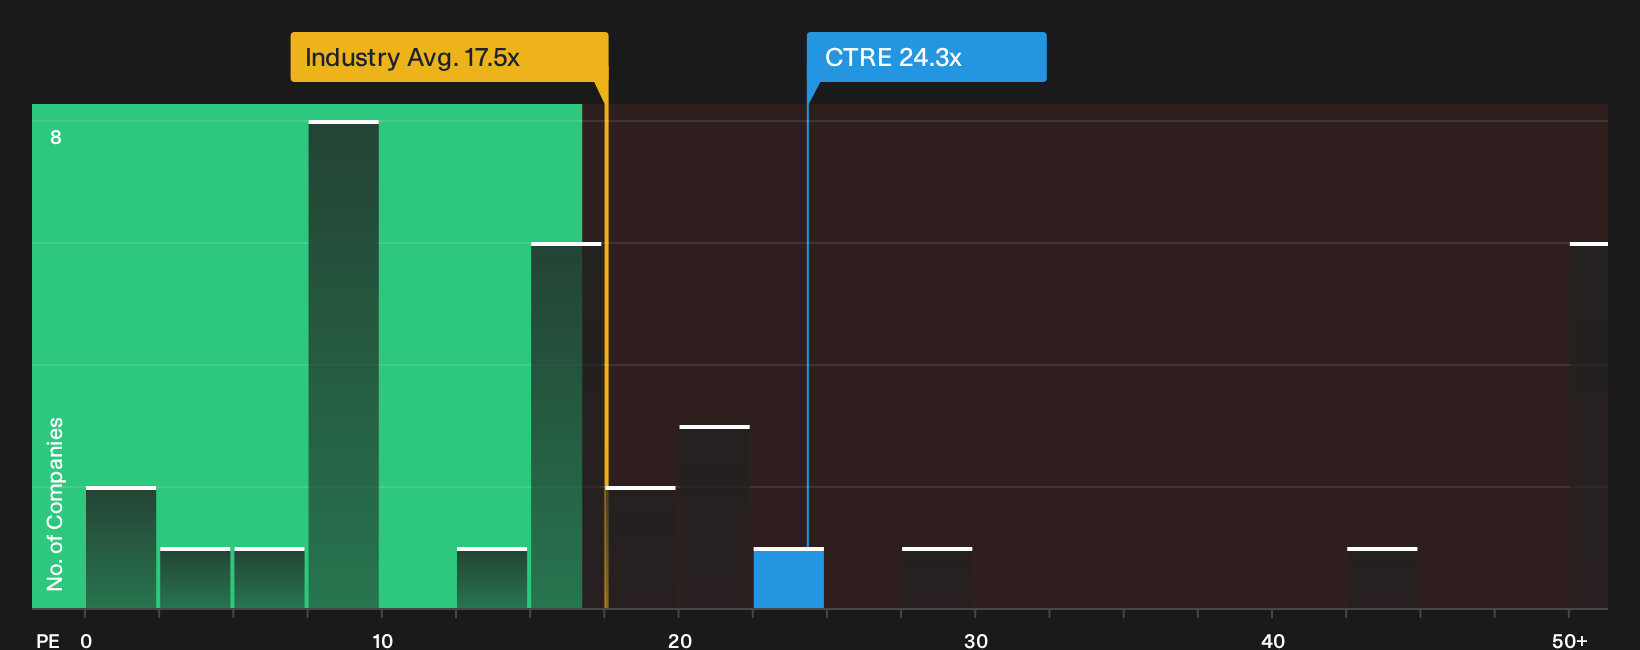
The P/E ratio is usually a useful starting point for a REIT like CareTrust REIT because earnings per share already reflect interest costs and share count. On this yardstick, the stock trades on about 24.3x earnings, which is above the Health Care REITs group on roughly 17.5x but far below the peer set that averages about 61.9x.
A more tailored fair multiple that adjusts for CareTrust REIT's own size, profitability profile and risk points to a higher level than the current 24.3x. That gap suggests the shares trade below what this framework implies, even though the stock already carries a premium to the broader Health Care REITs sector. Explore the numbers behind CareTrust REIT's P/E valuation.
The CareTrust REIT Narrative: What Would Justify Today's Price?
Narratives pick up where that earnings puzzle leaves off for CareTrust REIT by spelling out what kind of future rent growth, margins and earnings pattern would need to play out for the stock to be worth materially more or less than its current share price. They sit on Simply Wall St's Community page so you can see the assumptions behind a single valuation ratio or model figure and then watch how reality lines up with that path over time.
One of the top community narratives on CareTrust REIT: 19% undervalued
"The main thing that has to go right is that CareTrust REIT continues to place capital with high quality operators and sustain current lease coverage..."
Discover why this Narrative puts CareTrust REIT at 19% undervalued.
One more angle on CareTrust REIT that could change how you see it
Valuation only tells you so much about CareTrust REIT without understanding who is steering the portfolio, how they are rewarded, and whether those incentives truly line up with your interests. See who runs CareTrust REIT and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com