


Restar (TSE:3156) has drawn fresh attention after recent share price moves left the stock trading at an implied intrinsic discount of about 43%. This has prompted investors to reassess how the business is currently valued.
For context, Restar’s share price has climbed strongly over the year, with a 90 day share price return of 77.68% and a year to date share price gain of 121.15%. The 1 year total shareholder return of 148.79% points to powerful momentum rather than a short lived spike.
Scan other fast moving opportunities by comparing Restar with a curated set of 13 high quality undervalued stocks that currently trade at implied discounts too.
That kind of surge can either mirror improving fundamentals at Restar or simply reflect a swing in market mood. Which picture does the current valuation actually paint?
Most Popular Narrative: 140% Overvalued
Against the latest close of ¥6,210, the leading narrative on Restar pegs fair value far lower at ¥2,588, so the current market price sits well above that assessment and forces you to ask what is being priced in.
Trend to remain positive. Registering OP growth of 487% YoY, Q1 FY3/27 results were significantly ahead of expectations, with Restar strongly positioned to benefit from AI-driven data center investment demand and rising prices for key products. Taking these factors into account, the company has revised FY guidance and DPS upward. We believe the earnings outlook remains strong, with continued high order visibility, rather than scenarios where demand is driven by a temporary supply shock or customer pre-buying.
See why 1 investors see Restar as 140% overvalued.
Result: Fair Value of ¥2,588 (OVERVALUED)
Still, Restar’s story leans heavily on AI data center spending and M&A execution, so any slowdown in demand or a stalled deal pipeline could unwind this optimism.
Find out about the key risks to this Restar narrative.
Another View On Restar Using DCF
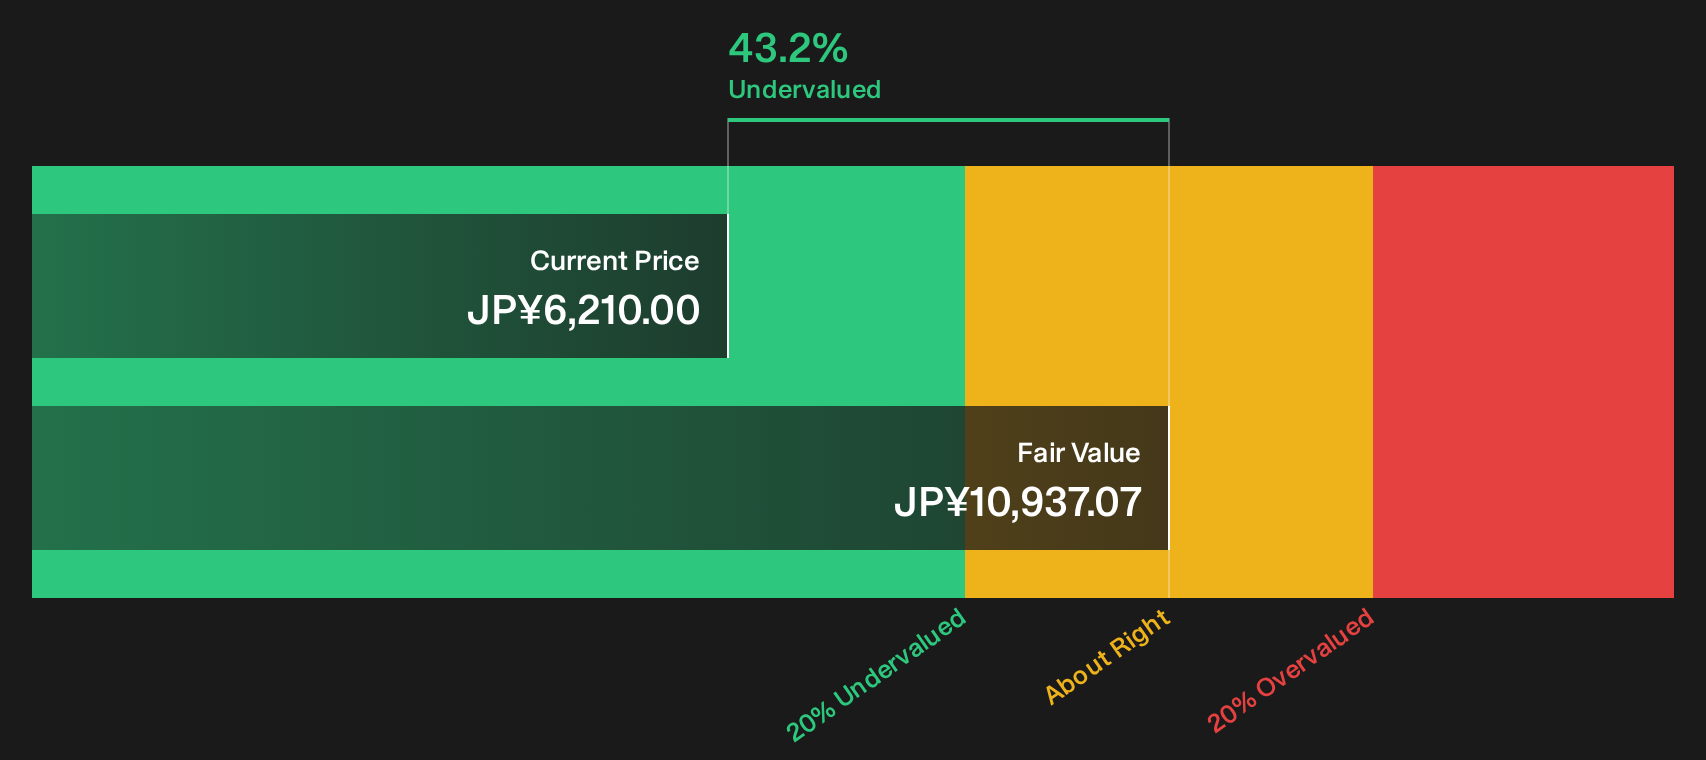
The first narrative pegs Restar as heavily overvalued at ¥6,210 versus a fair value near ¥2,588. Our DCF model points in the opposite direction. On this approach, the shares trade about 43% below an estimated future cash flow value of roughly ¥10,937. Which lens should carry more weight for you?
Before leaning on either signal too heavily, it is worth understanding how sensitive long term cash flow models can be to small shifts in growth or discount rate assumptions. Look into how the SWS DCF model arrives at its fair value.
Next Steps
The mix of bullish and cautious takes around Restar is sharp, so move fast, review the data yourself, and weigh both sides carefully by checking 3 key rewards and 3 important warning signs.
Looking for more Restar sized opportunities?
If you stop with Restar, you risk missing other setups where price, quality, and risk line up in your favor. Cast the net wider and pressure test your next ideas now using the Simply Wall Street Screener.
- Zero in on potential bargains early by scanning a 73 high quality undiscovered gems before they attract wider attention.
- Lock in a focus on resilience by filtering for a list of solid balance sheet and fundamentals (22 results) that can better withstand shocks.
- Dial down portfolio stress and hunt for steadier performers using a 22 resilient stocks with low risk scores tailored to more defensive profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com