


MilDef Group (OM:MILDEF) drew investor focus after publishing preliminary third quarter 2026 guidance, flagging approximately SEK 825 million in sales and organic growth of about 53%, alongside an estimated SEK 920 million delivery backlog for the rest of 2026.
The preliminary guidance arrived during a strong run in MilDef Group’s stock, with a 1-day share price return of 3.39% and a 7-day move of 14.53% contributing to a 90-day gain of 33.83% and a year-to-date share price return of 110.83%. Total shareholder returns over 3 and 5 years have been several times higher, suggesting that investors are reassessing both growth potential and risk around the current SEK253.0 share price.
Scan other high-momentum defence and infrastructure suppliers by reviewing the hand-picked 55 AI infrastructure stocks, which share some of the same demand drivers as MilDef Group.
MilDef Group now looks like a powerful operator in rugged defence IT, yet the share price has sprinted far ahead of the market this year. Is this still a solid business at a fair tag, or has enthusiasm run too hot?
Most Popular Narrative: 4% Overvalued
MilDef Group’s most followed valuation narrative points to a fair value of about SEK243.88, slightly below the recent SEK253.0 close. This positions the stock as modestly expensive rather than extremely stretched.
The surge in order intake (up 116% YoY, with 58% organic growth) and the record SEK 3.2 billion order backlog, underpinned by increased NATO/EU defense budgets and mandates for higher spending, are cited as factors that support expectations for top-line revenue acceleration over the next several years.
Ongoing digitalization initiatives within armed forces, including a pronounced focus on advanced system integration, software, secure networks, and data-driven defense, are described as drivers for more systems contracts and higher-margin service offerings, which some observers expect to gradually uplift EBITDA and net margins.
See why 21 investors see MilDef Group as 4% overvalued.
Result: Fair Value of SEK243.88 (OVERVALUED)
Still, the MilDef Group story can be knocked off course if complex European defence contracts are delayed or if rapid capacity expansion drives cost overruns and squeezes margins.
Find out about the key risks to this MilDef Group narrative.
Another View: MilDef Group Through The Cash Flow Lens
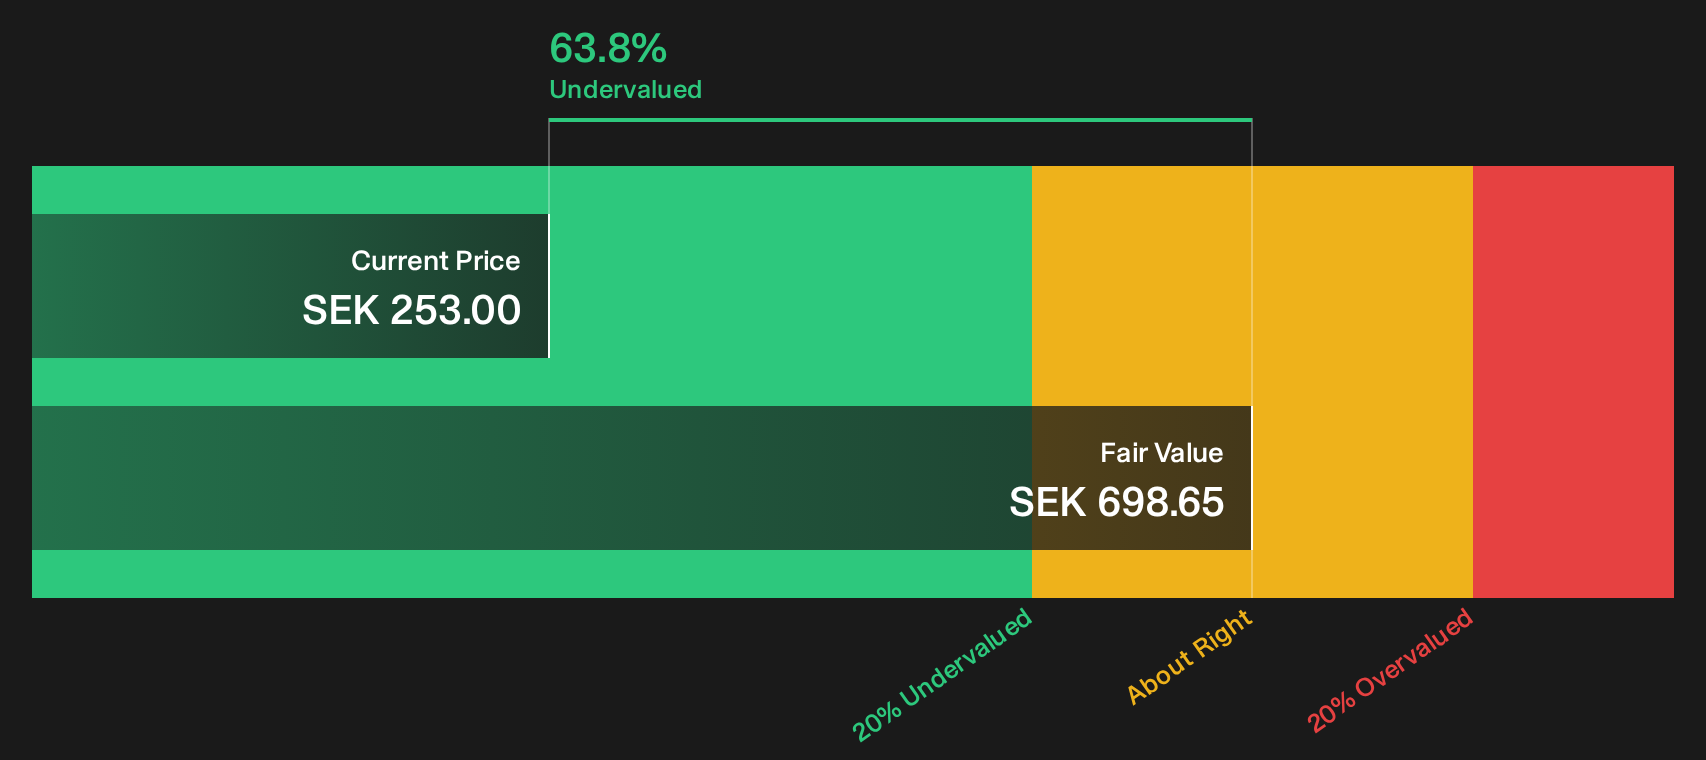
The DCF work tells a very different story. Our DCF model points to a future cash flow value of about SEK698.65 per share, compared with the current SEK253 price, which screens as heavily undervalued if those cash flow assumptions hold up.
That gap only matters if the underlying forecasts make sense for you, so it is worth stress testing the inputs and seeing how sensitive the outcome is to growth and discount rate shifts before leaning on it too heavily. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MilDef Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in MilDef Group’s story. Momentum, backlog and cash flow value estimates all pull in different directions, so check the underlying data now. Weigh both the upside case and the caution flags by reviewing the 3 key rewards and 1 important warning sign.
Looking for more MilDef Group style investment ideas?
If MilDef Group has sharpened your focus, do not stop here. Broaden your watchlist with fresh, data driven ideas that you might regret skipping later.
- Target stronger potential value by reviewing companies that screen as undervalued on quality and fundamentals through the 191 high quality undervalued stocks.
- Prioritise resilience and capital protection by checking the 234 resilient stocks with low risk scores for businesses with more stable risk profiles.
- Hunt for under-the-radar opportunities by scanning the 617 high quality undiscovered gems where solid fundamentals have not yet attracted broad attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com