


Valued at a market capitalization of $145.6 billion, Uber Technologies, Inc. (UBER) is a technology company that operates a global platform for ride-hailing, food and grocery delivery, and freight transportation services. The company connects riders with drivers through Uber, consumers with restaurants and retailers through Uber Eats, and businesses with carriers through its logistics platform. Headquartered in San Francisco, Uber has evolved from a ride-hailing app into a multi-vertical mobility and on-demand services ecosystem operating in dozens of countries.
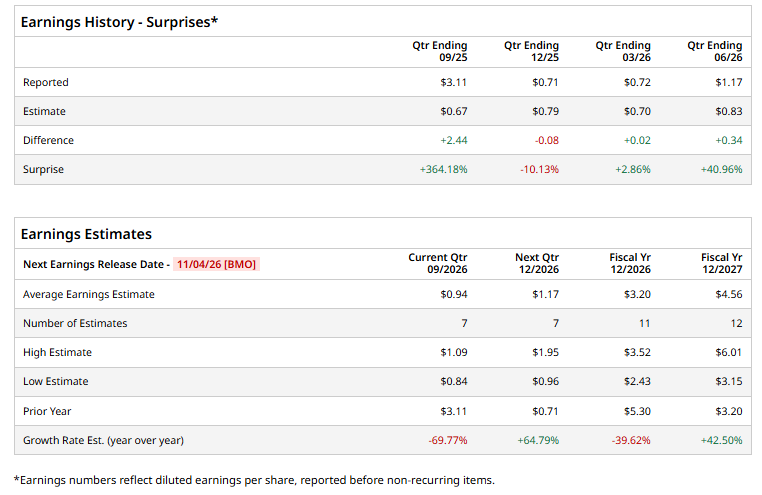
The cab titan is expected to release its Q3 2026 earnings before the market opens on Wednesday, Nov. 4. Ahead of the event, analysts expect the company to post a profit of $0.94 per share on a diluted basis, down 69.8% from $3.11 per share in the year-ago quarter. The company has surpassed Wall Street’s EPS estimates in three of its last four quarters, while missing on another occasion.
For the current year, analysts expect the company to report EPS of $3.20, down 39.6% from $5.30 in fiscal 2025. However, its EPS is expected to rise 42.5% year over year to $4.56 in fiscal 2027.
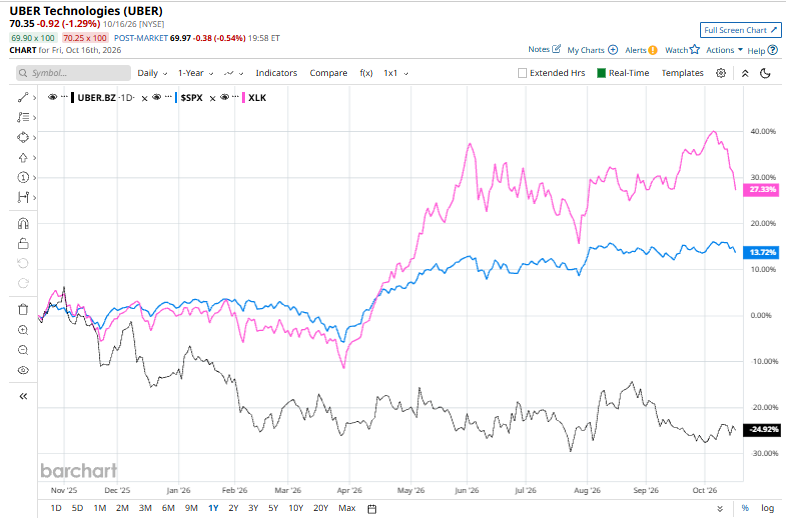
Shares of UBER have declined 24% over the past 52 weeks, underperforming the S&P 500 Index’s ($SPX) 15.5% rise and the State Street Technology Select Sector SPDR ETF’s (XLK) 29% return during the same time frame.
Uber Technologies has faced pressure during the past year as concerns about autonomous-vehicle competition, rising investment requirements, and weaker-than-expected guidance weighed on investor sentiment. The company’s planned spending of more than $10 billion on autonomous-vehicle commercialization has raised concerns about its impact on near-term profitability and free cash flow. Meanwhile, growing competition from robotaxi operators alongside pressure from delivery rivals has increased uncertainty about Uber’s long-term competitive position.
Adding to that, on Sept. 11, Arete Research downgraded Uber Technologies to “Neutral” from its previous rating and lowered its price target to $74, citing limited upside potential.
Analysts’ consensus opinion on the stock is highly bullish, with a “Strong Buy” rating overall. Among the 45 analysts covering the stock, 33 are recommending a “Strong Buy,” four recommend a “Moderate Buy,” seven recommend a “Hold,” and the remaining one analyst suggests a “Strong Sell” for the stock. UBER’s average analyst price target is $102.38, indicating an upside of 45.5% from the current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.