


- ABM Industries announced that it has extended its longstanding relationship with SoFi Stadium and YouTube Theater, continuing to provide engineering and janitorial services across both venues as part of its wider sports and entertainment operations.
- The renewal highlights ABM Industries' deep operational role at SoFi Stadium, where it delivers roughly 84,000 engineering service hours a year and can scale janitorial staffing to more than 250 team members on major event days.
- This development examines how ABM Industries' extended SoFi Stadium partnership relates to the existing investment narrative around contract quality and margins.
Scan how ABM Industries fits into the wider facilities and venue services space by reviewing the hand-picked list of solid balance sheet and fundamentals (25 results) that operate in similarly complex environments.
ABM Industries Investment Narrative Recap
For ABM Industries, the core belief as a shareholder is that contract quality keeps improving. The focus is on complex facilities where the firm can justify higher value engineering work, while still managing lower margin janitorial volumes. The extended SoFi Stadium and YouTube Theater deal fits this pattern but likely does not shift the short term outlook in a material way on its own.
The near term catalyst still sits in how effectively ABM Industries converts its US$1.9b of FY25 bookings and US$1.2b from the first half of FY26 into stable, well priced revenue. The biggest operational risk is slower progress in higher margin semiconductor, microgrid, and data center work, which would limit the mix improvement analysts are currently factoring into their models.
The clearest linked development to this SoFi Stadium renewal is the broader push into higher margin technical infrastructure work in Technical Solutions. Management has already reported nearly US$775 million of year to date FY26 revenue from semiconductor, microgrid, and data center services at a double digit blended operating margin. The stadium deal underscores ABM Industries’ ability to run complex, mission critical sites, which supports that positioning.
This matters for catalysts because investors are watching whether more earnings come from these specialist contracts rather than traditional janitorial only work. If semiconductor revenue, microgrids, and data centers scale as expected, the operational mix may gradually tilt further toward technical services. The SoFi relationship shows the execution muscle, while the infrastructure pipeline holds the bigger margin swing factor.
ABM Industries’ current analyst narrative points to US$10.1b of revenue and US$272.9m of earnings by 2029, based on a 3.3% yearly top line growth assumption and an earnings increase of about US$106.5m from US$166.4m today.
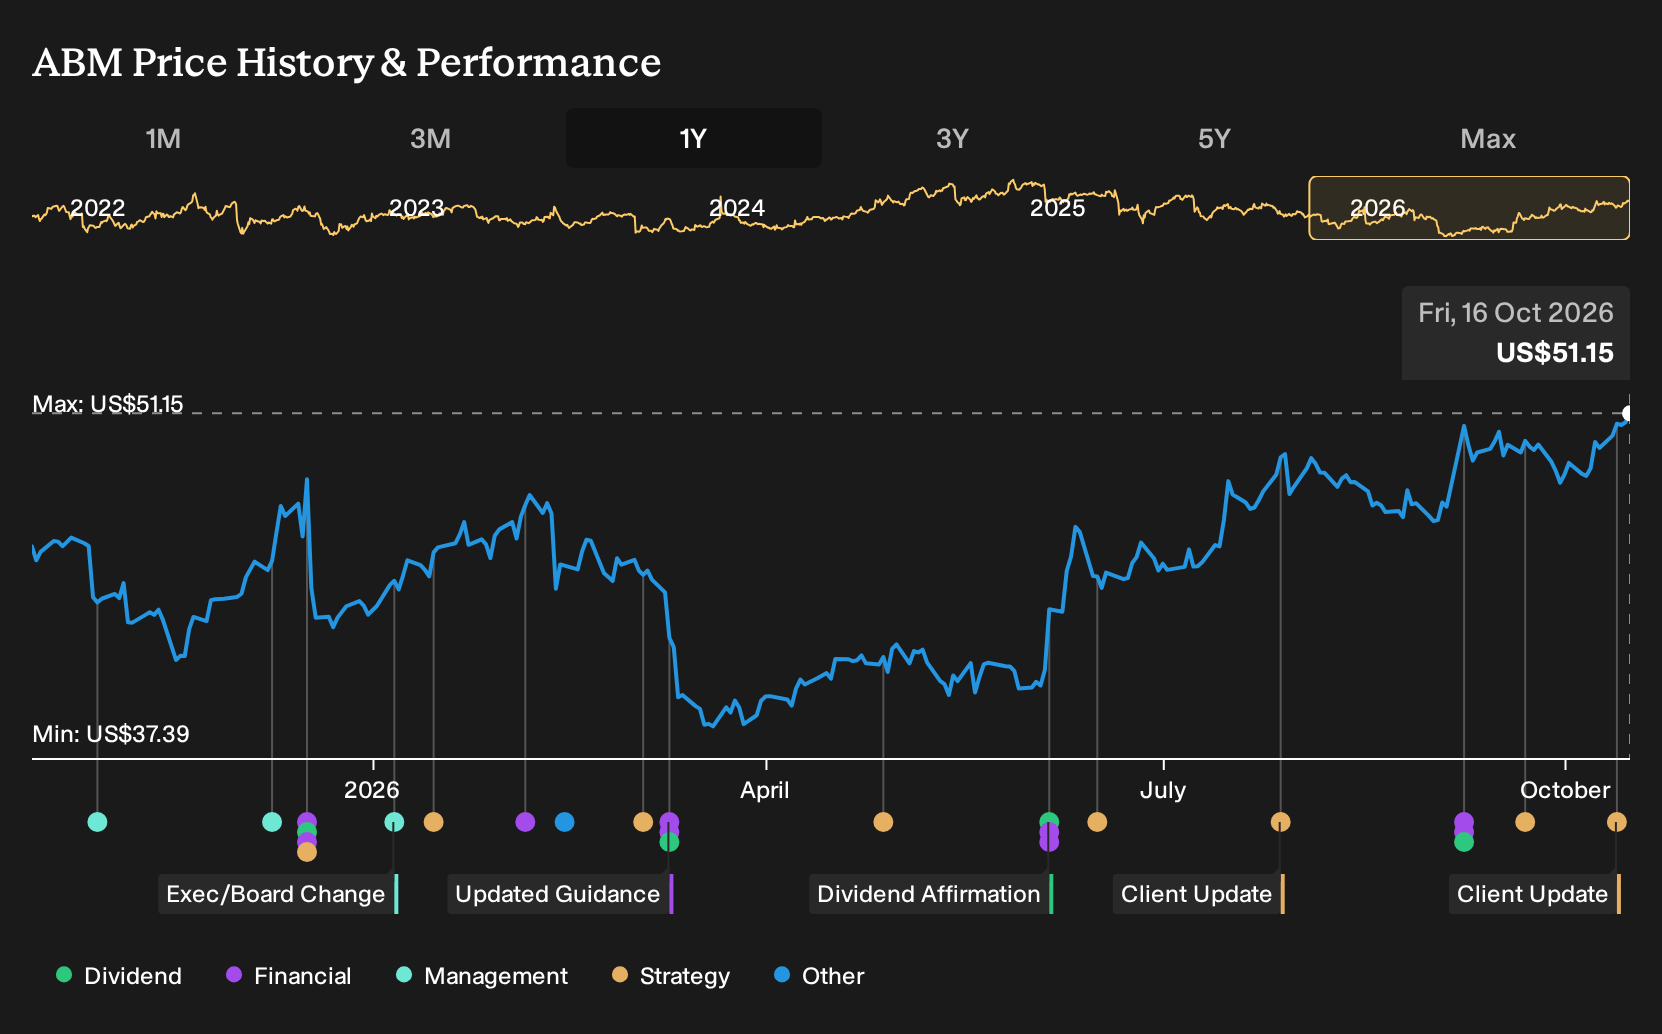
Uncover why ABM Industries' fair value indicates a 9% potential upside to its current price that could close sooner than investors expect.
Exploring Other Perspectives
One alternate view on ABM Industries leans heavily on project risk in Technical Solutions. Those analysts worry that weather disruption and construction delays could matter more than stadium renewals. They were working off slower 2.6% annual revenue growth and about US$9.9b of 2029 sales, which shows how wide opinion can run and why fresh news like SoFi might reshape forecasts.
Explore another ABM Industries fair value estimate, including one that suggests it could be worth just $55.93.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ABM Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ABM Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ABM Industries' overall financial health at a glance.
Looking for more investment ideas beyond ABM Industries?
Once you have a view on ABM Industries, it can help to stress test that thinking against a wider watchlist of potential opportunities using the Simply Wall St Screener.
- If you want potential value combined with quality, scan a curated set of 33 high quality undervalued stocks that pair stronger balance sheets with more conservative pricing.
- For readers focused on income, filter for higher yielding businesses through a targeted set of 8 dividend fortresses that prioritise both payout and balance sheet support.
- When capital protection sits higher on your list, start with a 32 resilient stocks with low risk scores that concentrates on companies with more resilient financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com