


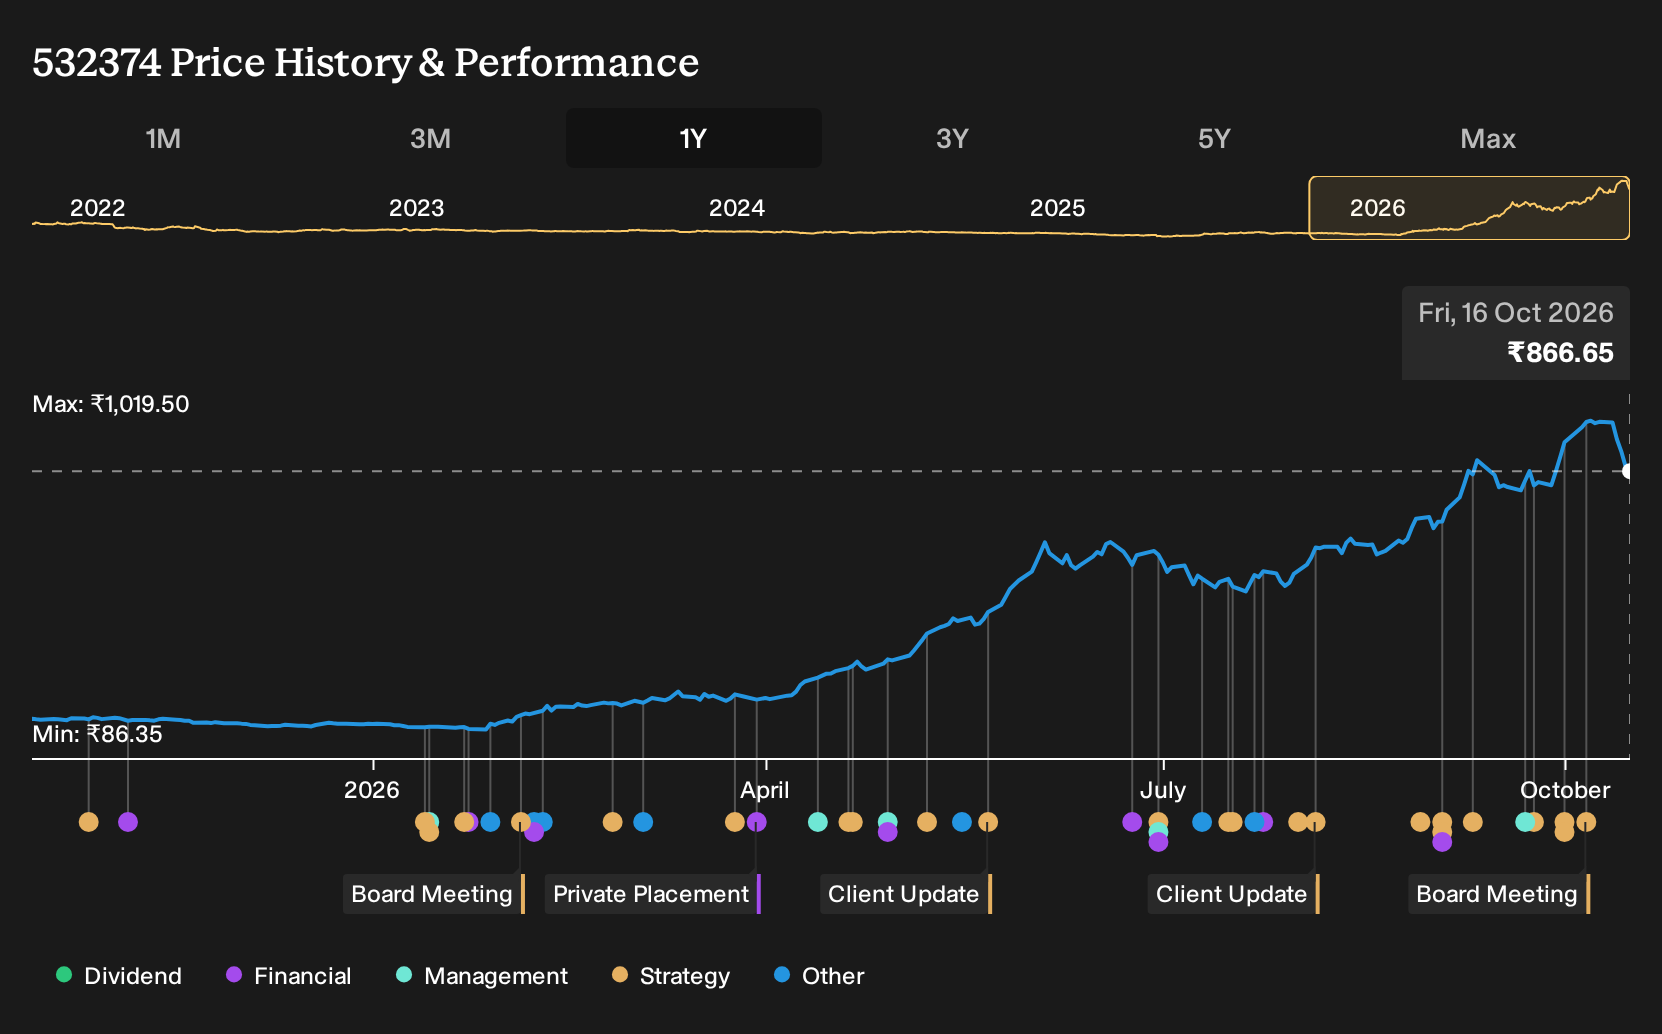
Sterlite Technologies did not need a headline grabbing acquisition to move the story forward. A single quarter told plenty. Management reported Q1 2027 revenue of ₹19,100 million and net income of ₹1,970 million, with net margin at 10.3%, compared with ₹10,190 million and ₹100 million a year earlier. For Sterlite Technologies shareholders, the return over the past year was 648.1%, including dividends. If you were buying on 16 October 2025, what had to feel believable before any of that was on the table?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Sterlite Technologies. Zero in on 191 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Choose Between On Sterlite Technologies
The shares cost ₹117 at the start of the period, which meant any case on Sterlite Technologies had to feel grounded in what the fibre business might reasonably achieve.
The bullish Narrative put Fair Value at ₹128 and leaned on surging FTTx, data center and 5G infrastructure demand. Supporters focused on global manufacturing expansion and large long term contracts as the engine for more resilient revenue and better margins.
The bearish side anchored on Fair Value of ₹106 and worried about wireless and satellite alternatives capping fibre demand. That view stressed high debt from past capacity expansion as a key financial risk if cash flows tightened.
What The Results Changed For The Sterlite Technologies Story
The clearest development was Sterlite Technologies reporting Q1 2027 revenue of ₹19,100 million and net income of ₹1,970 million, with net margin at 10.3%, compared with ₹10,190 million and ₹100 million a year earlier. That margin step up gave more weight to the bullish narrative that expected better profitability, although high debt concerns from the cautious side remained untested in this set of results.
The main lesson is simple. When a thesis hinges on margin improvement, treat net margin as the key scoreboard and track whether each new result actually moves that figure toward the story investors believed.
What Sterlite Technologies' Price Now Asks You To Believe
Sterlite Technologies now trades at ₹867. The selected Narrative places its Fair Value above that figure and ties the gap to how far investors think long term connectivity demand and product mix can support margins and earnings stability.
On this view, a buyer today is effectively judging whether current pricing fully reflects the earnings resilience the Narrative links to higher margin connectivity solutions and broader market exposure.
"Strategic expansion into advanced connectivity and diversified markets is boosting margins, operational efficiency, and earnings stability while reducing risk and strengthening the balance sheet. Geographic and segment diversification, through increased exposure to enterprise, digital, and export markets, dilutes concentration risk and reduces sensitivity to regional demand cycles, thereby enhancing the stability and resilience of both revenue and earnings over the long term."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 18% below our estimate - target AI server and data center test equipment demand growth.
- Company 2 - 33% below our estimate - win bundled subsea projects combining equipment sales with extended service contracts.
- Company 3 - 37% below our estimate - scale AI driven hiring and local services matching while expanding monetization options.
That is three of the list. See all 205 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com