


Mazda Motor (TSE:7261) is teaming up with auto parts supplier Yazaki to use robots in wire harness assembly, shifting part of this labour intensive production back to Japan.
For investors watching the tape, Mazda Motor’s 2.56% 1 day share price return and 3.23% 7 day gain suggest short term momentum is improving. This is occurring even though the 30 day share price return is down 4.40% and the year to date share price return has fallen 10.08%.
Scan other auto and robotics plays responding to supply chain pressures with our curated list of 92 robotics and automation stocks to see how peers are retooling their manufacturing footprints.
Mazda Motor trades at a clear discount to both analyst targets and estimated fair value, even after the recent pop on the Yazaki robotics news. Is the cautious pricing still warranted, or has sentiment lagged reality?
Price-to-Earnings of 6.6x: Is it justified for Mazda Motor?
Mazda Motor changes hands at a P/E of 6.6x while Simply Wall St estimates a fair P/E closer to 13.1x, which points to the market assigning a relatively low earnings multiple to the ¥1,120 last close.
The P/E ratio compares the share price to earnings per share and, for an automaker, it gives a quick read on how investors are weighing profit power against sector peers. A lower P/E often means investors are cautious on how durable current earnings are or how much growth they expect from the business.
Here, the headline numbers and the multiple tell a different story. Earnings over the past year grew very strongly and exceeded both the Auto industry and Mazda Motor's own 5 year average. Yet the shares trade on a P/E that is materially below the estimated fair P/E of 13.1x. The gap between the current 6.6x and that fair ratio is wide, which is a level the P/E could reasonably move toward if sentiment and fundamentals stay aligned.
Relative to the Asian Auto industry average P/E of 13.4x and a peer average of 21.1x, Mazda Motor trades on a much lower earnings multiple. This strongly suggests the market is pricing its profits more conservatively than both the sector and direct comparables.
Explore the SWS fair ratio for Mazda Motor.
Result: Price-to-Earnings of 6.6x (UNDERVALUED)
Still, Mazda Motor faces real pressure if auto demand softens or if robotics investments and supply chain shifts weigh on costs more than expected.
Find out about the key risks to this Mazda Motor narrative.
Another View: Mazda Motor Through A Cash Flow Lens
The low 6.6x P/E paints Mazda Motor as cheaply priced, yet our DCF model suggests something even starker. At ¥1,120 the shares trade 36.7% below an estimated future cash flow value of ¥1,769.9, which also implies the stock is undervalued. If both earnings and cash flow point in the same direction, what is the market still worried about?
Look into how the SWS DCF model arrives at its fair value.
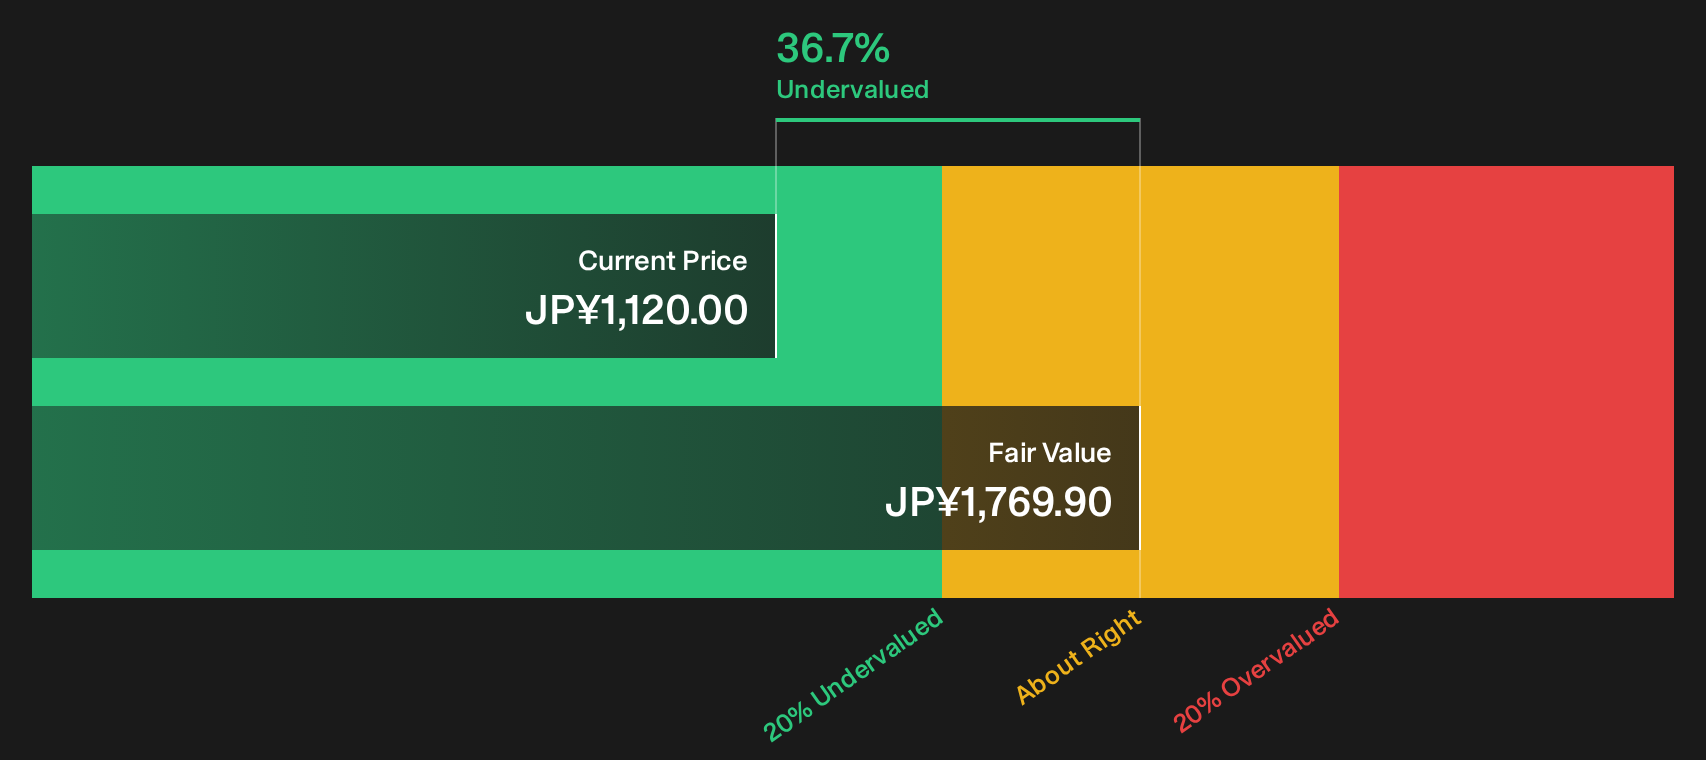
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mazda Motor for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Mazda Motor's valuation and robotics push make this a moment to check the numbers yourself and decide what really matters most. To weigh both the caution and optimism already in the data, start with the 4 key rewards and 2 important warning signs
Want more ideas beyond Mazda Motor?
If Mazda Motor has you rethinking what value looks like, now is the time to widen the lens and line up your next set of candidates.
- Target resilient balance sheets first and use the list of solid balance sheet and fundamentals (22 results) to filter for businesses with financial foundations that can better handle shocks.
- Hunt for mispriced quality by scanning the 13 high quality undervalued stocks and see which companies the numbers suggest may not match their current tags.
- Stack potential income streams by reviewing the 29 dividend fortresses and spot payouts that could complement a more growth focused portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com