


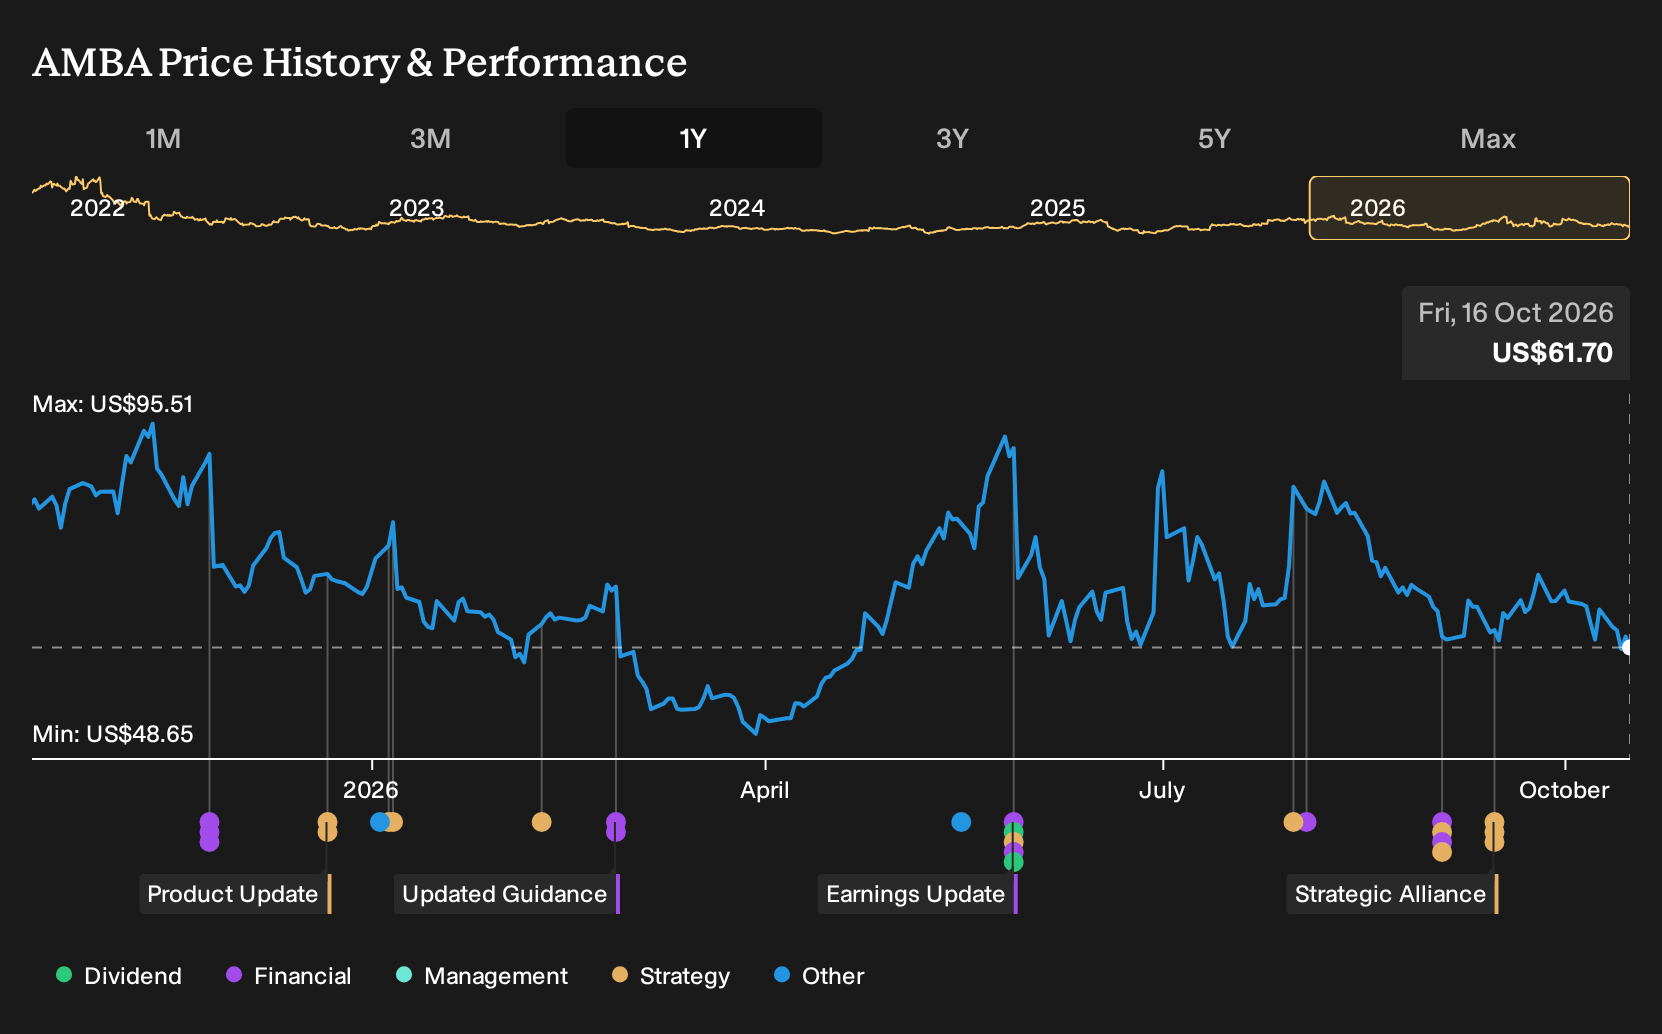
If you bought Ambarella for its edge AI story and sat tight through a year of headlines, the payoff looked very different on your statement. Holding Ambarella over the past year would have meant a 25.4% loss, including dividends. If that decision felt grounded in forecasts of mid‑teens revenue growth, a rapid swing from deep losses toward a 14.1% margin, and a rich 2028 P/E, what exactly did that original case overlook about execution, customer concentration, and IoT reliance?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Ambarella is not the only name tied to this theme. Zero in on 38 AI small caps and compare how each one is priced.
The Two Ambarella Stories Investors Had To Weigh
The shares cost US$84.09 at the start of the period, so any case for Ambarella needed to justify paying that price against uncertain edge AI outcomes.
The bullish narrative pointed to a fair value of US$90.05, based on an assumption of 14.8% annual revenue growth and a future P/E of 74.3x tied to a profit margin reaching 14.1% by about 2028.
The bearish narrative argued for a fair value of US$57.94, built around 12.1% assumed annual revenue growth and concern that Ambarella’s heavy IoT and Asia exposure could magnify cyclicality and customer concentration risk.
What The Ambarella Results Put To The Test
The Hanwha deal, framed at over US$800m across more than 10 years plus Q2 2027 revenue of US$108.1m, supported the bullish Ambarella story around design wins and broader edge AI demand. At the same time, the firm still reported a loss of US$6.7m and a net margin of -6.2%, so the profitability leg of the optimistic case remained unproven. Overall, the evidence cut both ways.
The episode hinged on one assumption you can reuse elsewhere. Strong contract headlines and revenue growth need to be checked against whether losses are shrinking and margins are moving clearly toward the target, not just whether analysts talk about future opportunity.
What Ambarella’s Drop Asks You To Believe Today
Ambarella trades at US$61.7 after falling 25.4% over the past year. The selected Narrative’s Fair Value sits above the current price, based on the idea that contracted edge AI demand and defined serviceable markets eventually matter more than recent share performance.
The distinct question now is whether long dated contracts, semi custom projects and new channel partners really turn Ambarella’s expanded edge AI footprint into durable design wins and earnings. A buyer today would need to believe those programs scale enough to make the price drop an opening rather than a warning.
"The main thing that has to go right is that Ambarella converts its new edge infrastructure products, semi custom programs, and indirect channel agreements into sustained design wins that offset supply chain and customer concentration risks."
One Narrative disagrees with today's price. → See where this Narrative says Ambarella should trade
How Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 24% below our estimate - sells high density liquid cooling and power systems for large AI racks.
- Company 2 - 33% below our estimate - turns AI infrastructure backlog and multicloud database demand into subscription cloud revenue streams.
- Company 3 - 46% below our estimate - integrates an acquired bank while using high retention bankers to expand core relationships.
Those are three of them. See all 33 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com