


Fresh analyst coverage has pushed Nicolet Bankshares (NIC) into the spotlight, highlighting net interest income and profitability metrics that set the regional lender apart from peers and sharpen investor focus on the stock.
Recent trading has been choppy rather than one way, with a 7 day share price return of 0.62% and a 30 day performance that is down 2.51%. However, Nicolet Bankshares still carries strong momentum with a year to date share price gain of 35.94% and a 3 year total shareholder return of 147.76%, suggesting investors have been steadily reassessing its prospects over time.
Compare Nicolet Bankshares with a curated list of solid balance sheet and fundamentals (25 results) to see how other banks with resilient financial footing are trading right now.
The rally in Nicolet Bankshares has already rewarded long term holders, while near term trading has cooled. Does the current valuation still leave enough upside to justify fresh risk for new buyers?
Price-to-Earnings of 22.3x: Is it justified?
Nicolet Bankshares now trades on a P/E of 22.3x, which is high relative to many US banks and suggests investors are already paying up for its earnings profile at the current $163.80 share price.
The P/E ratio compares what the market pays for each dollar of profit. For a lender like Nicolet Bankshares, it gives a quick read on how much investors are willing to value its net income against other financial institutions that operate in a similar regulatory and interest rate backdrop.
Here the P/E of 22.3x is materially richer than the US Banks industry average of 11.5x and above the estimated fair P/E of 16.7x. That gap indicates the market is pricing in stronger profitability and growth than a typical bank, and well ahead of what the fair ratio suggests the valuation could gravitate toward if sentiment changes.
Explore the SWS fair ratio for Nicolet Bankshares.
Result: Price-to-Earnings of 22.3x (OVERVALUED)
Still, patience gets tested if loan demand softens in Nicolet Bankshares communities or credit quality weakens; either could quickly challenge a premium P/E story.
Find out about the key risks to this Nicolet Bankshares narrative.
Another View: SWS DCF Says Undervalued
The P/E ratio presents Nicolet Bankshares as expensive, yet the SWS DCF model tells a different story. On that measure, the shares at $163.80 are assessed as trading below an estimated future cash flow value of $264.62, which places the current premium multiple in a very different context. Which lens do you consider more important for a long term position?
Look into how the SWS DCF model arrives at its fair value.
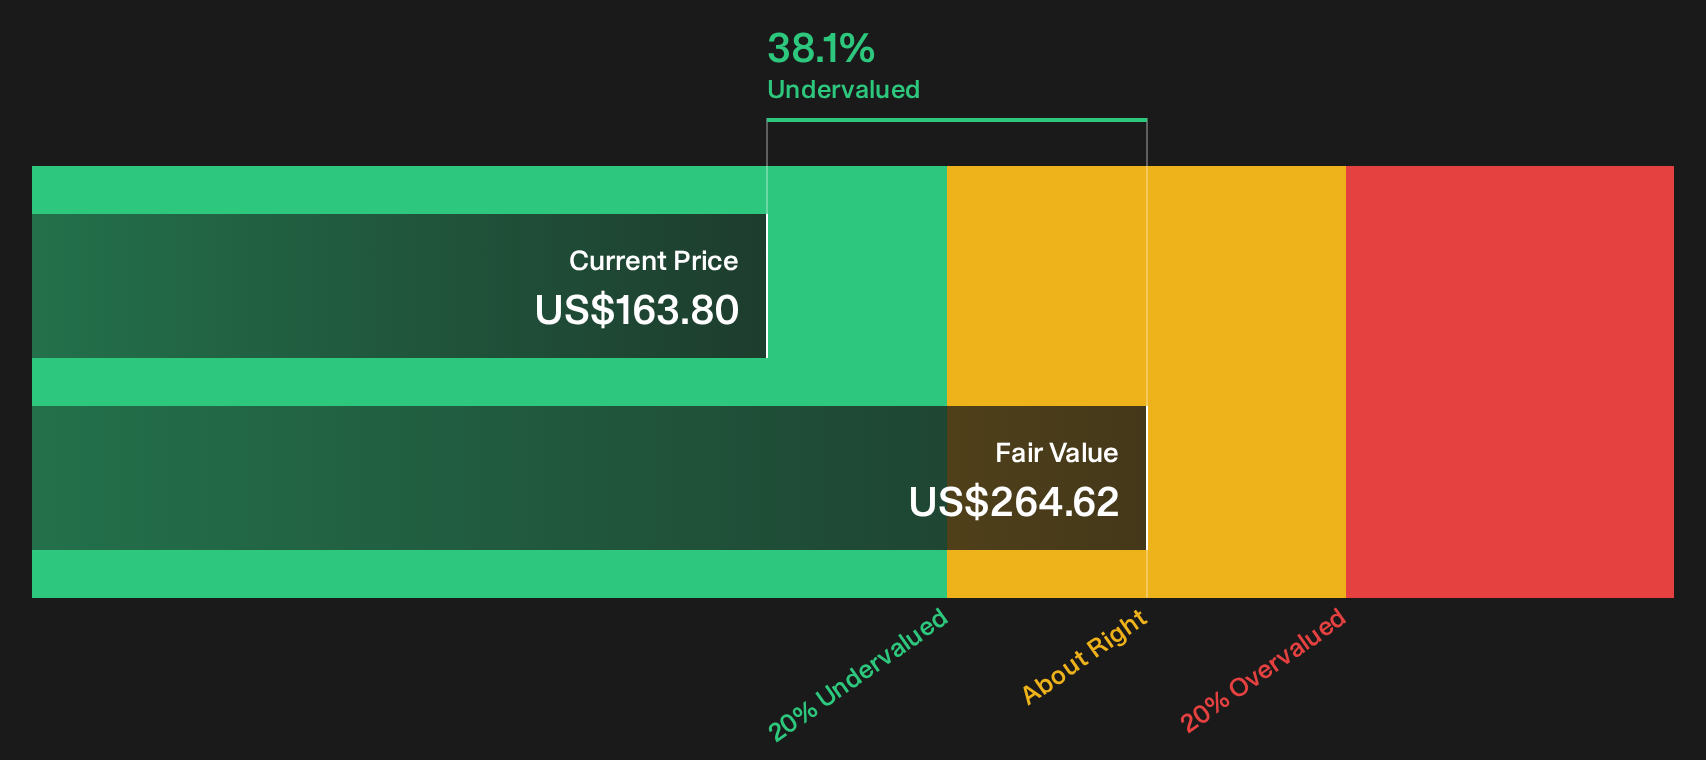
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nicolet Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages can feel confusing, especially when Nicolet Bankshares screens as both expensive on earnings and attractive on cash flow, so dig into the underlying figures yourself and move fast enough that the market is not making the decision for you. To weigh both sides of the story in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more Nicolet Bankshares sized opportunities?
If Nicolet Bankshares has your attention, do not stop here. Broaden your watchlist with fresh ideas that match different risk and income preferences.
- Target resilient balance sheets and steadier profiles by scanning a 32 resilient stocks with low risk scores that filters for companies with lower overall risk characteristics.
- Hunt for mispriced quality by using a 20 high quality undiscovered gems that focuses on fundamentally strong businesses that are not widely followed yet.
- Build a stream of potential income ideas by reviewing a 8 dividend fortresses that highlights companies offering higher dividend yields with robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com