


Ensign Group (ENSG) is back in focus after a securities class action lawsuit accused the healthcare operator of systematically neglecting elderly residents, falsifying care records, and mishandling Medicaid and Medicare billing.
At a share price of US$176.63, Ensign Group has seen short-term pressure linked to the class action headlines, with a 1-day share price return that declined 0.83%. However, the 3-year total shareholder return of 84.72% and 5-year total shareholder return of 147.34% point to a long-running momentum story that some investors may now see as fading, with recent legal risk bringing that narrative back into question.
Spot opportunities beyond Ensign Group by sizing up healthcare operators and adjacent players with stronger financial profiles using our hand-picked list of solid balance sheet and fundamentals (25 results).Ensign Group now trades below both analyst targets and one intrinsic value estimate after legal headlines knocked confidence. Where does a fair appraisal land between those valuation anchors and the current quote?
Most Popular Narrative: 20% Undervalued
Ensign Group's most followed narrative points to a fair value of $220 per share, above the recent close at $176.63. This puts the current lawsuit headlines in tension with a longer term earnings story built around operations and reimbursement dynamics.
A sizeable pipeline of low occupancy, clinically challenged acquisitions, particularly in Texas, creates room for operational turnaround using the existing cluster and ONE CLINICAL model. This can affect occupancy driven revenue and EBIT over multi year periods.
Expansion of Standard Bearer’s owned real estate base and third party tenant relationships is broadening rental income sources beyond Ensign affiliates. This can support a growing, recurring earnings stream and add flexibility to the balance sheet.
See why 1 investors see Ensign Group as 20% undervalued.
Result: Fair Value of $220 (UNDERVALUED)
Still, the Ensign Group story depends heavily on stable Medicare and Medicaid funding, as well as on turning around recently acquired, low occupancy facilities without unexpected cost strain.
Find out about the key risks to this Ensign Group narrative.
Another View On Ensign Group's Valuation
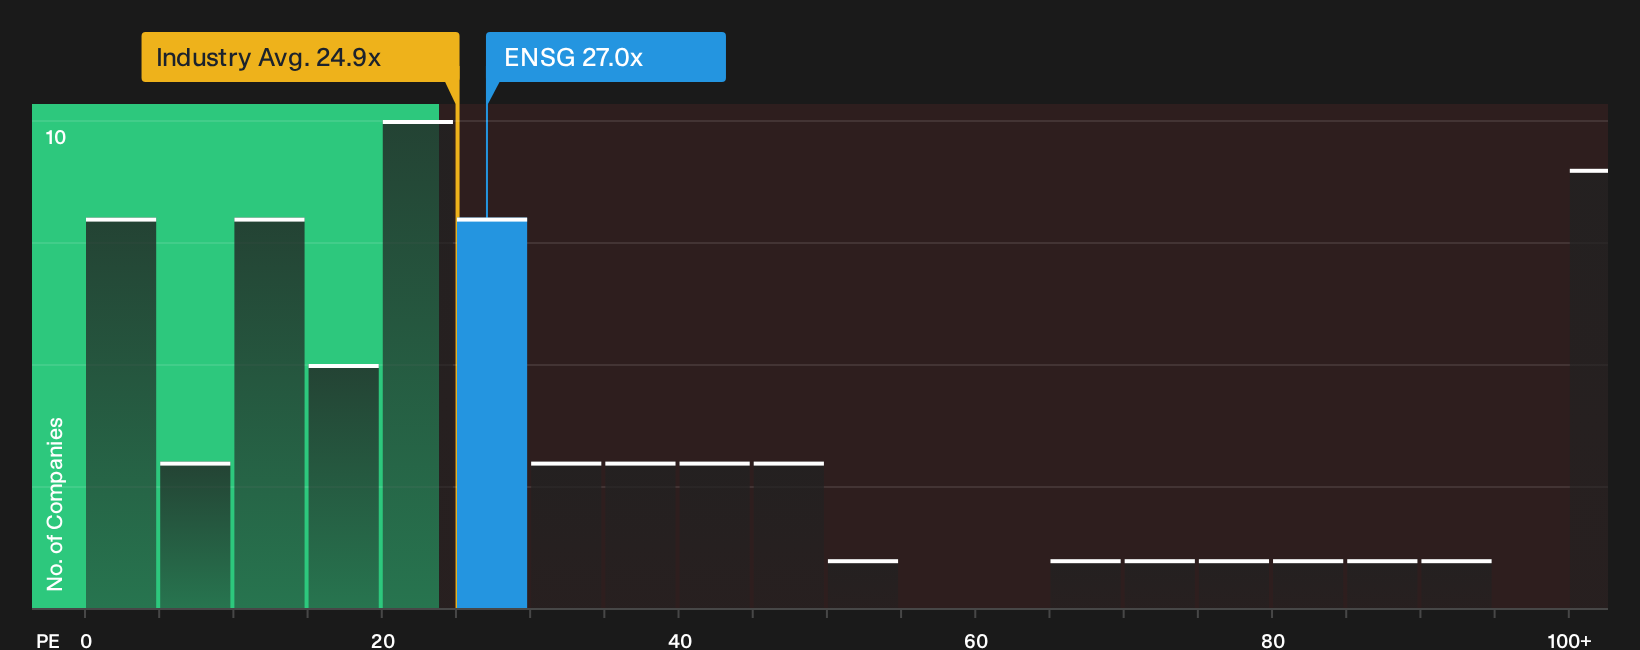
The earlier narrative leans on future earnings to argue Ensign Group is undervalued at $176.63. A simple P/E cross check tells a cooler story. The stock trades at 27x earnings while the US Healthcare sector is at 24.9x and peers average 20.7x.
Our fair ratio estimate sits at 25.7x. This suggests the current multiple is already above a level the market could drift toward over time. If sentiment on growth, legal risk or funding softens, that higher starting point may leave less room for error than the DCF style upside suggests.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Worried the mixed signals around Ensign Group are pulling you in two directions? Act while the details are fresh and pressure test the upside story for yourself by starting with the 4 key rewards.
Looking for more Ensign Group sized ideas?
If Ensign Group has you rethinking risk and reward, this is the moment to widen your field of vision and pressure test fresh opportunities.
Use the Simply Wall Street Screener to quickly surface focused shortlists that match the type of portfolio you want to build next.
- Target resilient compounding by scanning a 32 resilient stocks with low risk scores that filters for businesses with steadier profiles and fewer potential shocks to your returns.
- Hunt for quality at a discount by reviewing a curated 20 high quality undiscovered gems before other investors start paying closer attention.
- Build staying power into your holdings by checking a 8 dividend fortresses that screens for higher yielding payouts backed by solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com