


- AddLife has attracted interest as analysts point to recurring demand for its lab and medical technology offerings, along with a Discounted Cash Flow model that suggests the stock's intrinsic value sits above the current market valuation.
- The emphasis on stable, expanding free cash flow points investors toward AddLife's underlying cash generation as a key driver of the investment debate, rather than short term sentiment.
- We will now look at how AddLife's investment narrative could be influenced by the focus on stable and expanding free cash flow.
Scan 189 high quality undervalued stocks that, like AddLife, pair resilient cash generation with prices that the market may not fully reflect yet.
AddLife Investment Narrative Recap
To be comfortable holding AddLife, you need to believe its mix of lab and medical technology can keep attracting steady demand across healthcare and research customers, while its free cash flow remains resilient enough to fund portfolio tweaks and acquisitions. The recent focus on discounted cash flow and intrinsic value does not change the near term story that operational execution is the main driver.
Right now, the key short term swing factor is how efficiently AddLife can balance organic growth, product rationalisation and acquisition integration without putting strain on working capital or margins. The biggest risk is that high debt, supply chain friction or weak academic funding turns expected free cash flow stability into more volatile cash generation.
There have been no fresh company announcements tied directly to this latest intrinsic value discussion. The most relevant reference point is still management's stated focus on organic growth, portfolio optimisation and bolt on deals in areas like orthopedic surgery. Those priorities sit in the background of any free cash flow focused valuation debate.
For you as a shareholder, the real test is whether AddLife can keep integrating past acquisitions such as BonsaiLab and Edge Medical while maintaining tender wins in Labtech and supporting advanced offerings like robotic surgery and gene sequencing. Execution against those goals will likely matter more to future cash generation, and therefore to any discounted cash flow model, than short term market sentiment around the stock.
AddLife's current analyst narrative points to SEK 12.2b in revenue and SEK 710.9m in earnings by 2029. This is built on an assumed 5.4% yearly revenue growth rate and a move from SEK 560.0m in earnings today to that SEK 710.9m figure, which is an earnings increase of about SEK 150m.
Uncover why AddLife's fair value indicates a 5% potential upside to its current price that could close sooner than you expect.
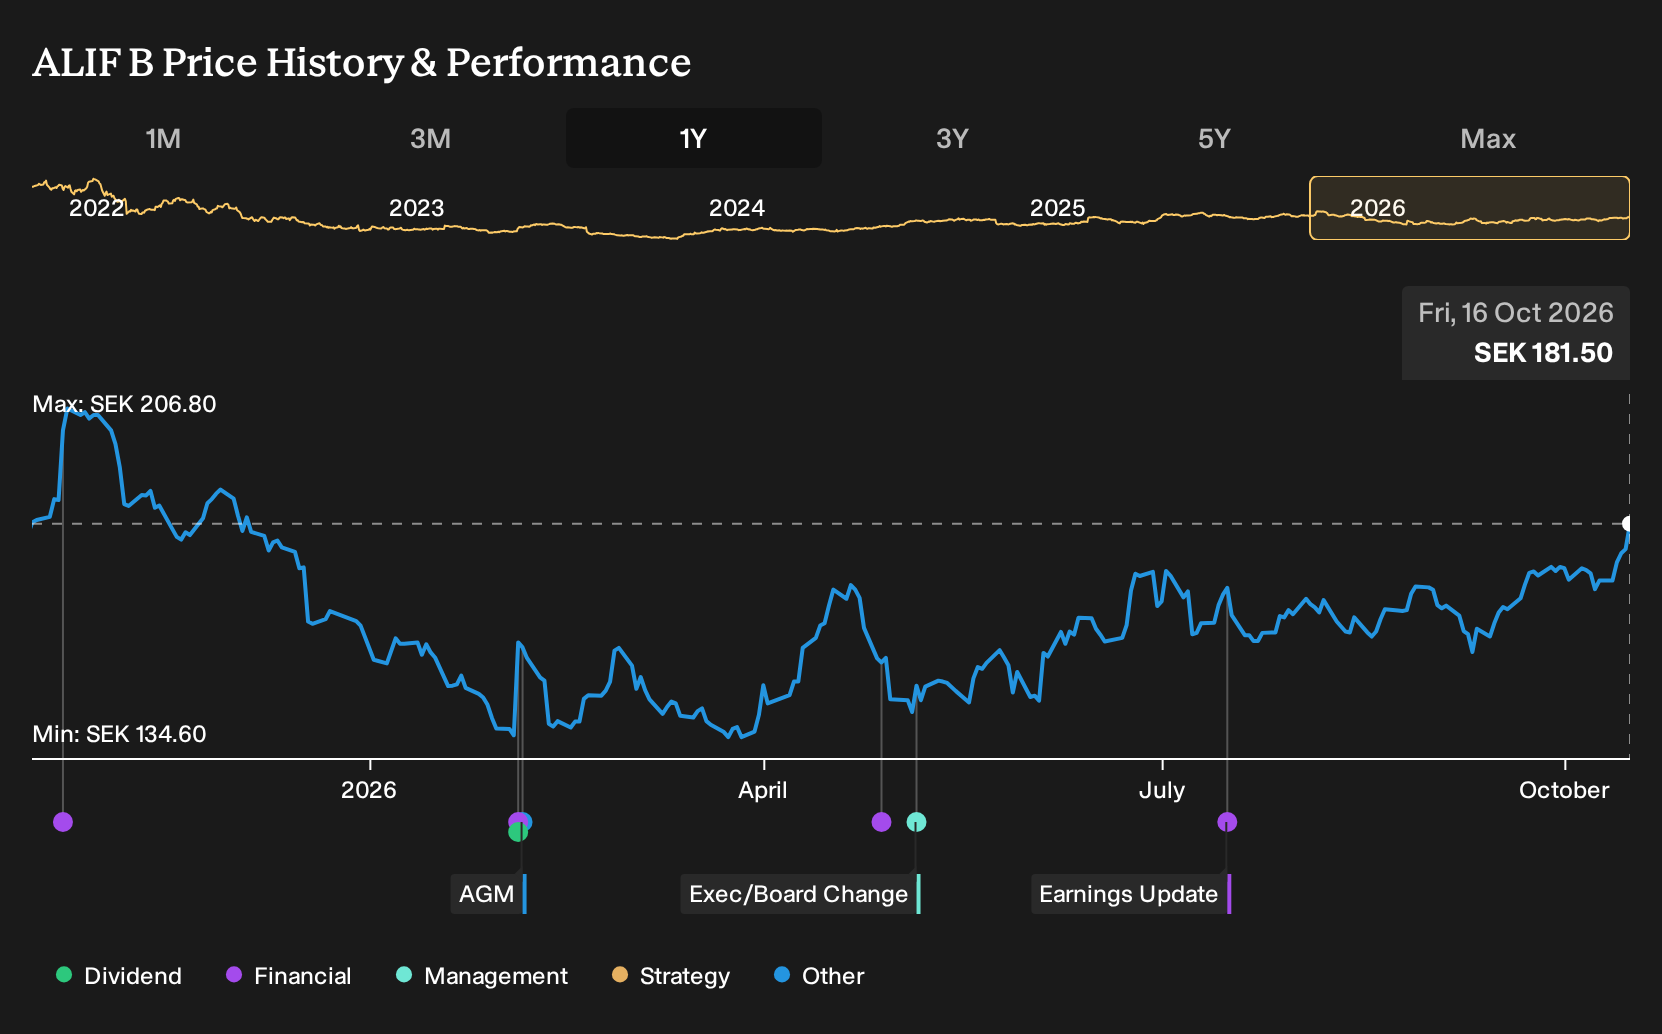
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between SEK 190 and about SEK 222, with one view at the top of that band hinting at a much richer AddLife valuation than the low end. You also need to weigh funding risk in academic research and supply chain pressure, which could reshape how these private investors reassess future free cash flow resilience.
Explore 2 other AddLife fair value estimates, including one that suggests it could be worth just SEK190.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AddLife research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AddLife. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AddLife's overall financial health at a glance.
Looking For More Investment Ideas Beyond AddLife?
If the AddLife story has sharpened your focus on cash generation and valuation, it can help to compare that lens across a wider watchlist using the Simply Wall St Screener.
- For investors who want potential mispricings without throwing quality out the window, scan a curated 614 high quality undiscovered gems that pair strong fundamentals with less crowded attention.
- If capital preservation is high on your agenda, filter for a 232 resilient stocks with low risk scores that target resilient balance sheets and steadier risk profiles than the broader market.
- Income focused readers can zero in on 215 dividend fortresses that aim to combine higher yields with durable business models.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com