


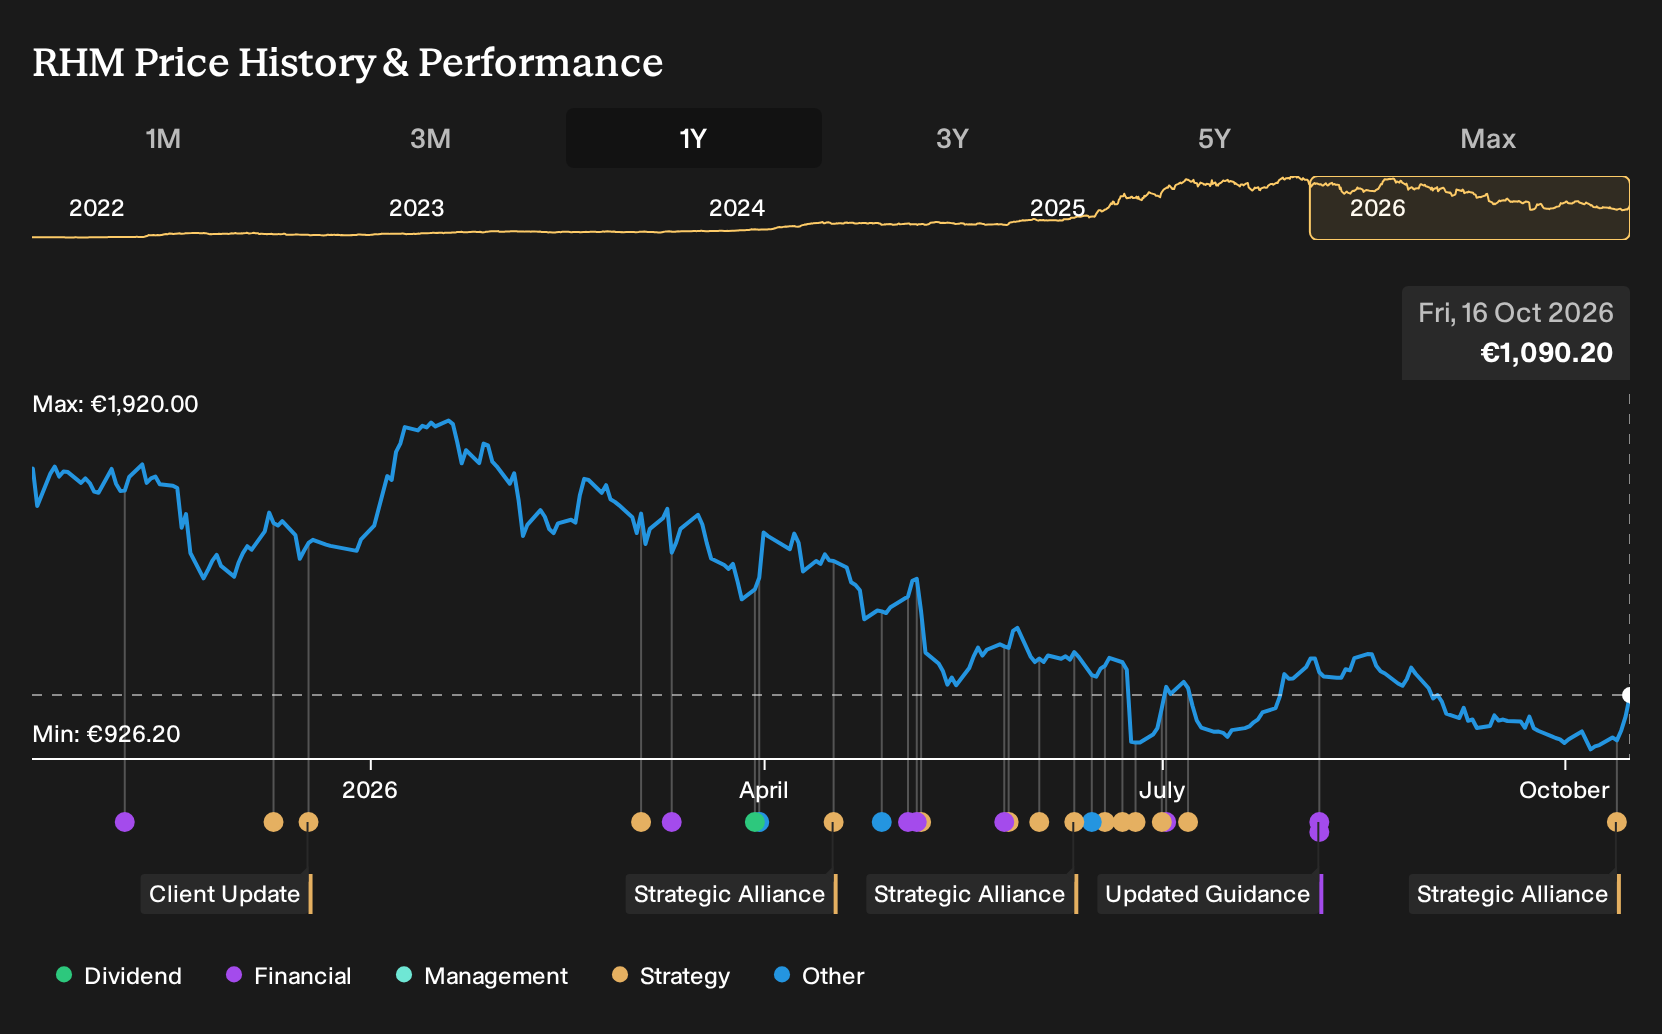
- In October 2026, Nel ASA and Rheinmetall AG signed a non binding MoU to combine Nel's electrolyser technology with Rheinmetall's Giga PtX and systems integration know how, with the aim of exploring decentralised renewable synthetic fuel production for defence and critical infrastructure.
- The focus on modular, local fuel production that can substitute conventional fuels without altering end use equipment highlights Rheinmetall's push into energy security solutions that are closely linked to its existing defence and infrastructure footprint.
- We will now examine how Rheinmetall's push into decentralised renewable fuel production could influence the wider investment narrative around defence energy security.
Scan beyond Rheinmetall and this MoU and line up other potential beneficiaries of the push for resilient defence energy supply with our curated 42 power grid technology and infrastructure stocks
Rheinmetall Investment Narrative Recap
To own Rheinmetall you need to believe the defence order backlog, higher European budgets and expansion into systems like autonomy can be turned into sustained, profitable volume. The Nel MoU plugs into that story by testing whether Rheinmetall can extend its energy security reach beyond hardware into fuel ecosystems. On its own, this is early stage.
The more immediate swing factors still look familiar. Converting a backlog above €80b into deliveries while dealing with capacity ramp risks, project delays and high working capital sits at the top of the list. The biggest near term risk remains program exposure and cash drain from inventory and capex if schedules slip again.
There are no fresh binding contracts directly tied to the Nel partnership yet, so attention likely stays on existing programs such as ammunition, vehicles and the planned ATACMS production hub in Unterlüß. Those efforts link more clearly to Rheinmetall’s stated ammunition backlog above €26b and the push to scale energetics capacity through 2027.
Viewed against that backdrop, the MoU reads more like optionality on future decentralised fuel ecosystems than a core driver of the current earnings path. Execution on plants, inventory unwinding and converting multi year German and NATO budget commitments into cash receipts still looks like the main operational catalyst investors will watch.
Rheinmetall's current analyst blueprint points to €28.0b in revenue and €3.9b in earnings by 2029, based on assumed yearly revenue growth of 34.9% and an earnings increase of about €2.7b from €1.2b today.
Uncover why Rheinmetall's fair value indicates a 44% potential upside to its current price. This gap could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view sees cash generation as the real fault line, not growth. The most bearish analysts were pencilling in about €27.0b of revenue and €3.3b of earnings by 2029, with a P/E of 18.8x, before this Rheinmetall and Nel MoU. That is a far more cautious story. Use it as a reminder that your own thesis should weigh several sharply different forecasts that may shift as this decentralised fuel angle develops.
Explore 6 other Rheinmetall fair value estimates, including one that suggests there may be as much as 6% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Rheinmetall research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rheinmetall. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rheinmetall's overall financial health at a glance.
Looking for more investment ideas beyond Rheinmetall?
If the Rheinmetall story has sharpened your focus on risk, cash generation and long term resilience, it can be useful to apply the same filters across a broader watchlist using the Simply Wall St screener.
- For investors who care most about valuation support and balance sheet strength, start with a curated set of 195 high quality undervalued stocks that combine cash flow support with financial resilience.
- If capital preservation and smoother return profiles sit higher on your priority list, narrow your search to a 231 resilient stocks with low risk scores that score well on Simply Wall St's risk framework.
- When you want potential upside without relying on widely followed large caps, cast a wider net across a 613 high quality undiscovered gems that pair quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com