


Why Generac Holdings Is Back In Focus
Generac Holdings (GNRC) is drawing attention after securing a multiyear Amazon contract tied to data center power needs, with deliveries projected at about US$2.4b for 2027 to 2028.
Generac Holdings has experienced a sharp swing, with the share price falling 11.76% over the past week and 10.63% over the past three months. At the same time, the year to date share price return is up 36.56% and the three year total shareholder return sits at 118.21%, which suggests momentum has cooled in the short term while longer term holders have still seen meaningful gains.
Scan how Generac Holdings compares with other companies exposed to data center and AI power demand by reviewing our hand picked 55 AI infrastructure stocks in the same space.
After a sharp pullback, but with a sizeable Amazon data center backlog still on the way, does Generac Holdings offer enough potential upside to justify the hit risk if expectations around those contracts and earnings prove too optimistic?
Most Popular Narrative: 33% Undervalued
The prevailing narrative values Generac Holdings at $289.56 per share using a 9.75% discount rate, compared with the recent close of $192.68. That gap frames a story where the Amazon contract and wider data center exposure sit alongside residential and telecom demand as key swing factors.
Accelerating AI driven build outs of hyperscale and colocated data centers are now supported by Generac Holdings having about US$450m of expected 2026 data center revenue, a US$1.6b dedicated backlog, and multiple multiyear hyperscale agreements including an Amazon deal projected at about US$2.4b of deliveries in 2027 to 2028. Together, these factors point to a multi year runway for higher C&I revenue and operating leverage.
See why 30 investors see Generac Holdings as 33% undervalued.
Result: Fair Value of $289.56 (UNDERVALUED)
Still, the Generac Holdings story can break if heavy capital spending on new capacity is not supported by data center demand, or if residential outages remain muted for longer.
Find out about the key risks to this Generac Holdings narrative.
Another View: What Multiples Say About Generac Holdings
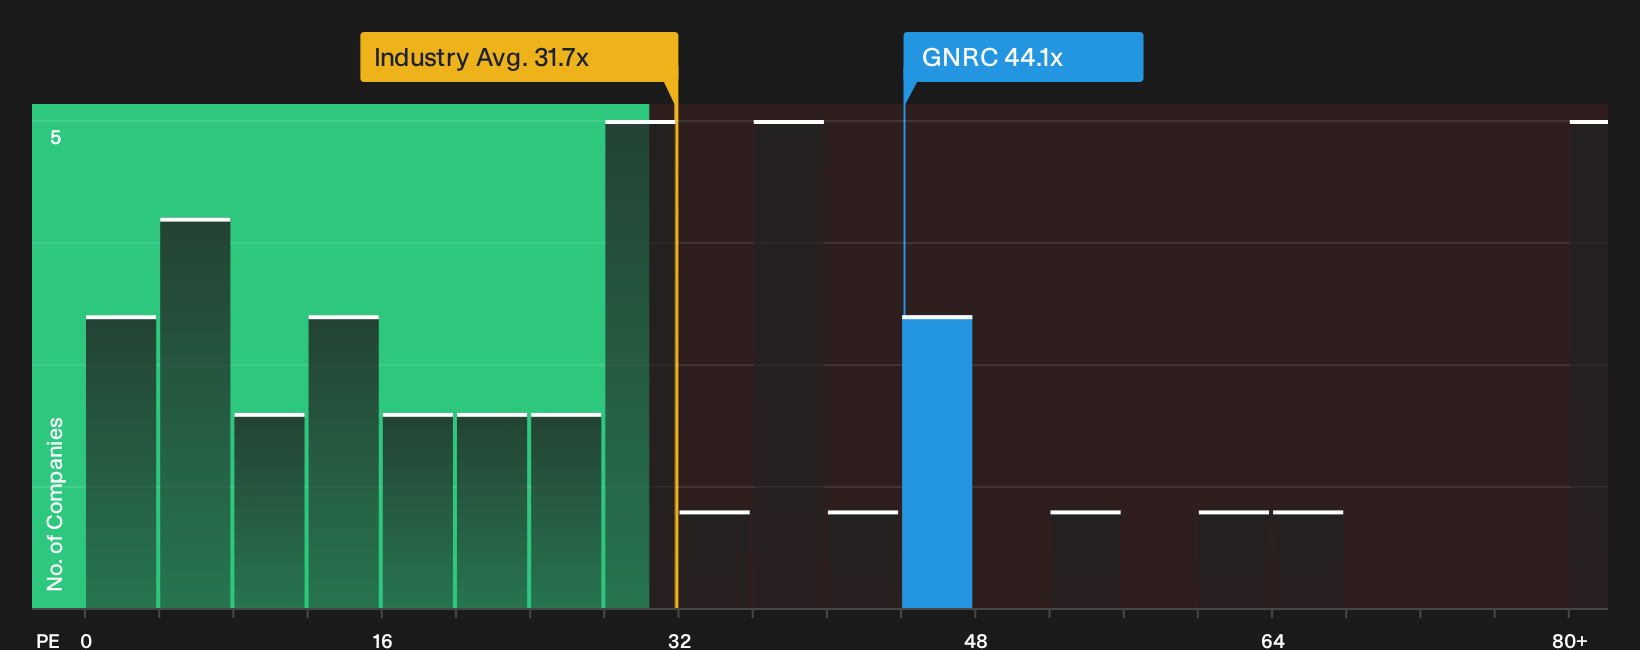
The story around Generac Holdings looks very different when framed through its current P/E ratio. The stock trades at 44.1x earnings, which is higher than the estimated fair ratio of 39.1x, the US Electrical industry on 31.7x, and peers on 32.5x. That gap points to valuation risk if sentiment cools, even with a strong data center narrative in play. How comfortable are you paying a premium multiple for a business already priced above its own fair ratio?
To pressure test that premium further, it is worth reviewing a detailed breakdown of the earnings multiple and how it compares with similar companies over time. You can then weigh that against your own expectations for Generac Holdings' growth and margins. See what the numbers say about this price — find out in our valuation breakdown.
For a quick visual check of how this premium has opened up against the wider group, examine the latest chart on relative earnings valuation versus peers and the sector.
Next Steps
Feeling torn between the enthusiasm in the Generac Holdings story and the valuation questions raised by its current P/E multiple? Act while the data is fresh, review the full picture yourself, and then weigh those potential benefits against your own risk tolerance by checking the 3 key rewards.
Looking For More Investment Ideas Beyond Generac Holdings?
Momentum in Generac Holdings is only one piece of your portfolio puzzle, and widening your opportunity set with focused screeners helps you spot ideas you might otherwise miss.
- Target potential mispricings by reviewing a curated 33 high quality undervalued stocks that blend strong fundamentals with appealing valuations before they move further onto the market's radar.
- Strengthen your resilience by scanning a 32 resilient stocks with low risk scores built around companies with steadier profiles that may help balance out higher volatility positions.
- Hunt for future standouts early by working through a 20 high quality undiscovered gems where quality metrics point to businesses the broader market has not fully focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com