


Restructuring optimism around Morgan Advanced Materials (LSE:MGAM) has become the main story, with investors focusing on projected margin gains and cost savings by 2026, as well as expectations for steadier free cash flow.
Recent trading reflects that optimism. Morgan Advanced Materials’ share price is £2.845, with a 30-day share price return of 14.72% and a 90-day share price return of 29.02%. The 1-year total shareholder return of 52.43% points to momentum that has been building rather than fading as restructuring and cash flow narratives gain traction.
Compare Morgan Advanced Materials' restructuring story with other industrials showing strong cash generation and potential valuation gaps by scanning our hand picked list of 7 high quality undervalued stocks.
After a 52% 1 year total return and a sharp recent move, the real puzzle with Morgan Advanced Materials is whether restructuring value is largely in the rear view mirror or if the valuation still leaves meaningful upside ahead.
Most Popular Narrative: 10% Overvalued
Morgan Advanced Materials closed at £2.845 compared with a widely followed fair value estimate of £2.59, which puts current enthusiasm ahead of that narrative and raises the question of how much future margin improvement is already reflected in the price.
The group's ongoing simplification programme, which will deliver £27 million of annual cost savings in 2026 and additional benefits from further upcoming optimization, creates a structurally lower fixed-cost base that enhances net margins and operating leverage as demand recovers.
See why 24 investors see Morgan Advanced Materials as 10% overvalued.
Result: Fair Value of £2.59 (OVERVALUED)
Still, the bullish Morgan Advanced Materials story could be knocked off course if semiconductor demand stays muted, or if core industrial customers continue to defer orders.
Find out about the key risks to this Morgan Advanced Materials narrative.
Another View: Cash Flows Paint A Different Picture
Analysts looking at Morgan Advanced Materials through earnings forecasts and price targets see a stock about 10% above a £2.59 fair value, which suggests some optimism already in the price. Our DCF model that focuses on future cash flows points in a very different direction and indicates value closer to £4.40 per share, which frames the current £2.85 level as materially below that estimate.
Two models, two answers, and one key question for you as an investor remains whether earnings-based targets or long term cash flow assumptions feel more realistic for Morgan Advanced Materials over the next few years.
Look into how the SWS DCF model arrives at its fair value.
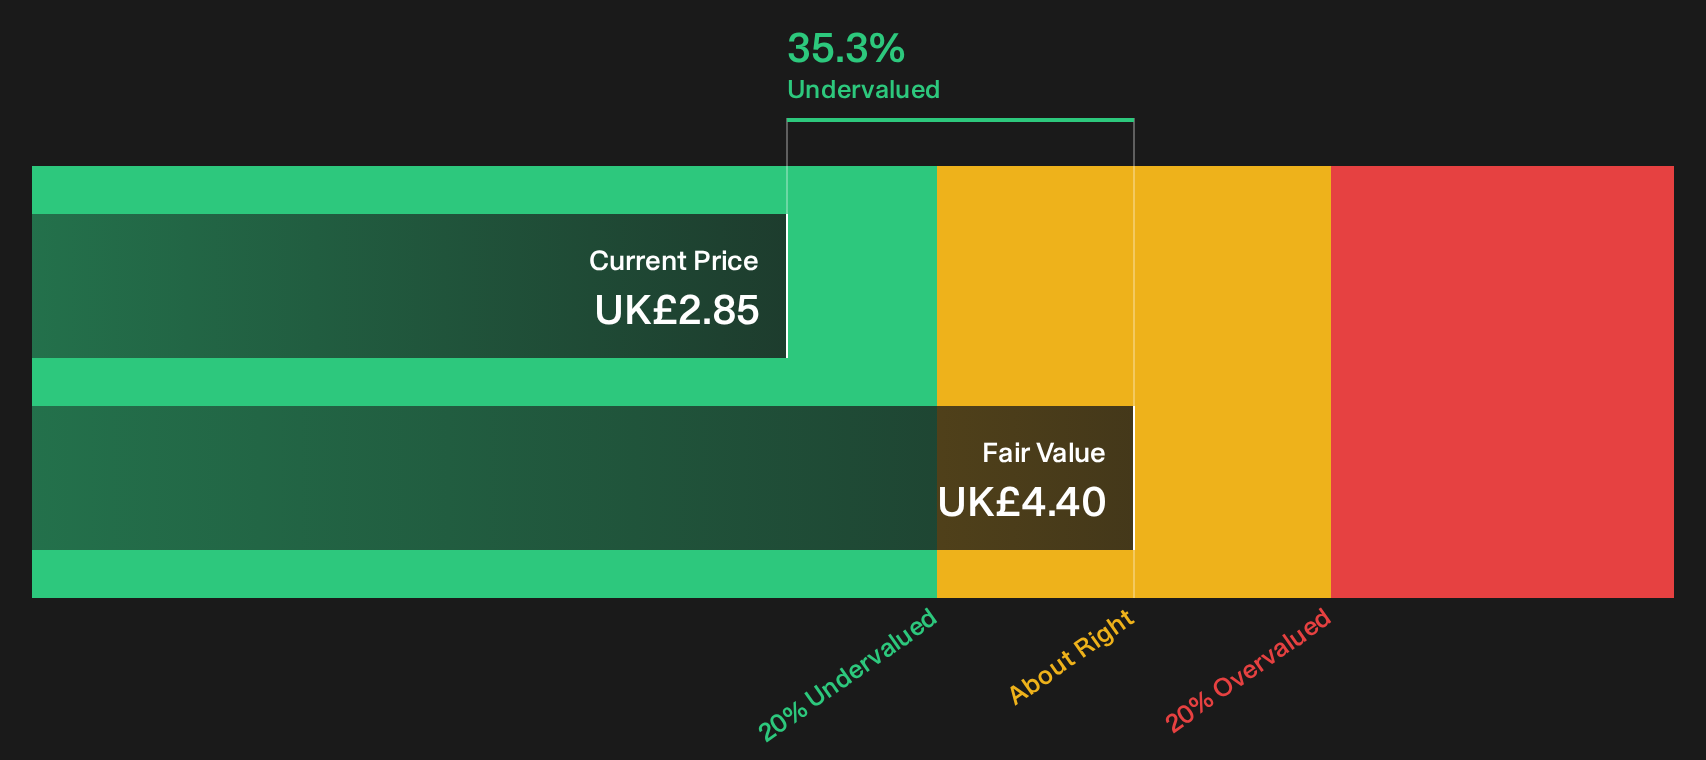
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Morgan Advanced Materials for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Morgan Advanced Materials story, with both risks and rewards in play, mean you benefit most by checking the numbers yourself and deciding quickly where you land. To see a concise breakdown of both sides of that equation, review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Morgan Advanced Materials?
If Morgan Advanced Materials has sharpened your focus on valuation and cash generation, do not stop here. Use the Simply Wall Street Screener to quickly surface fresh, data driven ideas that match your risk, income, and quality preferences.
- Target stronger long term balance sheet resilience by checking companies in the list of solid balance sheet and fundamentals (9 results).
- Hunt for mispriced quality where fundamentals and valuation may still be out of sync through the 5 high quality undiscovered gems.
- Prioritise stability and lower volatility potential in your portfolio construction by reviewing the 4 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com