


- Kawasaki Heavy Industries is in focus as investors react to projections that the group could shift from recent cash outflows to positive free cash flow, supported by activity in hydrogen infrastructure, aerospace and defense, precision machinery, robots, and rolling stock.
- The key angle is whether Kawasaki Heavy Industries can translate busy order books in hydrogen and high value aerospace and defense programs into durable cash generation rather than just headline revenue and profit figures.
- We will now explore how Kawasaki Heavy Industries' potential move into sustained positive free cash flow could reshape its broader investment narrative.
Gauge how Kawasaki Heavy Industries fits into the wider industrial shift by comparing it with a curated list of 92 robotics and automation stocks that captures similar automation and precision engineering themes.
Kawasaki Heavy Industries Investment Narrative Recap
To own Kawasaki Heavy Industries today, you need to be comfortable with a story that leans heavily on turning complex, long cycle projects into hard cash. Hydrogen infrastructure, aerospace and defense programs, precision machinery, robots, and rolling stock already underpin sizeable revenue, but the key belief is that these lines can convert more consistently into free cash flow rather than just accounting earnings.
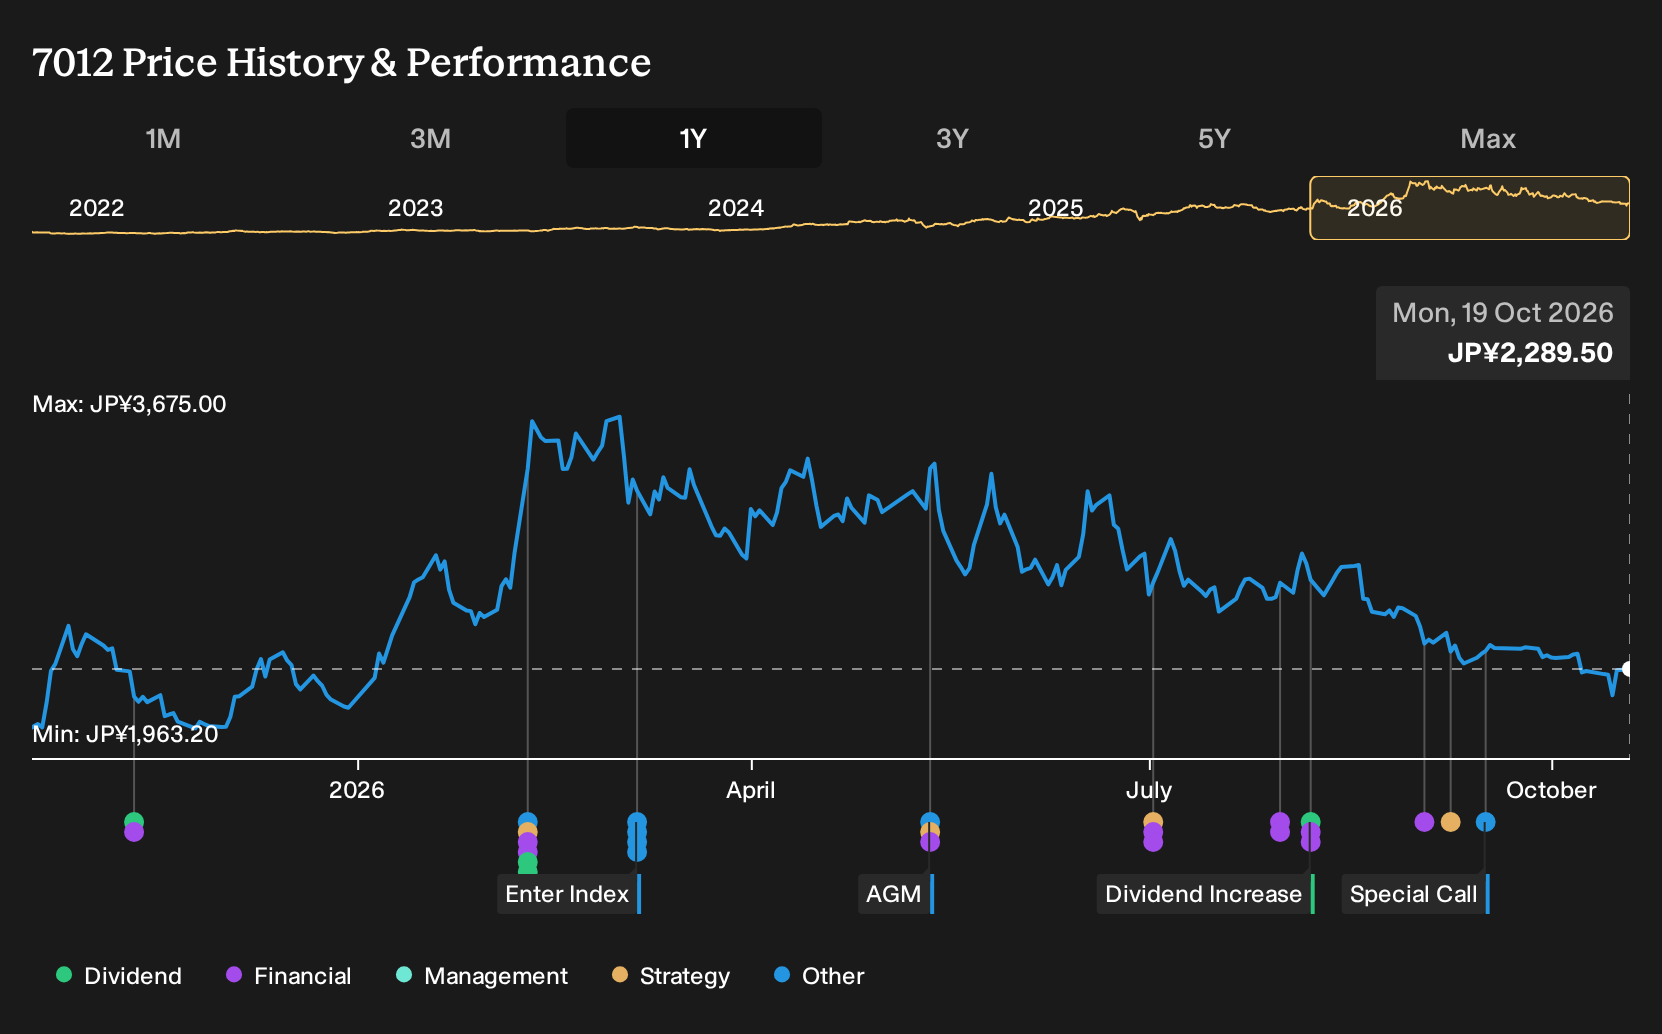
The recent share price move tied to expectations of a free cash flow swing does not change the near term hinge point. Execution on hydrogen and high value defense and aerospace work remains the main short term catalyst. The biggest near term risk stays the same as well, with tariffs, currency swings and funding needs potentially squeezing margins and limiting that cash conversion.
The planned ¥200b raise through new shares and convertible bonds sits closest to this cash flow debate. Proceeds are earmarked for aircraft engines, gas turbines, robotics systems and hydrogen infrastructure, all areas investors are watching as potential drivers of steadier cash generation. The announcement makes the cash conversion story more tangible, because it shows where Kawasaki Heavy Industries is putting fresh capital to work.
This funding plan also brings a clear trade off into focus. Extra equity can support large projects that might help free cash flow over time, but it also risks dilution if earnings and cash generation do not scale with the larger share base. For you as a shareholder, the key question is whether the hydrogen, aerospace and robotics investments funded by this raise can realistically support the cash recovery that the market is already starting to price in.
Kawasaki Heavy Industries' current analyst story points to revenues of ¥2.9503b and earnings of ¥164.6b by 2029. That profile assumes revenue growing at 7.6% each year and an earnings increase of about ¥45b from earnings today of ¥119.6b.
Uncover how Kawasaki Heavy Industries' fair value indicates a 57% potential upside to its current price, which could narrow quickly if Kawasaki Heavy Industries executes on its cash conversion plans.
Exploring Other Perspectives
One alternate view focuses on Kawasaki Heavy Industries’ capital raise as a potential catalyst rather than just a dilution risk. The most optimistic analysts were already modelling revenues of ¥3,250.9b and earnings of ¥197.8b by 2029 before this news. You can use this gap in expectations to explore how sentiment might shift from here.
Explore 3 other Kawasaki Heavy Industries fair value estimates, including one that suggests as much as 114% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kawasaki Heavy Industries research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kawasaki Heavy Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kawasaki Heavy Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Kawasaki Heavy Industries?
If the Kawasaki Heavy Industries story has you thinking about where else steady cash generation or balance sheet resilience might show up, the Simply Wall St Screener can help you widen the net without losing focus on quality.
- For investors who want potential mispricing with support from fundamentals, scan through 13 high quality undervalued stocks that already line up strong cash flows with solid financial positions.
- If income reliability matters most to you, focus on 29 dividend fortresses that combine higher yields with metrics aimed at payout sustainability.
- For a calmer ride through market swings, concentrate on 22 resilient stocks with low risk scores that score well on financial strength and business stability checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com