


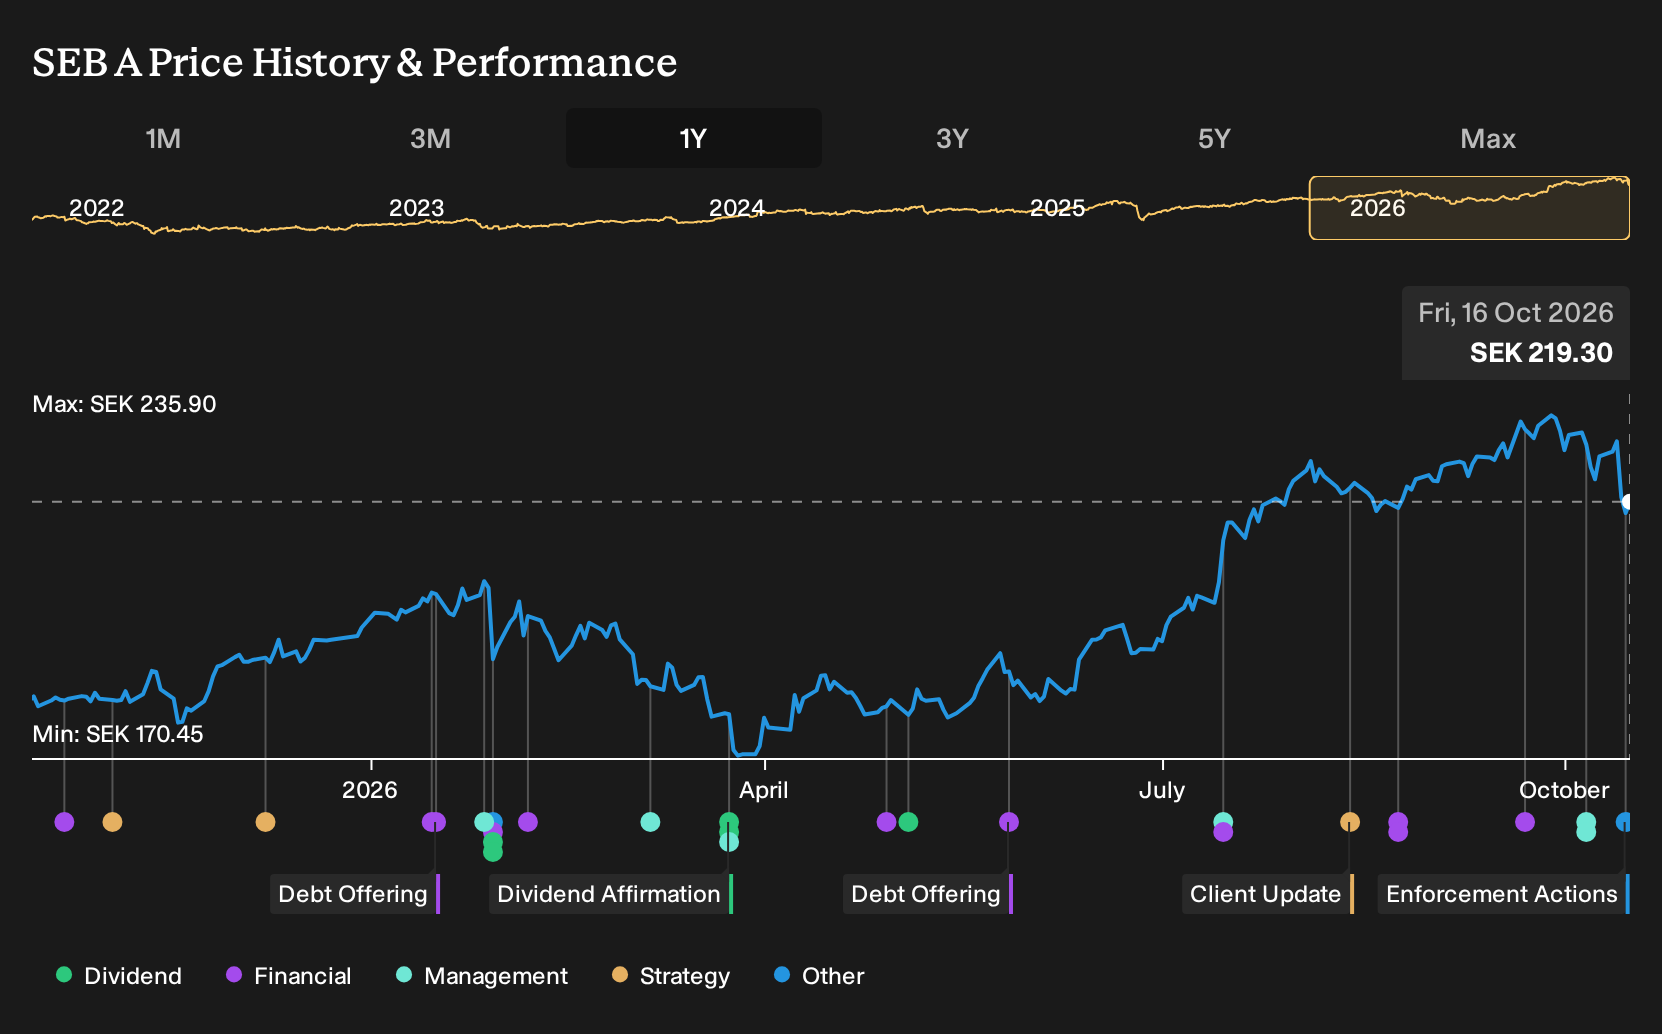
- Skandinaviska Enskilda Banken has resolved past U.S. investigations into historical anti money laundering controls in its Baltic operations and agreed to pay US$33 million, which the bank plans to book as a fourth quarter 2026 operating expense, with management indicating a limited financial impact and an unchanged full year cost target.
- The closure of these historical compliance reviews, alongside regulators acknowledging SEB’s cooperation and remediation efforts, reduces uncertainty around operational risks and frees up management focus for core banking priorities such as fee income growth, efficiency projects and broader client relationships.
- We will now explore how Skandinaviska Enskilda Banken's cleared U.S. AML matters could reshape its investment narrative around costs and risk.
Skandinaviska Enskilda Banken Investment Narrative Recap
For Skandinaviska Enskilda Banken, the big picture hinges on a clean regulatory profile, solid capital, and fee driven income from areas like Corporate & Investment Banking. The U.S. AML settlement looks small next to the group’s scale and is booked as an operating expense, so the key near term catalyst around fee and commission growth remains largely intact.
The bigger swing factor is still client activity. If corporate deal making or lending appetite softens, it may be harder for Skandinaviska Enskilda Banken to offset pressure from mortgage competition, levies and resolution fees. Regulatory costs stay a meaningful risk, even with the Baltic AML chapter closed.
The leadership switch on 6 October 2026, with Johan Torgeby stepping down and Jonas Ahlström becoming acting CEO and President, ties directly into execution risk around these catalysts. Continuity on priorities such as AI projects, cost control and deepening relationships with existing clients will likely be important, rather than a prolonged reset.
SEB’s board has started the recruitment process for a permanent CEO, so investors will likely pay close attention to how Ahlström and the eventual appointee handle regulatory engagement and operational efficiency. That leadership track record could influence confidence in fee income growth, capital allocation and any future balance between dividends and share buybacks.
Skandinaviska Enskilda Banken's current earnings are SEK 31.1 billion, with analyst consensus pointing to SEK 36.8 billion by 2029, which implies an increase of about SEK 5.7 billion. This outlook is accompanied by an assumed 5.3% yearly revenue growth profile and revenue forecasts of SEK 87.1 billion for 2029.
Uncover why Skandinaviska Enskilda Banken's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly SEK 227 at the low end to about SEK 390 at the top, so opinions on Skandinaviska Enskilda Banken already differ sharply. When you layer in the fresh U.S. AML resolution and the CEO transition, you gain additional reasons to compare several viewpoints before deciding how you see the bank.
Explore 2 other Skandinaviska Enskilda Banken fair value estimates, including one that suggests as much as 78% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Skandinaviska Enskilda Banken research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Skandinaviska Enskilda Banken. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Skandinaviska Enskilda Banken's overall financial health at a glance.
Looking For More Skandinaviska Enskilda Banken Style Ideas?
If Skandinaviska Enskilda Banken has you thinking about risk, income and balance sheet strength in a new way, use that framework to widen your opportunity set. The Simply Wall St Screener can help you spot other stocks with traits that fit how you like to invest.
- For investors who care most about resilience, start with a 231 resilient stocks with low risk scores that aim to keep drawdowns and surprises in check.
- If income reliability is high on your list, review a curated set of 219 dividend fortresses that focus on high yields supported by underlying business strength.
- When you want quality financial footing as a foundation, filter for a list of solid balance sheet and fundamentals (203 results) and see which companies match your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com