


Panic selling has gripped Indonesian equities after MSCI threatened to shift the country to standalone status, with the benchmark index sliding sharply and the rupiah under pressure. Forced selling can push solid businesses into the bargain bin, which is where disciplined investors often find their edge. This article walks through three Indonesian stocks exposed to this MSCI news shock and explains why some investors are watching them closely right now.
The three stocks below are just a sample pulled from this MSCI shock, while the full quantitative screen turned up 10 more Indonesian companies with equally compelling value and contrarian stories that are not covered here. If you want to quickly identify which of these beaten down Indonesian equities best fits your style, head straight into the Indonesia value and contrarian equities screener to filter, analyze, and focus on the highest conviction ideas.
Perusahaan Perseroan (Persero) PT Telekomunikasi Indonesia (IDX:TLKM)
Overview: Perusahaan Perseroan (Persero) PT Telekomunikasi Indonesia is Indonesia’s flagship telecom and ICT provider, delivering mobile, home connectivity, enterprise solutions, wholesale networks, and digital services that underpin day to day communications and data usage.
Operations: Telkom Indonesia generates about IDR 111t from B2C, IDR 61.9t from B2B infrastructure, and IDR 29.9t from other services, with roughly IDR 141t earned domestically and IDR 8.6t abroad.
Market Cap: IDR 187.3t
Telkom Indonesia is a flagship example of the Indonesia value and contrarian equities theme. A large, cash generative telecom group has seen its share price affected by MSCI related selling and short term sentiment rather than a sudden change in its core digital connectivity role.
"Expansion in the B2B segment, focusing on digital connectivity supported by platform expansion, particularly data centers and cloud services, points to potential sustainable revenue growth and improved earnings as these sectors offer higher margins."
What happens to Telkom Indonesia’s margin story if a single key pressure around capital intensity and pricing shifts even slightly in its favor?
If that pressure eases even slightly, read the full narrative for Perusahaan Perseroan (Persero) PT Telekomunikasi Indonesia to see how Telkom Indonesia’s capital cycle, cash profile, and dividend capacity could be decoupling from sentiment-driven selling.
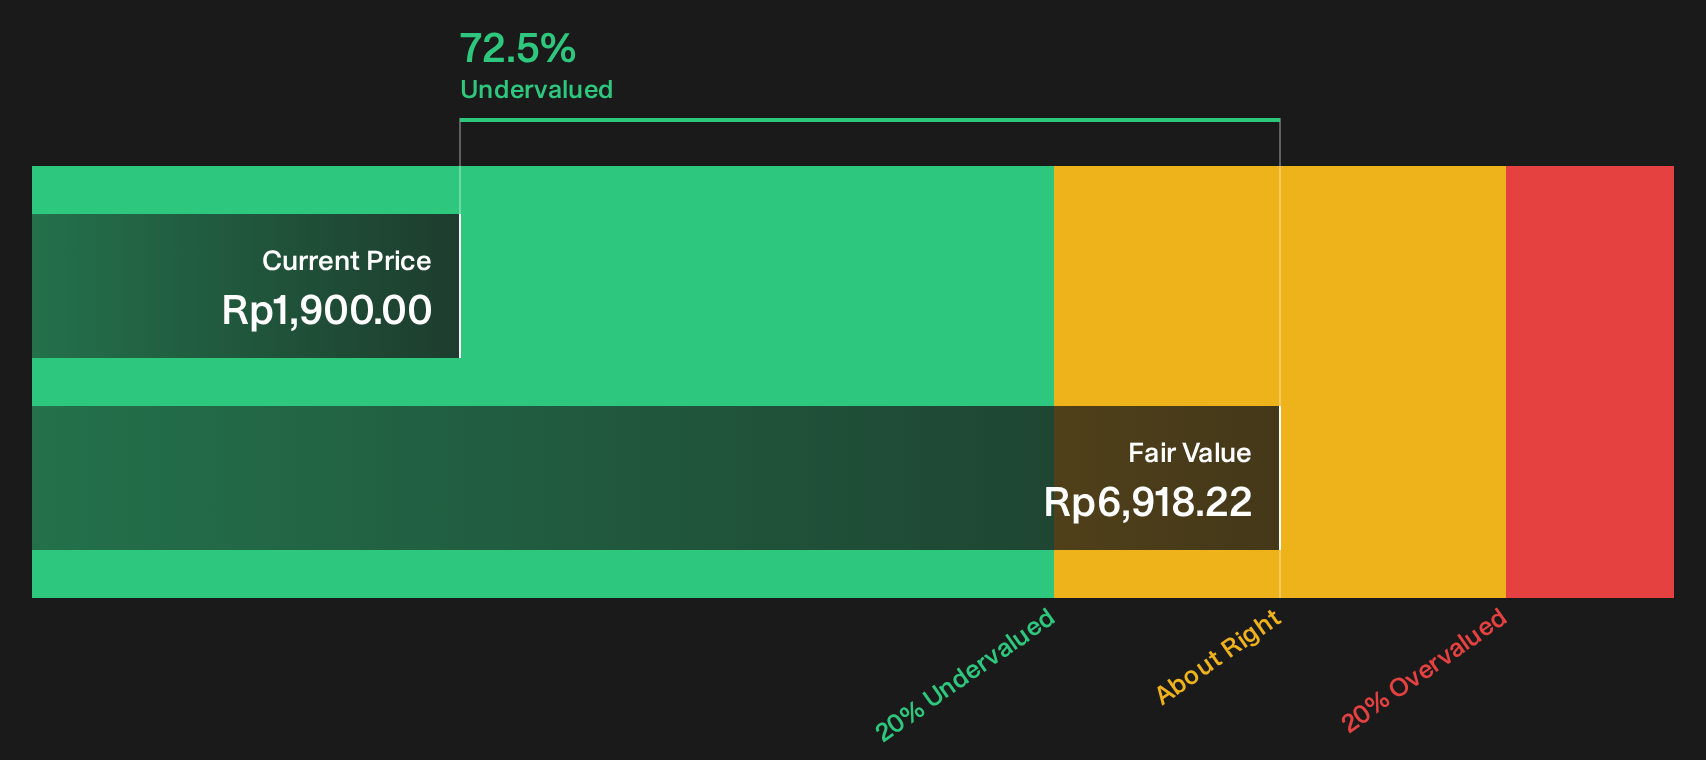
XLSMART Telecom Sejahtera (IDX:EXCL)
Overview: XLSMART Telecom Sejahtera runs a nationwide Indonesian telecom and multimedia business, serving consumers and enterprises with mobile, data, and digital connectivity, placing it squarely in the Indonesia value and contrarian equities theme.
Operations: XLSMART Telecom Sejahtera generates about IDR 46.9b from GSM mobile and network services and IDR 0.5b from managed IT services, almost entirely in Indonesia.
Market Cap: IDR 33.0t
For investors filtering the Indonesia value and contrarian equities list for liquid telecoms, XLSMART Telecom Sejahtera brings something different, a business where headline pressure from flows and accounting noise sits beside a more interesting usage and profitability story.
"XLSMART Telecom Sejahtera is already seeing data traffic grow despite a smaller mobile subscriber base. This points to an underappreciated route to revenue growth if higher usage per remaining user continues to feed into pricing power and a richer ARPU mix."
The real swing factor is whether one evolving pressure on unit economics tilts far enough to reshape what long term margins look like.
If that margin tilt proves real, read the full narrative for XLSMART Telecom Sejahtera to see how XLSMART Telecom Sejahtera’s usage trends and MSCI driven volatility intersect with long term earnings power.

Indosat (IDX:ISAT)
Overview: Indosat is a major Indonesian telecom and digital services provider, offering mobile, broadband, enterprise connectivity, cloud, and consumer digital products nationwide.
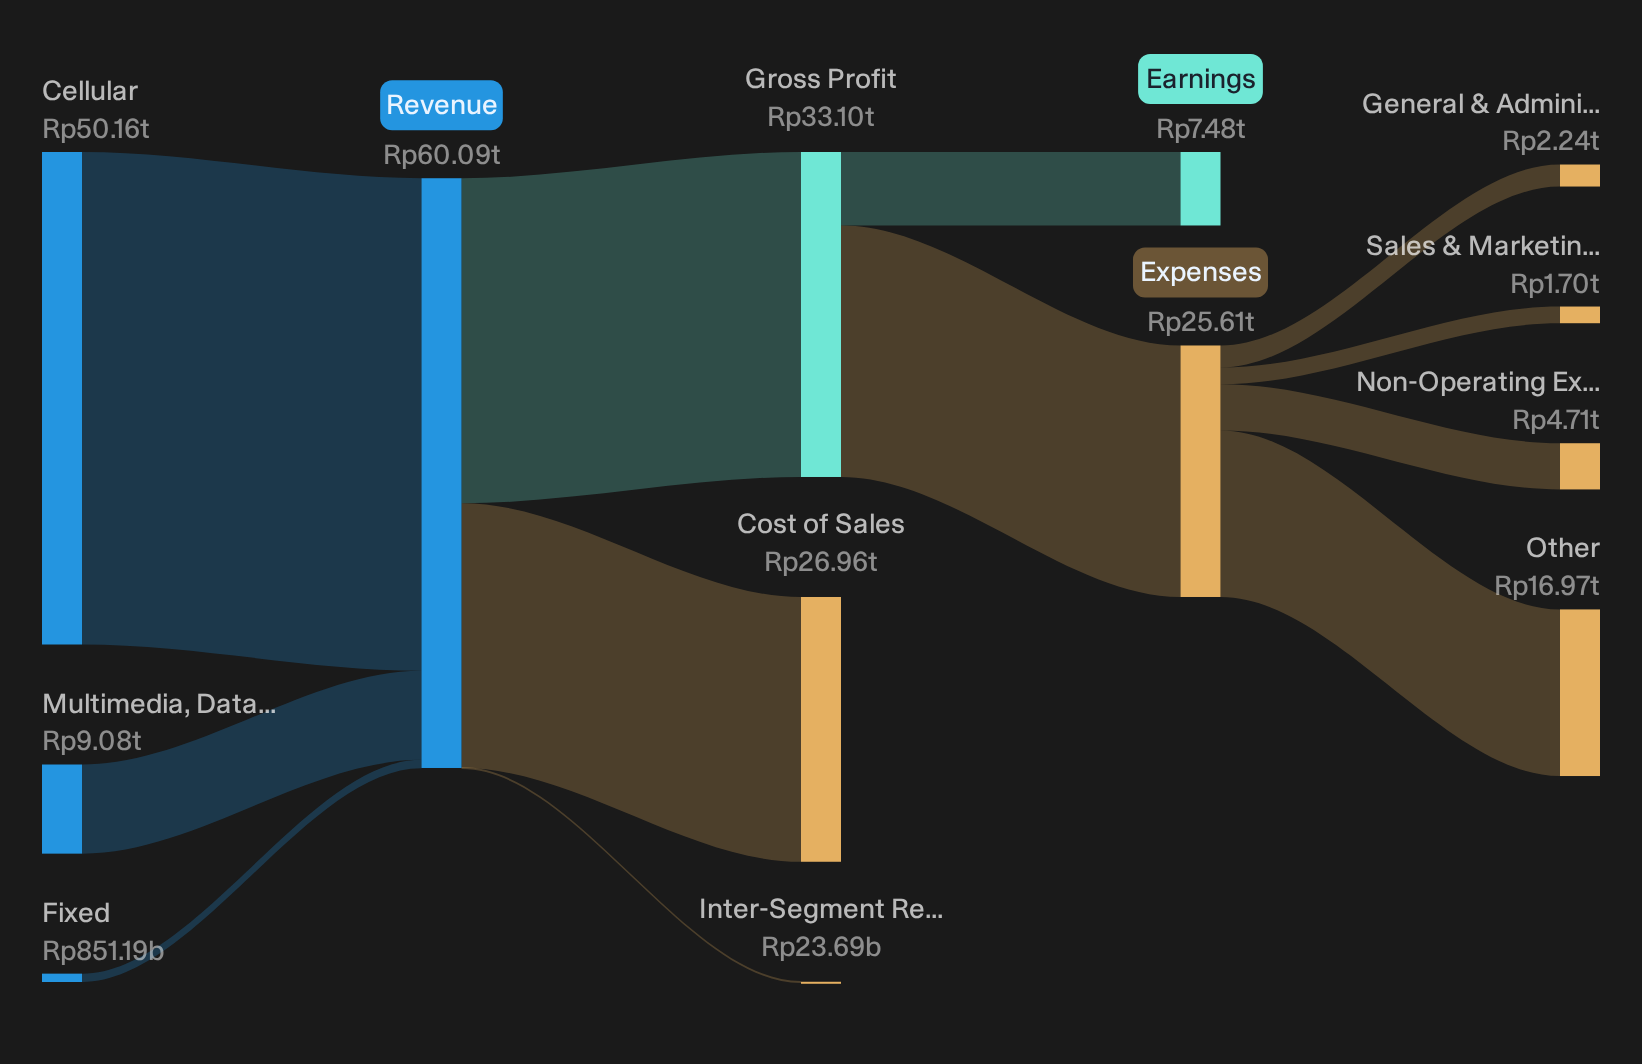
Operations: Indosat generates about IDR 50.2b from Cellular, IDR 9.1b from Multimedia, Data Communication, Internet, and IDR 0.9b from Fixed services, almost all in Indonesia.
Market Cap: IDR 56.6t
Indosat sits right in the sweet spot of this Indonesia value and contrarian equities theme. It is a high profile telecom stock where improving operations meet sharp price pressure from technical selling and MSCI related worries.
"Although Indosat is currently lifting customer ARPU with higher value bundles and personalization, the sharp step up in incentive linked personnel expenses of 52% year on year in Q1 2026 risks absorbing much of that ARPU led revenue, which could limit the flow through to EBITDA margin improvement and earnings growth."
This raises the question of what happens to Indosat’s earnings story if one cost pressure shifts just enough to either protect or squeeze those improving margins.
If that cost lever really starts to shift, reading the full narrative for Indosat shows how Indosat’s incentive burden could be masking an accelerating earnings story.
Curious To Explore Alternative Ideas?
Fresh opportunities move fast. Some are breaking out, some are dropping, and a few are still under the radar for now. Check these ideas before the crowd and act now.
- Target resilient cash generators that keep balance sheet stress contained by screening a curated list of solid balance sheet and fundamentals (203 results) while it still flies under most investors’ radars.
- Hunt for income opportunities by tracking hand picked 218 dividend fortresses that may help anchor a portfolio when momentum turns choppy, so you are not caught chasing yield late.
- Position for structural infrastructure themes by reviewing focused 42 power grid technology and infrastructure stocks before capital flows reprice these stories and the easy entry points are gone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com