


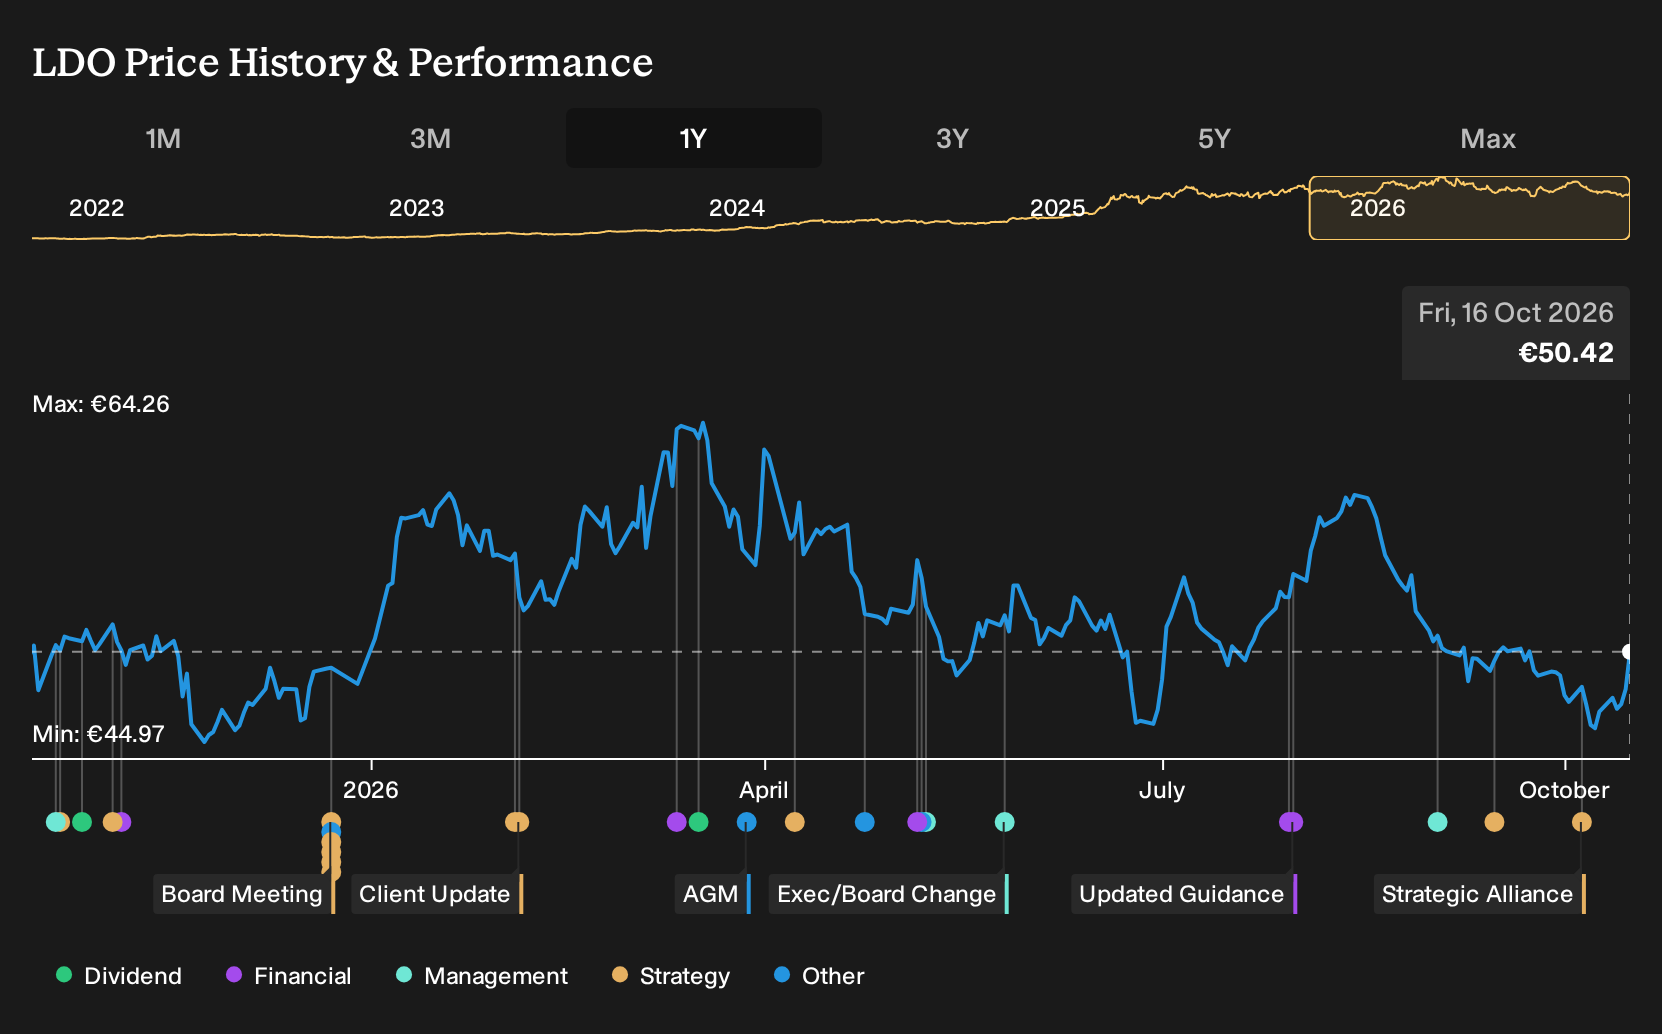
- In early October 2026, Unibap Space Solutions announced a collaboration with Leonardo's Space Division to adapt Unibap's iX20 edge computing platform for defense and emergency space applications, supporting onboard processing for Leonardo's SAR and electro optical Earth observation constellation.
- The partnership signals a push for Leonardo to move satellites from simple data collectors to in orbit analytics platforms, which could influence how its defense electronics and space offerings create value for government and security customers.
- We now examine how Leonardo's investment narrative could shift as onboard satellite processing becomes central to its space strategy.
Leonardo Investment Narrative Recap
To own Leonardo, you need to believe the shift toward higher margin defence electronics, space and security solutions can carry more weight than problem areas like Aerostructures and integration work. The Unibap partnership fits that story, since it leans into ISR, onboard processing and multi domain systems that are already central to the group playbook.
In the near term, the key swing factor still looks like execution on the existing defence upcycle and large programs such as Michelangelo and GCAP, while keeping Aerostructures cash drain and governance noise contained. This edge computing move in space is helpful for the narrative, but probably not the main short term catalyst or risk.
Among the recent themes around Leonardo, the push from pure defence contractor toward a wider security solutions role is closest to what this Unibap deal is about. Management has talked about targeting at least €1.5b of orders from areas such as precision agriculture and catastrophe monitoring, using cyber, drone, AI and space capabilities.
Turning raw satellite data into real time intelligence fits that broader plan. If the firm executes, ISR focused constellations with in orbit analytics could support that additional order pool and help mix more business toward Defence Electronics and Space. The operational watchpoint is delivery and uptake of these offerings while large integrations and Aerostructures remain work in progress.
What The Consensus Leonardo Forecasts Assume
On the numbers, analyst models around Leonardo lean on a clear set of revenue and earnings assumptions that sit behind the current space and ISR story. Forecasts point to revenue growth of 11.0% a year over the next three years, earnings today of €1.1b, and a consensus earnings target of €2.1b by 2029. That implies an earnings increase of about €1.0b from current levels.
Leonardo's narrative projects €28.2b revenue and €2.1b earnings by 2029. This requires 11.0% yearly revenue growth and about €1.0b earnings increase from €1.1b today.
Uncover why Leonardo's fair value indicates a 35% potential upside to its current price before that discount begins to narrow.
Exploring Other Perspectives
One alternate view focuses on governance risk at Leonardo. The most cautious analysts, who were only pencilling in about €28.0b revenue and €1.7b earnings by 2029 before this Unibap ISR deal, see political interference as a ceiling on valuation. This partnership can be treated as a test of whether that story shifts.
Explore 4 other Leonardo fair value estimates, including one that suggests it could be worth just €55.66.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Leonardo research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Leonardo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leonardo's overall financial health at a glance.
Looking for more investment ideas beyond Leonardo?
If the Leonardo story has sharpened your view on defence, space and security, it can help to line it up against other opportunities that fit different risk and return profiles. The Simply Wall St Screener lets you scan the market quickly, filter by fundamentals and build a watchlist that matches your own thesis rather than someone else's.
- If capital preservation sits near the top of your priorities, start with a basket of companies that screen well for resilience and stability through the 231 resilient stocks with low risk scores.
- For readers hunting for quality at a reasonable tag, broaden your watchlist with a carefully filtered 192 high quality undervalued stocks that couples stronger balance sheets with solid cash generation.
- Income focused investors who care about cash flow today rather than just long term upside potential can draw on a curated 218 dividend fortresses that emphasises higher yielding payouts with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com