


UK small caps linked to everyday spending are being squeezed by profit warnings, pricier energy and higher borrowing costs, yet possible business rates relief creates a rare twist in the story. When pressure on profits collides with targeted tax support, mispricing can appear in places investors often overlook. This article walks through three UK domestic service and retail stocks exposed to that policy debate, and explains why they might deserve closer attention.
The three stocks below are just a starting sample, and the full screen surfaced 11 more UK small caps in domestic retail and services with equally compelling policy and business narratives that are not covered here. To go wider and spot candidates that better fit personal risk, income or recovery themes, head straight into the UK Small-Cap Domestic Services and Retail Benefiting from Business Rates Relief screener to identify, compare and analyze the highest conviction plays.
Tortilla Mexican Grill (AIM:MEX)
Tortilla Mexican Grill runs fast casual Mexican restaurants and franchises like Tortilla and Chilango across the UK high street, where smaller leased units could benefit directly if business rates relief for local hospitality operators comes through.
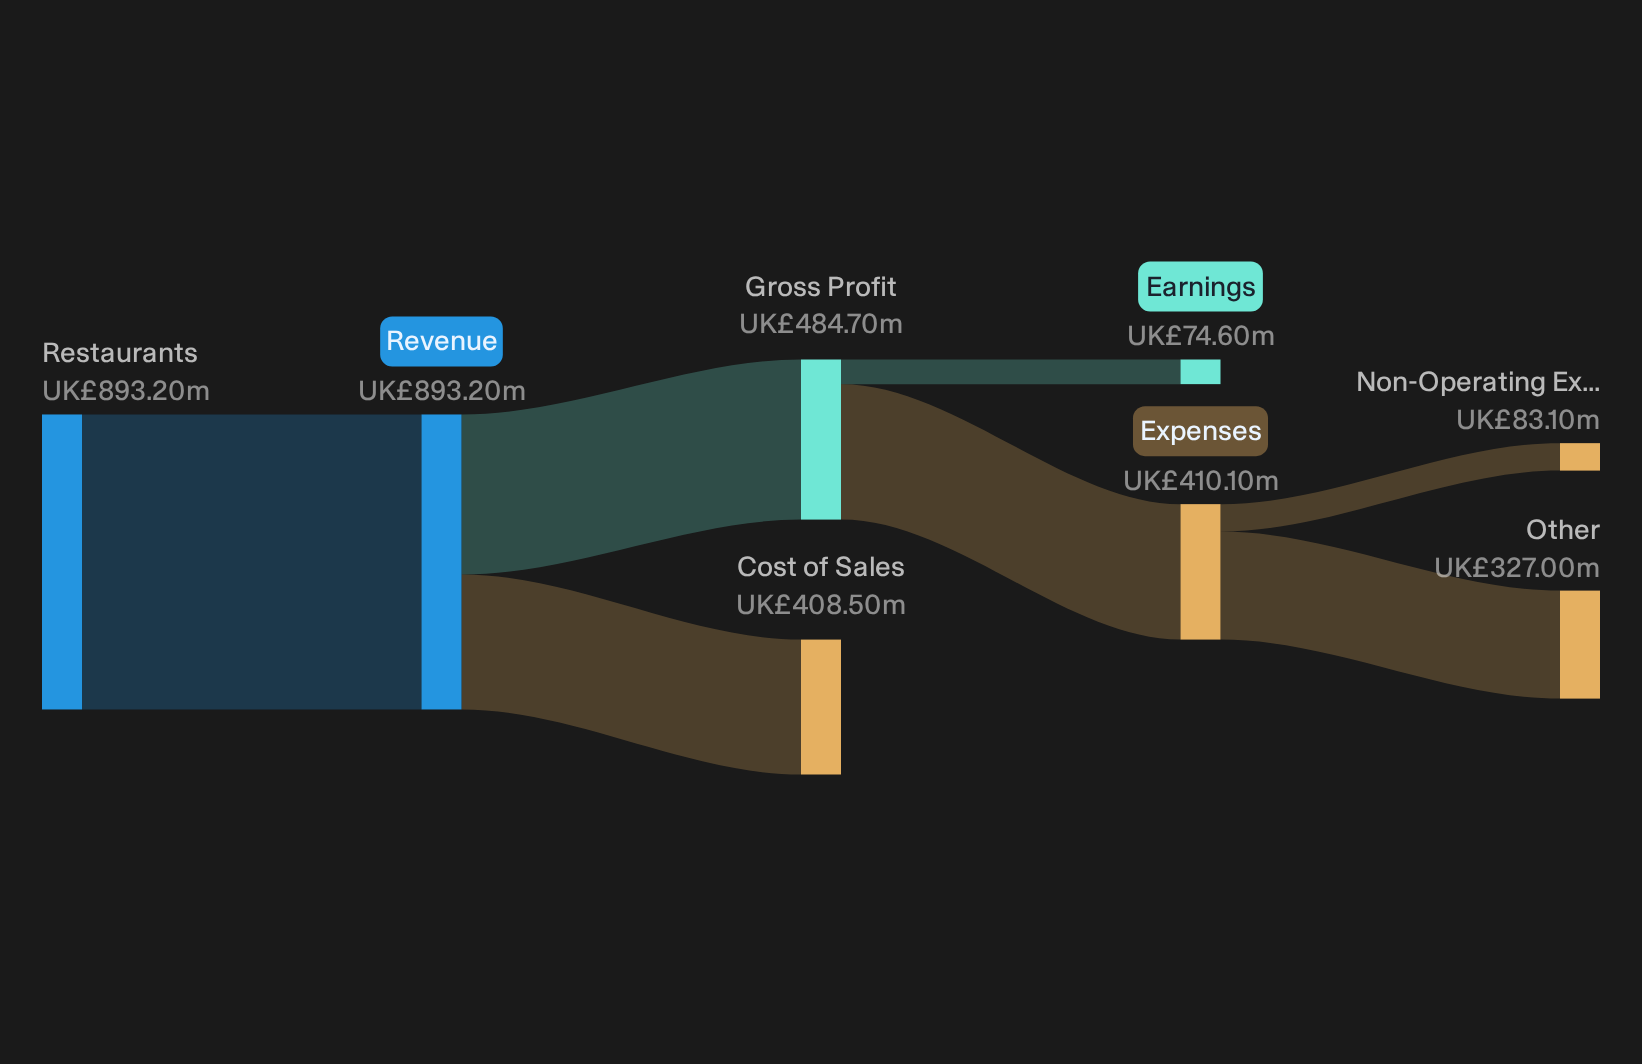
Tortilla Mexican Grill focuses on burritos, bowls and quick service dining across company operated and franchised outlets, with most of its £69.7 million geographic revenue base coming from the United Kingdom, and the stock valued at about £27.1 million by market cap.
"Rollout of self ordering kiosks and an upgraded Burrito Society loyalty app across most of the U.K. estate is lifting average transaction values and conversion."
What really matters next is how one unresolved pressure shapes the path for unit level margins and cash generation across that estate.
That pressure point is exactly what the full narrative for Tortilla Mexican Grill unpacks, showing where Tortilla Mexican Grill may be decoupling from headline worries and where risks could still bite.

Marston's (LSE:MARS)
Marston's gives this business rates relief theme real weight, because it runs a large community pub estate where smaller venues sit closest to the proposed tax support and where modest shifts in cost or customer habits can move the investment story quickly.
"Although the new Grandstand, Two Door and other formats are currently producing strong uplift in sales per pub, the plan to accelerate conversions to around 100 pubs a year increases execution risk if consumer preferences for event-led and sports-led occasions soften."
What matters most for Marston's is how one quiet assumption about future guest behavior plays out against that heavier conversion spend.
If that guest behaviour assumption is the real swing factor, the full narrative for Marston's shows where Marston's risk may be masking a potentially stronger recovery story.
ProCook Group (LSE:PROC)
ProCook Group is a UK kitchenware retailer in the sweet spot of this business rates themed screen, with high street stores that could benefit if fixed tax costs ease and a growing ecommerce arm that keeps it plugged into online demand.
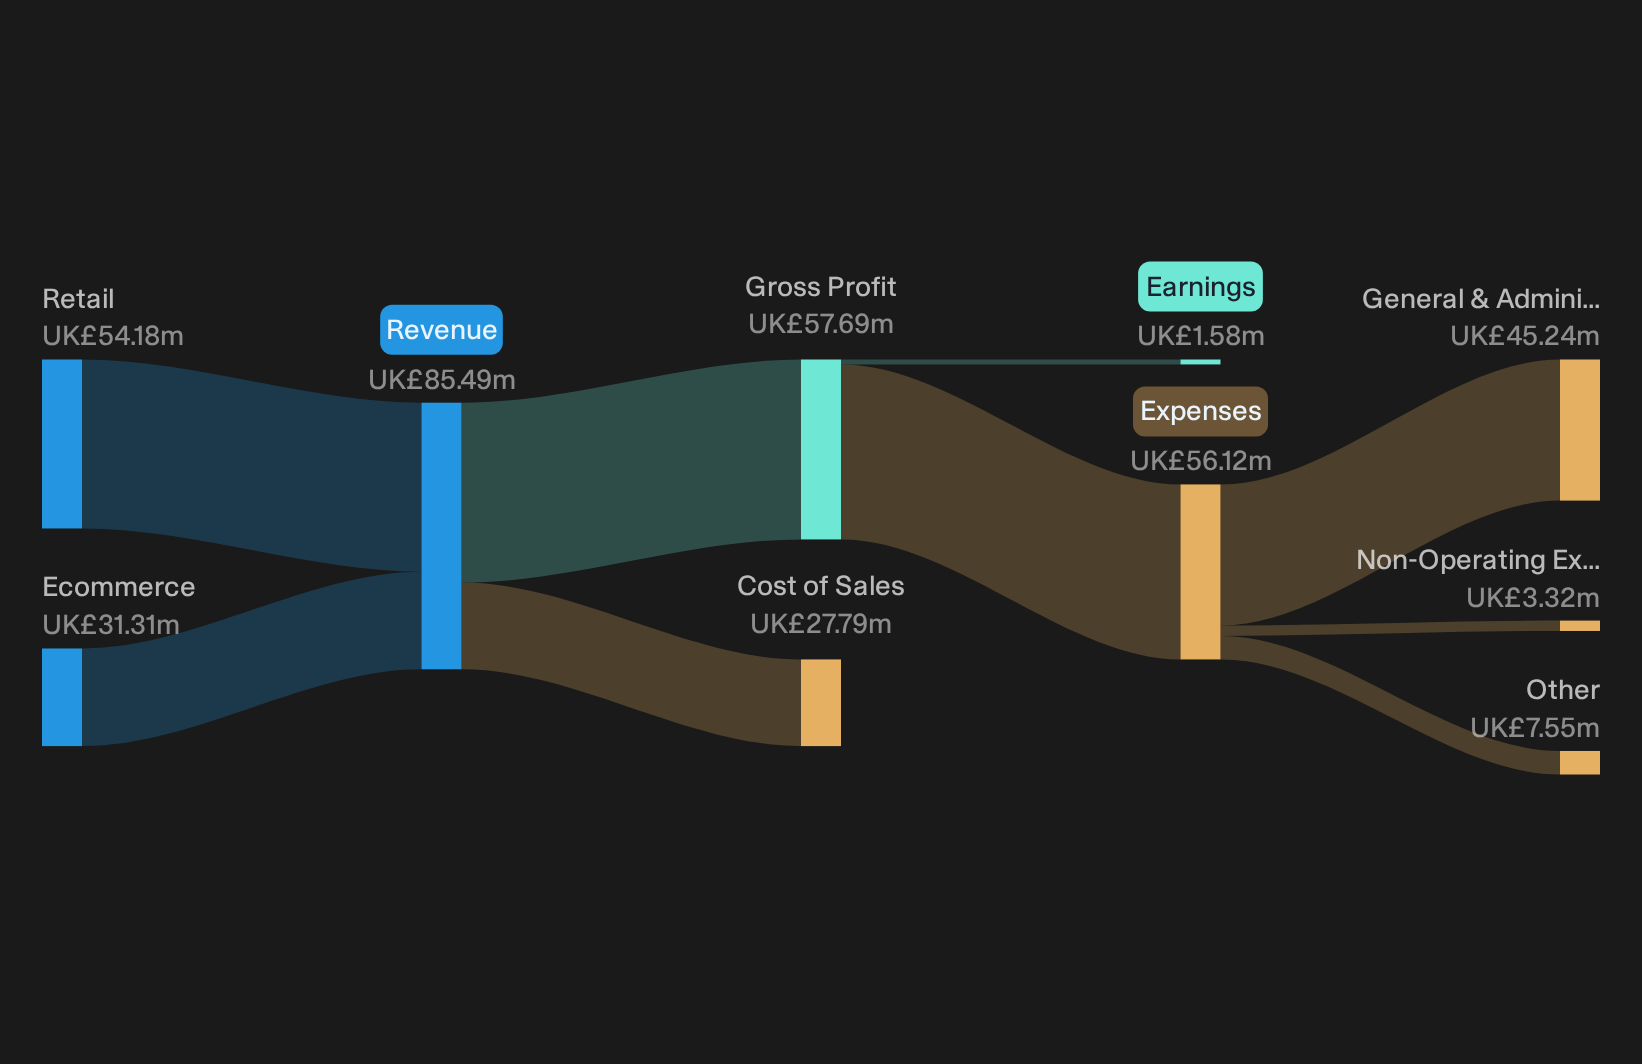
ProCook Group generated £54.2 million from retail stores and £31.3 million from ecommerce, all in the UK, and carries a market value of about £50.1 million.
For investors watching UK domestic retailers, ProCook Group offers a cleaner, kitchen focused angle on the rates relief story that is tightly linked to how fast its store footprint grows and how much of that extra scale drops into profit.
"ProCook is accelerating its profitable sales growth strategy by expanding its store network, planning to open 100 UK stores."
What really counts now is how one pressure on everyday profitability shifts as those extra leases meet consumer demand and any changes to business rates.
That profitability pressure is exactly where the full narrative for ProCook Group accelerates the story, revealing how ProCook Group’s expansion plan and business rates relief could reshape risk and upside.
Seeking Alternatives Before The Crowd?
Fresh breakouts and early momentum often get caught quickly, then the edge drops as they stop flying under the radar for now. Scan what matters first and get in early.
- Spot resilient cash generators before they hit every watchlist by running the list of solid balance sheet and fundamentals (9 results) while the best candidates are still quietly priced.
- Track income machines built for durability with the 4 dividend fortresses and see which high yielders keep cash flowing even when sentiment turns.
- Ride secular growth stories tied to AI infrastructure by scanning the 55 AI infrastructure stocks before capital floods into the same crowded basket.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com