


Erie Indemnity (ERIE) has drawn fresh attention after recent trading left the stock at US$243.71, with short term moves contrasting with weaker year and multi year total returns for shareholders.
Recent trading has given Erie Indemnity a short burst of positive momentum, with a 1 day share price return of 2.1% and a 7 day gain of 8.3%. This comes even though the year to date share price return is down 12.3% and the 1 year total shareholder return has declined 21.2%, suggesting the latest move may reflect a shift in sentiment around its risk profile or earnings power rather than a sustained trend so far.
Compare Erie Indemnity's recent volatility with a hand picked group of insurers and financials screened for resilient balance sheets and fundamentals through our list of solid balance sheet and fundamentals (25 results).
Erie Indemnity appears to be a solid, fee-based insurer support business. However, the share price has moved from double-digit declines over 1 year to a sharp short-term rebound. Is that quality now selling at a fair price or at a stretch?
Preferred P/E of 22.1x for Erie Indemnity: Is it justified?
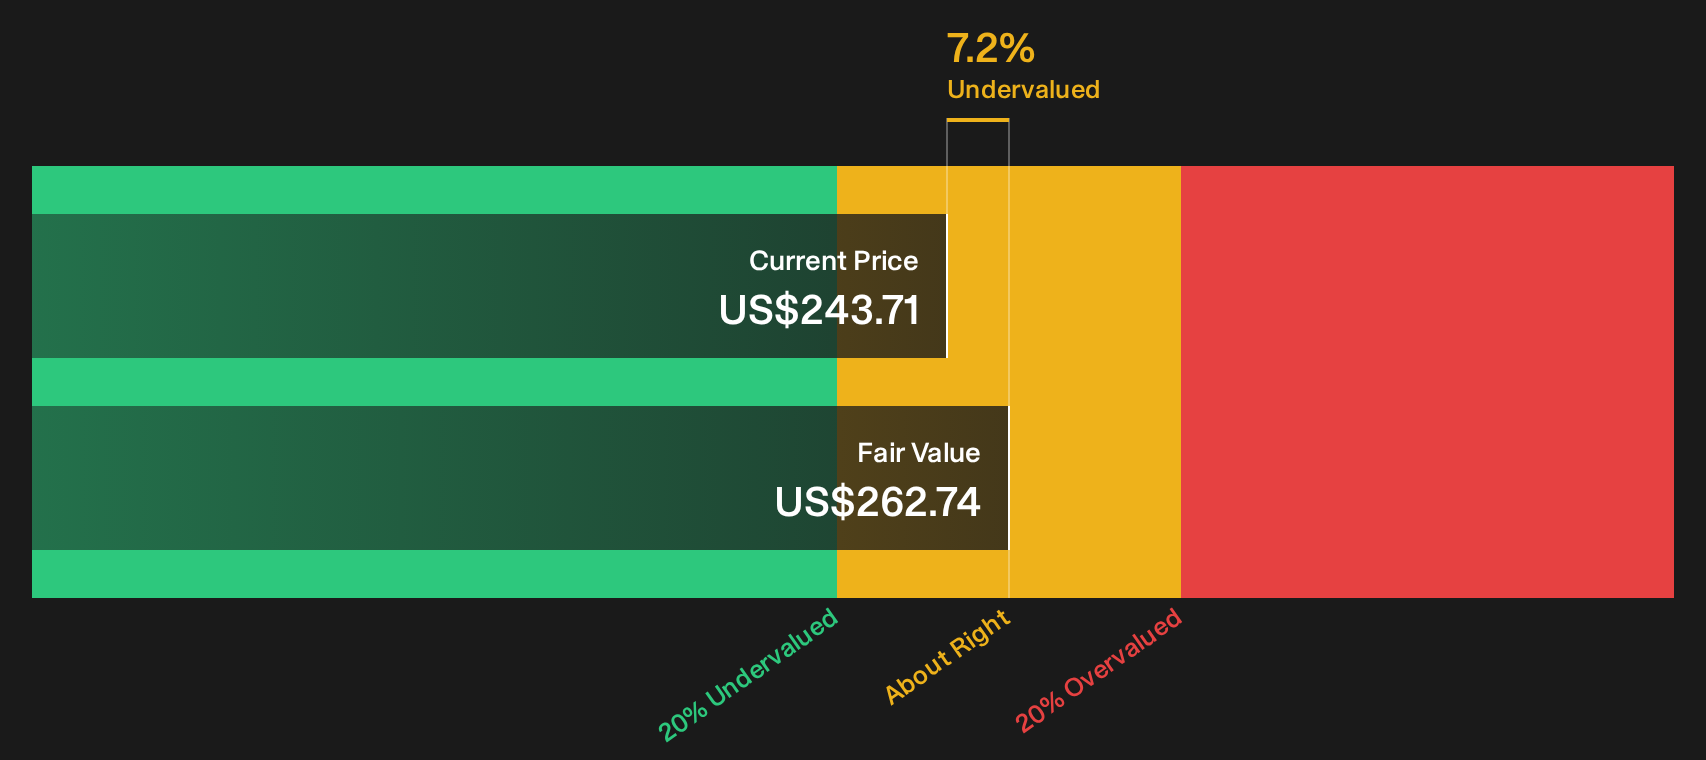
Valuation has shifted against Erie Indemnity over the past year, with a weaker share price record arriving alongside a stock that now trades at a premium P/E of 22.1x compared with its own insurance peers, even as the SWS DCF model points to a modest 7.2% discount to fair value at the latest close of $243.71.
The P/E ratio compares the share price with earnings per share and gives a rough sense of how much investors are willing to pay for each dollar of current profit. For an insurer support business like Erie Indemnity, that multiple often reflects views on the durability of fee income, the quality of underwriting services and how consistent profitability is through the cycle.
Here the signals pull in different directions. On one side, Erie Indemnity has high quality earnings and a strong 23.4% return on equity, with earnings having grown 18.3% per year over the past 5 years. On the other side, the latest year brought a decline of 7.7% in earnings and net profit margins eased from 15.7% to 14%, while the stock underperformed both the broader US market, which returned 10.7%, and the US Insurance industry, which returned 9.2%, over the same 1 year period.
Compared with the sector, the current P/E of 22.1x is expensive against the US Insurance industry average of 11x and also richer than the narrower peer average of 12.7x. That kind of valuation gap suggests investors are paying a clear premium for Erie Indemnity's fee based model, high return on equity and seasoned management and board, even though recent earnings and share price performance have lagged industry trends.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 22.1x (OVERVALUED).
Still, the story for Erie Indemnity can change quickly if subscriber growth at the Erie Insurance Exchange slows or if fee revenues come under pressure from competition or regulation.
Find out about the key risks to this Erie Indemnity narrative.
Another view on Erie Indemnity's value
The P/E screen presents Erie Indemnity as expensive, yet the SWS DCF model offers a different perspective. On that cash flow view, the stock trades at $243.71, around 7.2% below an estimated fair value of $262.74. This frames the recent pullback as a potential mispricing rather than pure over enthusiasm.
That kind of gap can close in either direction. Price can move up toward the DCF estimate, or the fair value mark can be revised down if future cash flow assumptions change. Which outcome do you consider more realistic for Erie Indemnity right now?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Erie Indemnity for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Erie Indemnity is mixed right now, which makes this a good moment to move fast and check the numbers yourself before views harden. To understand why some investors still see upside potential, take a closer look at the 2 key rewards.
Looking for more investment ideas beyond Erie Indemnity?
Do not stop your research with Erie Indemnity. Broaden your watchlist with fresh ideas that match your risk appetite and income goals using the Simply Wall Street Screener.
- Target reliable cash generators by checking companies that appear in our 33 high quality undervalued stocks for a blend of quality fundamentals and attractive pricing.
- Boost potential income by scanning for high-yield opportunities through the 8 dividend fortresses and see which payouts look better supported by current financials.
- Dial down portfolio stress and focus on resilience by reviewing the 32 resilient stocks with low risk scores before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com