


Carrier Global (CARR) has drawn fresh attention after its board declared a quarterly dividend of $0.24 per share, and the firm is also weighing a potential $433 million advanced manufacturing facility in either Texas or Alabama.
Investor attention around Carrier Global has picked up as these expansion plans land against a mixed share price backdrop, with a 30 day share price return of 2.08% but a 90 day share price decline of 17.53%. The 3 year total shareholder return of 18.12% points to longer term momentum that has cooled in recent months.
Scan beyond Carrier Global and compare it with a hand picked list of solid balance sheet and fundamentals (25 results) that could also be gearing up for their next expansion phase.
Carrier Global now trades at a clear gap to both analyst targets and intrinsic value estimates. Is the recent pullback a fair reset, or is the market mispricing the expansion story already in motion?
Most Popular Narrative: 27% Undervalued
The most followed narrative currently places Carrier Global’s fair value near $75.78, compared with a last close of $55.00. This frames the recent share price reset as a sizeable discount rather than a minor wobble.
Carrier Global is building a larger presence in AI and data center cooling, with about $2 billion of 2026 data center revenue already in backlog, an over $8 billion company backlog that is heavily tied to commercial and data center projects, and a dedicated U.S. manufacturing site planned to roughly double Americas data center capacity, which can support future revenue and earnings.
See why 30 investors see Carrier Global as 27% undervalued.
Result: Fair Value of $75.78 (UNDERVALUED)
Still, two pressure points hang over the Carrier Global story: uneven performance across regions and products, and ongoing cost and tariff headwinds that could squeeze margins.
Find out about the key risks to this Carrier Global narrative.
Another View: Carrier Global On Earnings Multiples
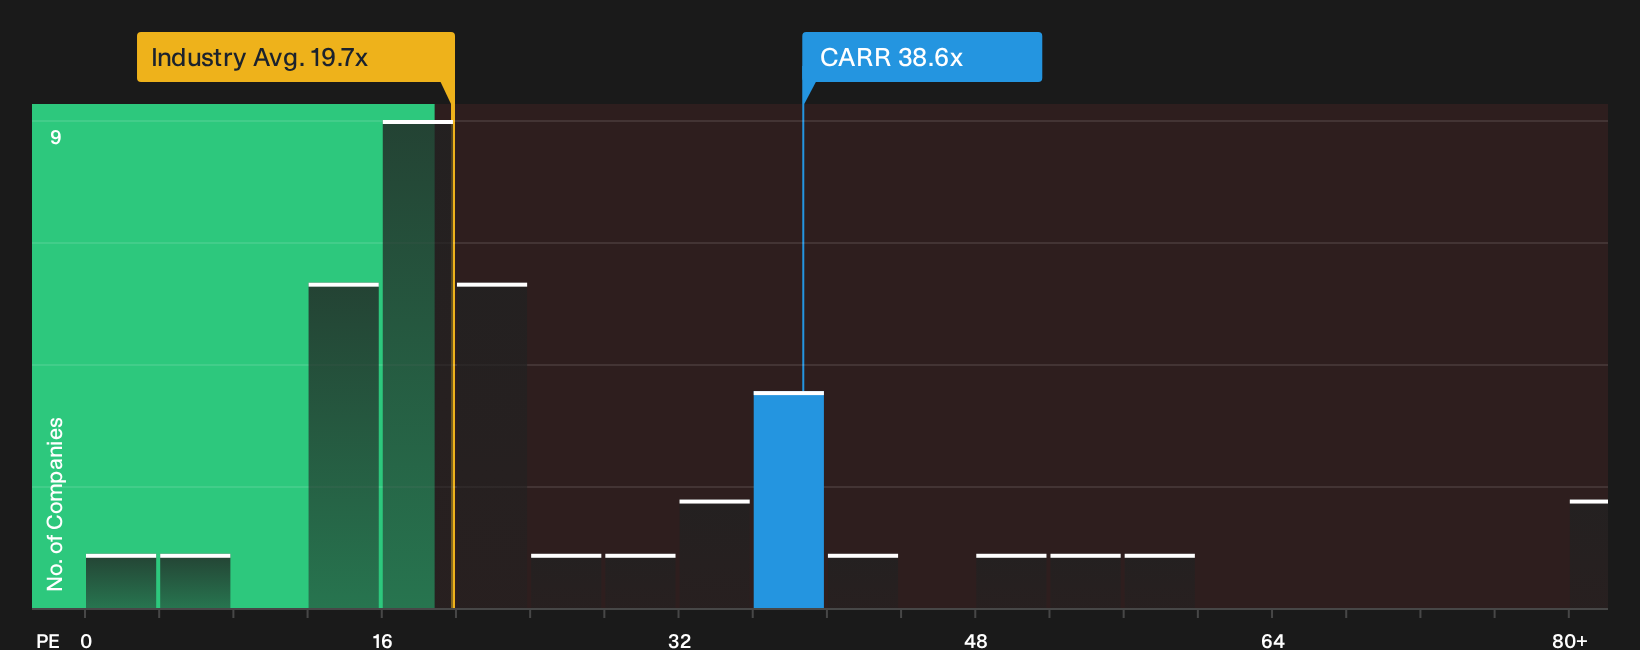
There is a catch. While the SWS model points to Carrier Global trading below fair value, the current P/E of 38.6x is well above both the US Building industry at 19.7x and peers at 28.1x, and exceeds a fair ratio of 33.1x, which raises the question of how much valuation risk investors are really taking on.
For readers weighing that trade off between discounted cash flow upside and a rich earnings multiple, it can help to see how those P/E gaps have opened up and what might close them over time, as outlined in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Carrier Global do not need to leave you on the fence, especially when you can review both sides of the story in minutes. Take a closer look at the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Carrier Global?
If Carrier Global has your attention, do not stop there. Broaden your watchlist with a few focused idea lists that can surface fresh opportunities fast.
- Target resilient balance sheets by reviewing a curated 32 resilient stocks with low risk scores. This approach aims to keep downside risk in check while you hunt for upside.
- Hunt for mispriced quality through a focused 33 high quality undervalued stocks that filters for strong fundamentals at prices that may not fully reflect them yet.
- Spot potential early-stage opportunities by scanning a tightly selected 14 elite penny stocks with strong financials that pairs smaller market caps with stronger financial profiles than the typical microcap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com