


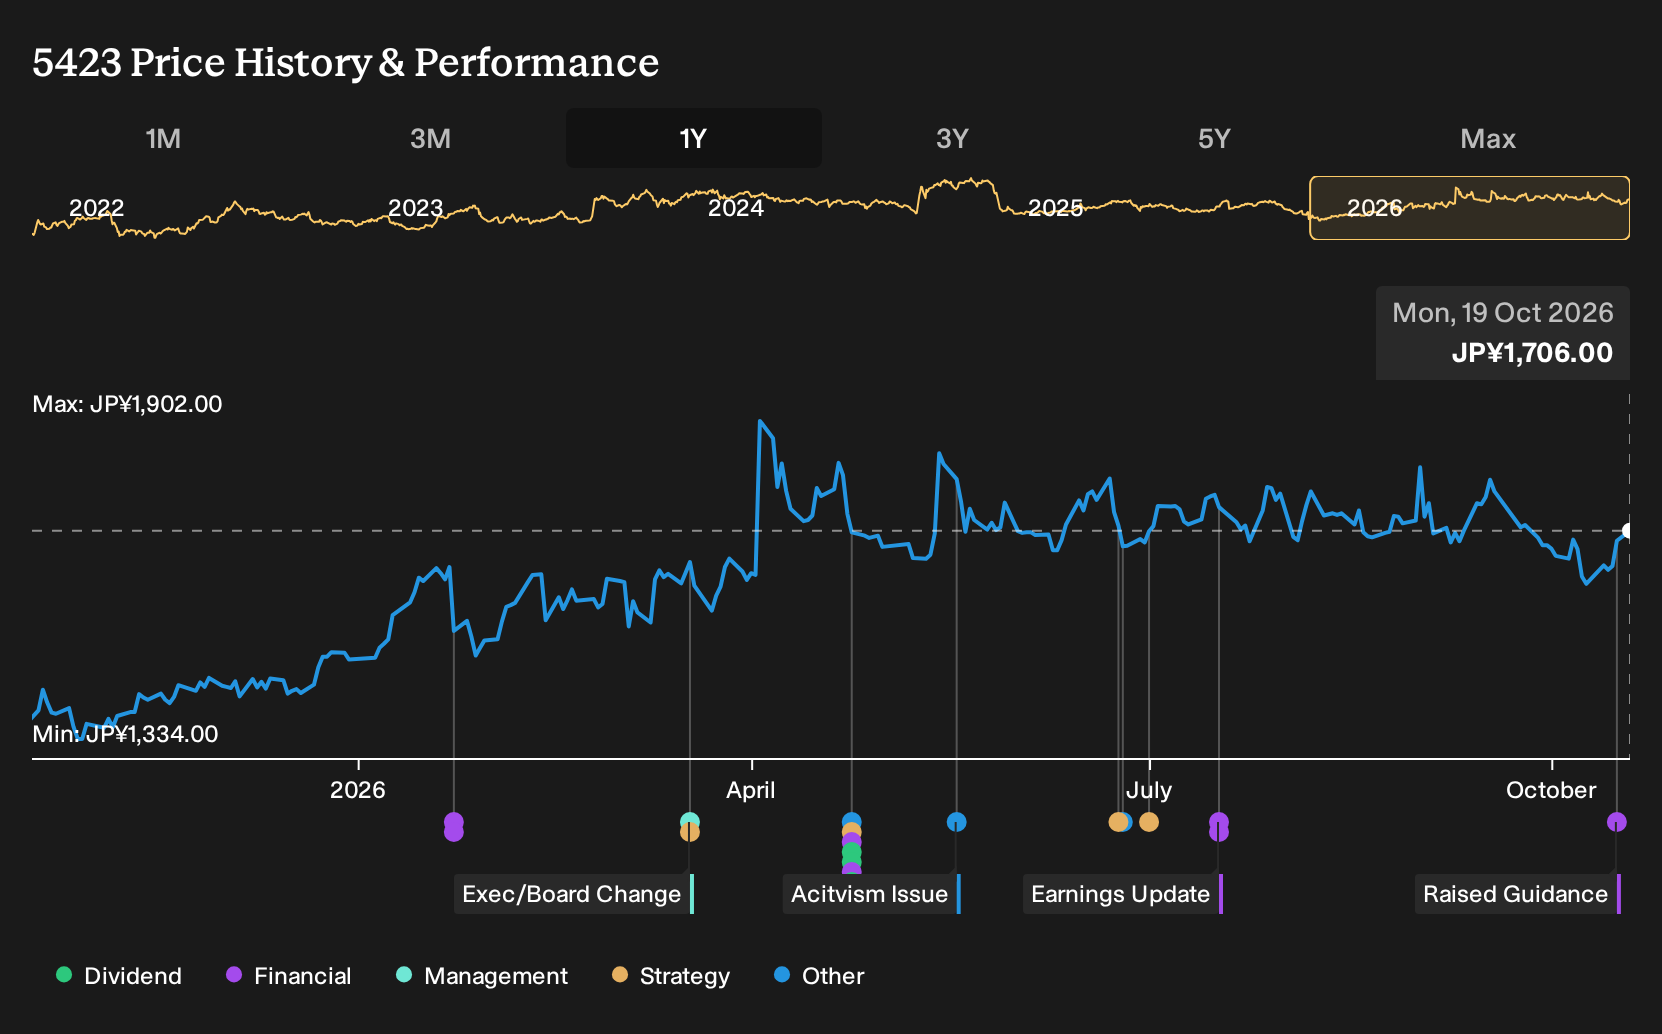
- Tokyo Steel Manufacturing revised guidance for the six months to September 30, 2026 and the year to March 31, 2027, trimming sales and operating profit forecasts while materially lifting profit and basic EPS projections, helped by asset sales and lower than expected steel scrap costs.
- The updated outlook leans heavily on one off asset disposals and input cost relief rather than core operations, which puts more weight on how repeatable these earnings drivers really are for Tokyo Steel Manufacturing.
- Next, the focus shifts to how Tokyo Steel Manufacturing's investment narrative absorbs earnings now tied to asset sales and cheaper raw materials.
What Is Tokyo Steel Manufacturing's Investment Narrative?
To own Tokyo Steel Manufacturing, you need to be comfortable with a very cyclical, capital hungry steel maker where pricing power, mill utilization and scrap costs do most of the heavy lifting. The revised guidance reinforces that reality. Short term earnings now lean on cheaper steel scrap and asset sales, while core operations are guided to only modest operating profit for the full year. That mix matters for a business already showing thinner net margins than last year and low Return on Equity.
In the near term, the key swing factors look clear. Shipment prices and domestic demand need to hold up as recent price revisions flow through, and management has to keep squeezing costs in a market where earnings are forecast to decline on average over the next 3 years. At the same time, the stock trades on a P/E above both industry and peer averages, and free cash flow coverage of the dividend is flagged as weak, so this guidance reset makes the quality and repeatability of Tokyo Steel Manufacturing's current profit profile a very live question.
Even so, sitting behind this guidance upgrade and the recent share price gains is a less comfortable issue that starts with how reliant...
There's only one way to know the right time to buy, sell or hold Tokyo Steel Manufacturing. Head to Simply Wall St's company report for the latest analysis of Tokyo Steel Manufacturing's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tokyo Steel Manufacturing research is our analysis highlighting 4 important warning signs that could impact your investment decision.
- See our latest analysis for Tokyo Steel Manufacturing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tokyo Steel Manufacturing's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tokyo Steel Manufacturing?
If this earnings reset has you rethinking your watchlist, it can help to line Tokyo Steel Manufacturing up against other businesses with different strengths. The Simply Wall St Screener lets you filter for the traits you care about most so you are not relying on a single storyline.
- If you care most about valuation support and fundamentals, start with a focused set of 13 high quality undervalued stocks that pair cash generation with balance sheets that do not look stretched.
- If income reliability matters to you, scan a curated pool of 29 dividend fortresses where yield and balance sheet strength sit side by side.
- If capital preservation is higher up your list, work through a pre-filtered group of 22 resilient stocks with low risk scores that screen well on resilience and financial risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com