


Huntsman (HUN) has drawn fresh attention after posting annual revenue of US$5.9b and a net loss of US$168m. Those headline figures help frame how investors might think about the chemicals group’s recent share performance.
Recent trading reflects that mix of pressure and resilience. Huntsman shares closed at US$8.58, with a 7-day share price return of 6.32% after a period in which the 90-day share price return declined 31.96%. The 1-year total shareholder return is 8.77%, despite a 5-year total shareholder return that is down 67.95%.
Scan 33 high quality undervalued stocks hand picked for resilient financials if Huntsman’s recent swings have you considering other materials players with a potentially stronger mix of quality and value.
Huntsman now trades at a discount to analyst targets after a sharp 90 day pullback. Is that caution simply tracking the recent loss, or does the gap hint at mispricing?
Most Popular Narrative: 21% Undervalued
The most followed narrative pegs Huntsman’s fair value at $10.85, above the recent $8.58 close, which frames a potential discount that investors are trying to explain.
The company is actively transforming its portfolio away from lower-margin, commodity chemicals toward specialty chemicals (e.g., adhesives, elastomers, aerospace composites). It is aiming to further improve EBITDA margins and overall profitability in future cycles. Cost optimization, working capital discipline, and strategic asset closures (e.g., the maleic anhydride facility in Europe) are expected to enhance free cash flow generation and support improved net margins and earnings resilience during the next macro upturn.
See why 13 investors see Huntsman as 21% undervalued.
Result: Fair Value of $10.85 (UNDERVALUED)
Still, the narrative comes under pressure if weak construction demand and soft European volumes persist, or if high regional energy costs keep Huntsman margins under strain.
Find out about the key risks to this Huntsman narrative.
Another View On Huntsman’s Valuation
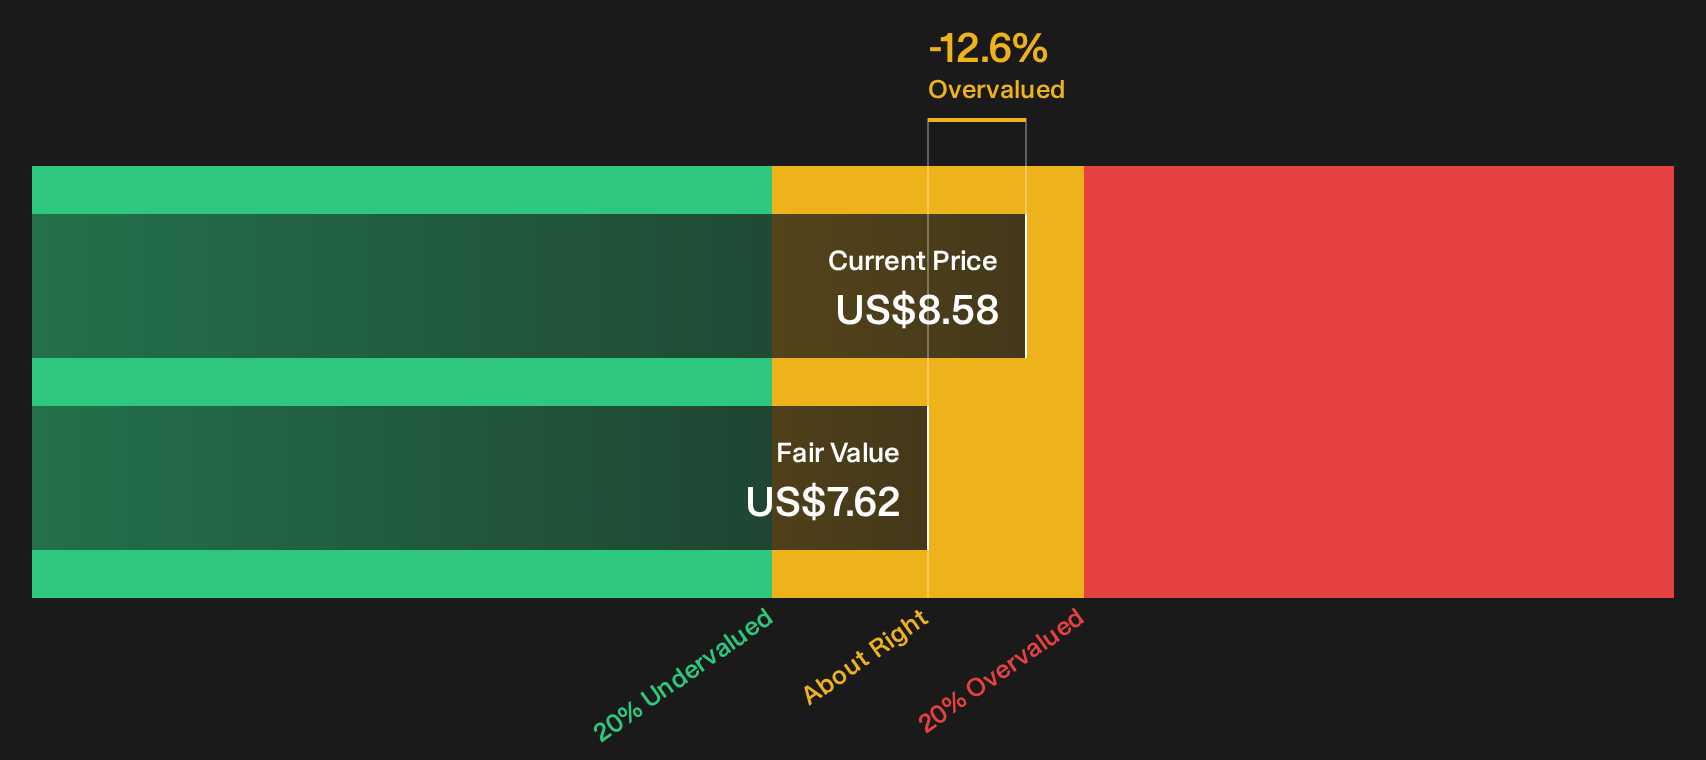
The popular narrative tags Huntsman as undervalued against a US$10.85 fair value, yet our DCF model points in the opposite direction. On a future cash flow basis, Huntsman at US$8.58 screens as expensive relative to an estimated value of about US$7.62. So which story do you trust more?
To see how that cash flow view is built, and where the key assumptions sit, take a closer look at the SWS DCF model for Huntsman, including the full step by step calculation in context of its current share price. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Huntsman for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Huntsman is clearly split. This is exactly why it helps to move fast, review the full risk and reward picture, and shape your own view with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Huntsman?
If Huntsman has you thinking harder about valuation and risk, broaden your watchlist now with a few focused idea sets that target very different opportunities.
- Target income first and prioritize dependable cash returns by scanning a curated pool of potential 8 dividend fortresses.
- Prioritize resilience under pressure and seek businesses built on stronger finances through our carefully filtered list of solid balance sheet and fundamentals (25 results).
- Hunt for tomorrow’s potential standouts early by reviewing a tightly screened group of 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com