


- Merit Medical Systems initiated a voluntary Class II recall of Embosphere microsphere syringes produced in specific lots after packaging holes were found that may compromise sterility. The recall covers 104 units distributed across the US and several international markets.
- This quality issue introduces potential remediation costs and operational focus on packaging integrity. These factors could intersect with Merit Medical Systems' broader efficiency and margin improvement programs.
- We will now examine how Merit Medical Systems' investment narrative could be affected by this Class II Embosphere packaging recall.
Scan beyond Merit Medical Systems and stress test your thesis against 32 resilient stocks with low risk scores, which keep product quality and balance sheet resilience front and center.
Merit Medical Systems Investment Narrative Recap
To own Merit Medical Systems, you need to believe the efficiency program, product platform build out and tuck in deals can keep earnings and cash generation moving in the right direction, despite moderate top line forecasts. The Embosphere recall introduces some near term remediation effort, but given the 104 unit scope it does not look like a major volume or revenue swing factor.
For the next year or so, the key swing item still looks like execution on margin targets while managing tariff costs that are embedded in 2026 guidance. The biggest operational risk remains slower than hoped adoption and reimbursement for WRAPSODY CIE, not this packaging issue.
The Embosphere recall sits next to earlier commentary on multi year efficiency work that lifted non GAAP operating margin to 22.6% in Q2 2026 with a roughly 950 basis point expansion goal versus 2019. Quality fixes and extra checks can absorb resources, so investors will watch whether recall related work shows up in manufacturing costs or slows further progress.
That margin program, together with 7.8% organic growth in Foundational products and 11.7% in Therapeutic products in Q2 2026, remains a core catalyst for the Merit Medical Systems story. If product platforms continue to scale and OEM and international channels contribute as outlined, this recall looks more like a test of operational discipline than a reset to the thesis.
Merit Medical Systems' current analyst narrative points to revenues of US$1.9b and earnings of US$226.5 million by 2029, based on a forecast revenue growth rate of 6.3% a year and an increase in earnings of about US$80.9 million from US$145.6 million today.
Discover why Merit Medical Systems' fair value indicates a 14% potential upside to its current price that may not last much longer.
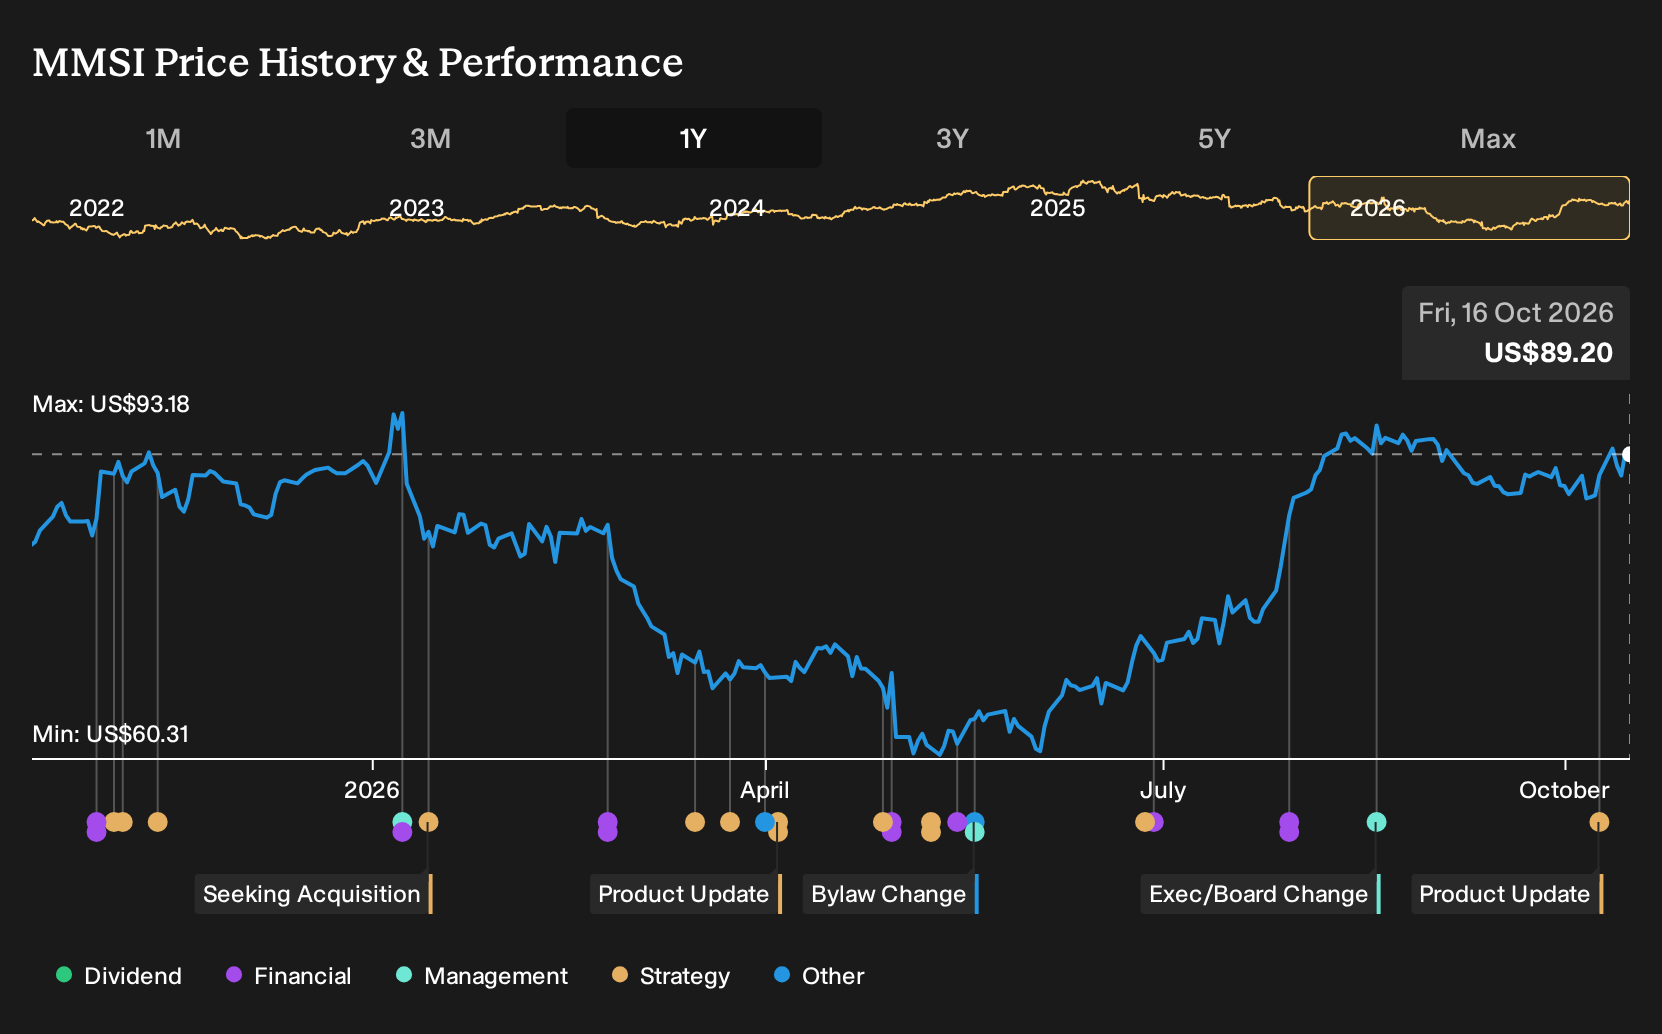
Exploring Other Perspectives
Some of the most optimistic analysts focus less on recalls and more on Merit Medical Systems’ push into higher margin oncology and endoscopy platforms. Before this packaging issue, that bullish group was modeling roughly US$1.9b of revenue and US$238.9 million of earnings by 2029. You should expect those views could shift as quality events evolve.
Explore 2 other Merit Medical Systems fair value estimates, including one that suggests a potential 20% increase from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Merit Medical Systems research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Merit Medical Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Merit Medical Systems' overall financial health at a glance.
Looking For More Ideas Beyond Merit Medical Systems?
If you want to stress test your thinking on Merit Medical Systems against other opportunities, a quick pass through a few targeted screeners can surface companies that may better match your risk tolerance and income or value goals.
- For investors focused on capital preservation and steadier profiles, review a curated group of resilient stocks in the 32 resilient stocks with low risk scores to compare how their risk characteristics stack up against Merit Medical Systems.
- If value is your priority and you are hunting for mispriced quality, scan the 33 high quality undervalued stocks and see which companies combine robust fundamentals with more conservative valuations.
- Income driven readers who care about cash returns can use the 8 dividend fortresses to spot businesses offering higher yields while still keeping an eye on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com