


Truist’s decision to lift third quarter estimates for Pebblebrook Hotel Trust (PEB) after stronger revenue per available room in July and August puts the hotel REIT’s recent operating trends under a brighter spotlight for investors.
At a share price of $19.49, Pebblebrook Hotel Trust has logged a strong year to date, with a 30 day share price return of 8.0% and a 1 year total shareholder return of 80.8%. However, the 90 day share price return is slightly down 1.3%, which suggests momentum has been strong over the past year but has cooled a little in recent months.
Spot opportunities similar to Pebblebrook Hotel Trust’s recent momentum by scanning a curated list of hotel and real estate peers through 33 high quality undervalued stocks.Pebblebrook Hotel Trust has already delivered a powerful rebound, yet the recent stretch of softer 90 day returns raises a fresh question. After this sharp move, does the current valuation still leave meaningful upside on the table, or has most of it already played out?
Most Popular Narrative: 5.8% Overvalued
The most followed narrative pegs Pebblebrook Hotel Trust’s fair value at $18.42, slightly below the recent $19.49 close, which frames Truist’s estimate lift against a richer starting point.
The portfolio is set to benefit from a loaded pipeline of major citywide events, convention calendars, and sports/entertainment spectacles (World Cup, Super Bowl, Olympics) in 2026 to 2028, which are expected to significantly boost occupancy, push ADR higher, and drive revenue growth in core urban markets. Proactive risk management, strong balance sheet positioning (low fixed-rate debt and high cash/reserves), and continued focus on asset recycling and CapEx discipline enhance FFO visibility and enable the company to capitalize on sector consolidation trends, supporting resilient long-term earnings growth.
See why 1 investors see Pebblebrook Hotel Trust as 6% overvalued.
Result: Fair Value of $18.42 (OVERVALUED)
Still, heavy exposure to large coastal cities, along with the risk of higher labor costs or wage legislation, could pressure Pebblebrook Hotel Trust’s margins and test this upbeat narrative.
Find out about the key risks to this Pebblebrook Hotel Trust narrative.
Another View: What P/S Says About Pebblebrook Hotel Trust
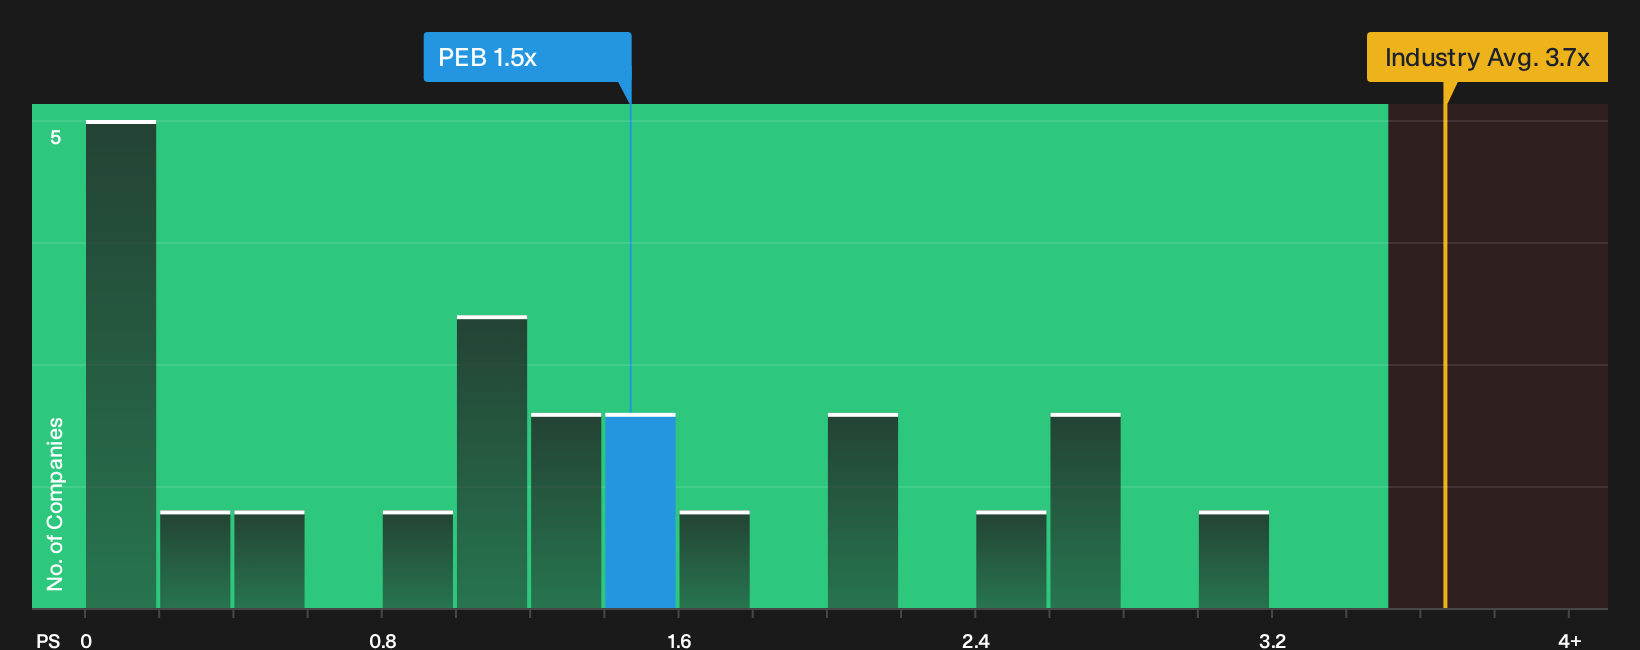
The headline community narrative flags Pebblebrook Hotel Trust as 5.8% overvalued at $19.49, yet the pricing picture looks different when you focus on sales. On a P/S of 1.5x versus a fair ratio of 1.9x and a global Hotel and Resort REITs average of 3.7x, the stock appears inexpensive relative to both its own fundamentals and sector peers. If the market edges closer to that fair ratio over time, are analysts underestimating how much room is left in this move?
See what the numbers indicate about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Pebblebrook Hotel Trust is mixed, with solid recent returns on one hand and questions on valuation and risk on the other. Consider acting promptly, reviewing the underlying metrics, and weighing both sides of the story by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Pebblebrook Hotel Trust?
Do not stop with Pebblebrook Hotel Trust. Take a few minutes to scan fresh opportunities so you are not watching better setups pass by on the sidelines.
- Target potential mispricings by running a focused search across 33 high quality undervalued stocks that combine quality fundamentals with discounted valuations.
- Strengthen portfolio resilience by filtering for businesses with cleaner finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for under-the-radar opportunities before they become crowded trades through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com