


Kingsoft Cloud Holdings (NasdaqGS:KC) just received an ESG ratings upgrade to the top tier AAA from MSCI, its third step up since 2022. This puts the company’s sustainability efforts directly in focus for investors.
Recent trading has told a different story to the ESG headlines. Kingsoft Cloud Holdings’ share price has fallen 14.6% over the past month and is down 22.5% year to date. The 3 year total shareholder return is strongly positive, but the 1 year total shareholder return is down 34.4%. This suggests earlier momentum has cooled even as investors reassess the business after the AAA rating news.
See how Kingsoft Cloud Holdings compares with other under-pressure tech names by reviewing our curated list of 33 high quality undervalued stocks.
So investors face a simple tension. Kingsoft Cloud Holdings now carries a top tier ESG badge while the share price has retreated hard. Does that gap still tilt the risk reward in favour of new buyers?
Most Popular Narrative: 58% Undervalued
Against the last close of $8.47, the most followed narrative pegs Kingsoft Cloud Holdings at a fair value of $20.17 using an 11.6% discount rate, which frames the ESG upgrade against a much higher long run earnings and cash flow story.
Ongoing advances in AI and generative AI adoption across multiple sectors are rapidly increasing demand for intelligent computing and scalable cloud services, driving strong revenue growth, evidenced by AI-related gross billings up 120%+ YoY and forming 45% of public cloud revenue, indicating the addressable market and future top-line expansion remain underappreciated.
See why 12 investors see Kingsoft Cloud Holdings as 58% undervalued.
Result: Fair Value of $20.17 (UNDERVALUED)
Still, the Kingsoft Cloud Holdings story can change quickly if high infrastructure and server costs continue to pressure margins or if key ecosystem clients cut back spending.
Find out about the key risks to this Kingsoft Cloud Holdings narrative.
Another View: Kingsoft Cloud Holdings And The Cash Flow Debate
The popular narrative around Kingsoft Cloud Holdings leans on earnings and revenue projections pointing to a fair value of $20.17. A different lens, the SWS DCF model, points in the opposite direction and suggests that at $8.47 the shares trade above an estimated future cash flow value of $5.01, implying the stock screens as overvalued on this measure. That split raises a simple question for you as an investor: which matters more right now, the story in the income statement or the one in the cash flow line?
For readers who want to see how the cash flow assumptions tie together in detail, our SWS DCF workup for Kingsoft Cloud Holdings is a useful cross check on the earnings based narrative. Look into how the SWS DCF model arrives at its fair value.
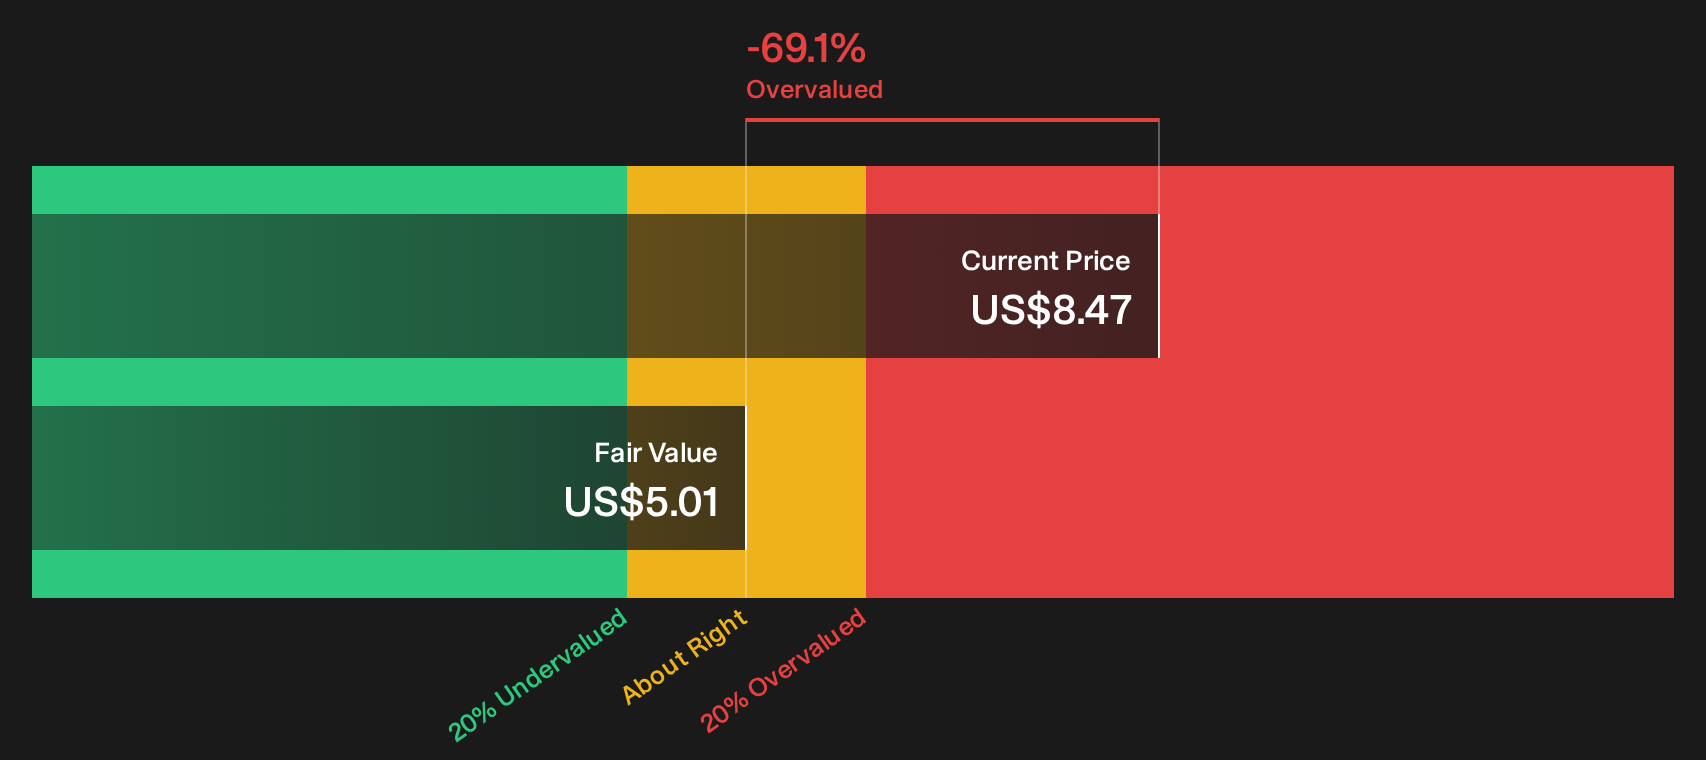
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kingsoft Cloud Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split views on Kingsoft Cloud Holdings leave you undecided, move quickly to look through the full data and pressure test the bullish angles for yourself by reviewing the 3 key rewards.
Looking for more Kingsoft Cloud Holdings investment ideas?
Do not stop at a single stock. Use the Simply Wall Street Screener to quickly surface fresh opportunities that match how you like to invest.
- Target dependable compounding by scanning a curated set of income opportunities through the 8 dividend fortresses.
- Hunt for quality at a discount by reviewing the 20 high quality undiscovered gems that pair strong fundamentals with lower market attention.
- Dial down portfolio stress by focusing on financially resilient businesses via the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com