


National Bank Holdings (NBHC) has drawn fresh attention after recent trading left the share price at US$37.92, with the stock down about 7% over the past month and 17% in the past 3 months.
That recent slide sits against a flatter backdrop for National Bank Holdings, with the year-to-date share price return roughly unchanged. The 1-year total shareholder return of 6.12% and 3-year total shareholder return of 43.12% point to longer term gains despite fading short term momentum.
Scan beyond National Bank Holdings and spot other banks that combine recent share price weakness with stronger long term returns through our hand picked 33 high quality undervalued stocks.
The recent pullback in National Bank Holdings could signal shifting opinion on banks in general, or it could be investors reassessing this specific franchise. Do current valuation markers point more to sentiment than fundamentals?
Most Popular Narrative: 18% Undervalued
National Bank Holdings last traded at $37.92 while the most followed narrative pegs a fair value closer to $46. This frames the recent pullback as a valuation gap rather than a resolved story.
The main thing that has to go right is that National Bank Holdings converts its loan growth, Vista integration, and digital investments like 2UniFi into durable, high quality earnings without eroding its conservative credit profile or near 4% net interest margin.
See why 4 investors see National Bank Holdings as 18% undervalued.
Result: Fair Value of $46 (UNDERVALUED)
Still, the story around National Bank Holdings can break if credit issues emerge in trucking or commercial real estate, or if 2UniFi expenses continue to outweigh early revenue.
Find out about the key risks to this National Bank Holdings narrative.
Another View: National Bank Holdings On Earnings Multiples
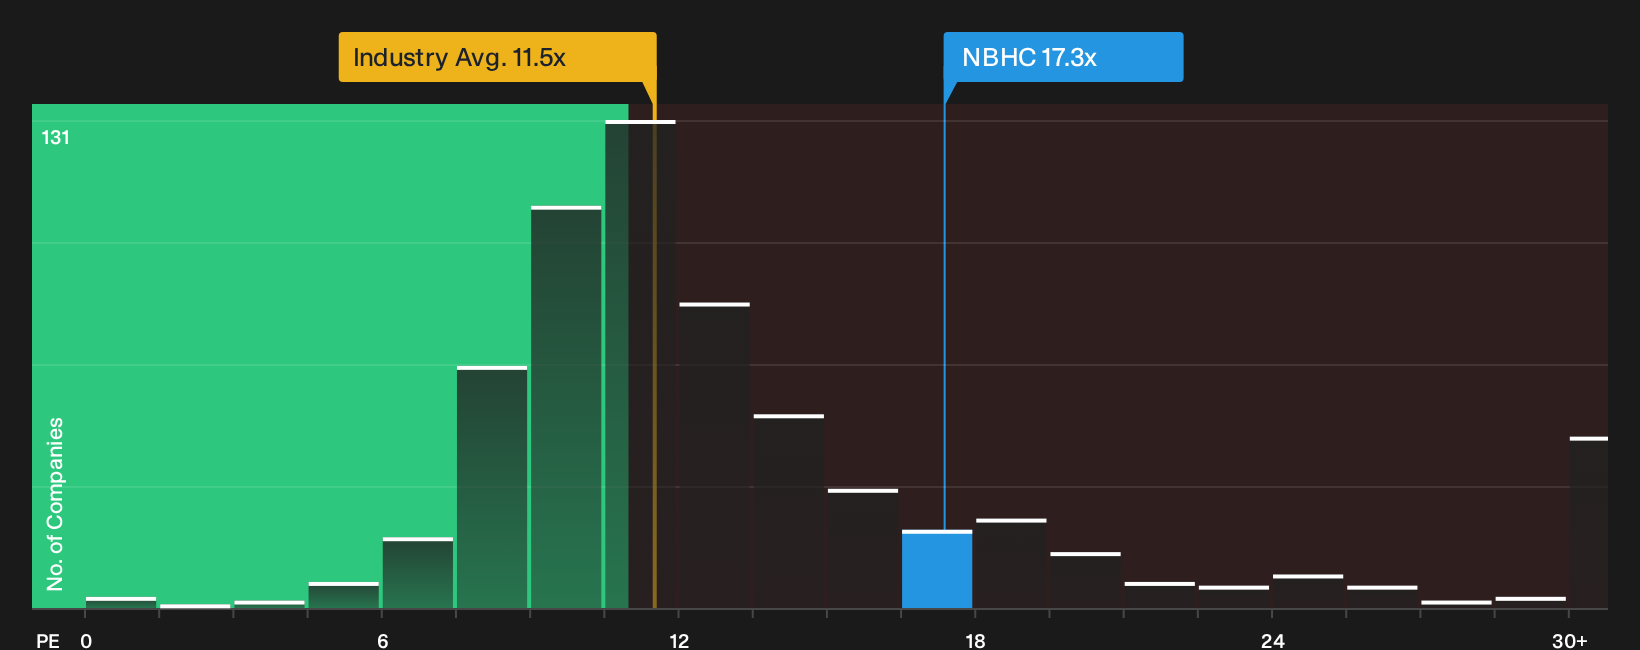
The earlier fair value of $46 for National Bank Holdings comes from a narrative and cash flow style approach. The current P/E of 17.3x is higher than the US Banks industry at 11.5x, the peer average at 12.6x, and the fair ratio of 16.1x, which suggests investors are already paying a richer price for each dollar of earnings. Does that premium feel justified to you, or does it raise questions about how much upside is really left?
For a closer look at how this earnings based check lines up against the story driven fair value and what that gap could mean for risk or opportunity, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around National Bank Holdings can either feel confusing or like a useful stress test for your own thesis, so review the full picture of risks and potential upsides and see how that lines up with your expectations through 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond National Bank Holdings?
If you stop with National Bank Holdings, you risk missing other opportunities that fit your style, so put the Simply Wall St screener to work for you.
- Target income first and scan for companies that aim to combine yield with resilience through our 8 dividend fortresses.
- Hunt for quality at a discount by checking stocks that pair solid fundamentals with appealing pricing using the 33 high quality undervalued stocks.
- Prioritize sleep at night and filter for businesses with sturdier finances and lower risk profiles through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com