


- Northwest Bancshares is scheduled to report its September 2026 quarter results, with analysts expecting year over year earnings and revenue growth based on current estimates.
- The bank's history of outperforming consensus EPS projections and the current gap between the Most Accurate Estimate and consensus have sharpened focus on its execution heading into this report.
- This sets the stage for an examination of how Northwest Bancshares' investment narrative aligns with the anticipated year over year earnings improvement in the upcoming report.
Compare Northwest Bancshares' setup ahead of earnings with a curated group of resilient financials by scanning our 32 resilient stocks with low risk scores that aim to balance upside potential with measured risk.
Northwest Bancshares Investment Narrative Recap
To own Northwest Bancshares, you need to be comfortable with a straightforward banking story. Management is leaning on commercial and industrial lending, new branches in Columbus, and a larger Dublin headquarters to support more loans, deposits, and fee income. The pending September 2026 earnings report mainly tests whether this expansion is translating into healthier day to day performance.
The near term catalyst is clear. Investors are watching whether higher projected revenue and earnings show that margin, credit quality, and expenses remain in check as the footprint grows. The primary risk is that higher operating costs and credit normalization, especially around healthcare and acquired loans, eat into that progress.
The most relevant data point right now is the expectation for improved earnings and revenue in the September 2026 quarter. That update will sit directly against management’s earlier focus on net interest margin protection through repricing CDs, reinvesting securities, and redeeming subordinated debt, along with a stated 2026 margin outlook of 3.73% to 3.75%.
For you as a shareholder, the connection is simple. Stronger quarterly results would help show that actions around C&I expansion, Columbus and Dublin investments, and fee based lines like wealth management and SBA lending are supporting the earnings and revenue path analysts have outlined, without letting higher costs, classified loans, or flat commercial real estate balances dominate the story.
Northwest Bancshares Analyst Setup Through 2029
Northwest Bancshares' long range story now comes with clearer signposts. Analysts have put numbers around the growth plan, giving you a sense of what needs to happen over the next few years for the current thesis to hold up.
The stock analysis work points to an assumed 10.6% annual expansion in revenue, which is the pace the business would need to keep as it leans on nationwide C&I lending, Columbus branches, and the Dublin headquarters buildout. Profit margins are modeled to move from 23.4% today to 28.3% in three years, pairing top line growth with tighter cost control and better mix.
Earnings today sit at US$152.9 million, and the consensus view has that figure reaching US$250.5 million by 2029. That is an increase of roughly US$97.6 million in annual profit that needs to show up through a combination of margin management, credit discipline, and contribution from fee businesses such as wealth management and SBA lending.
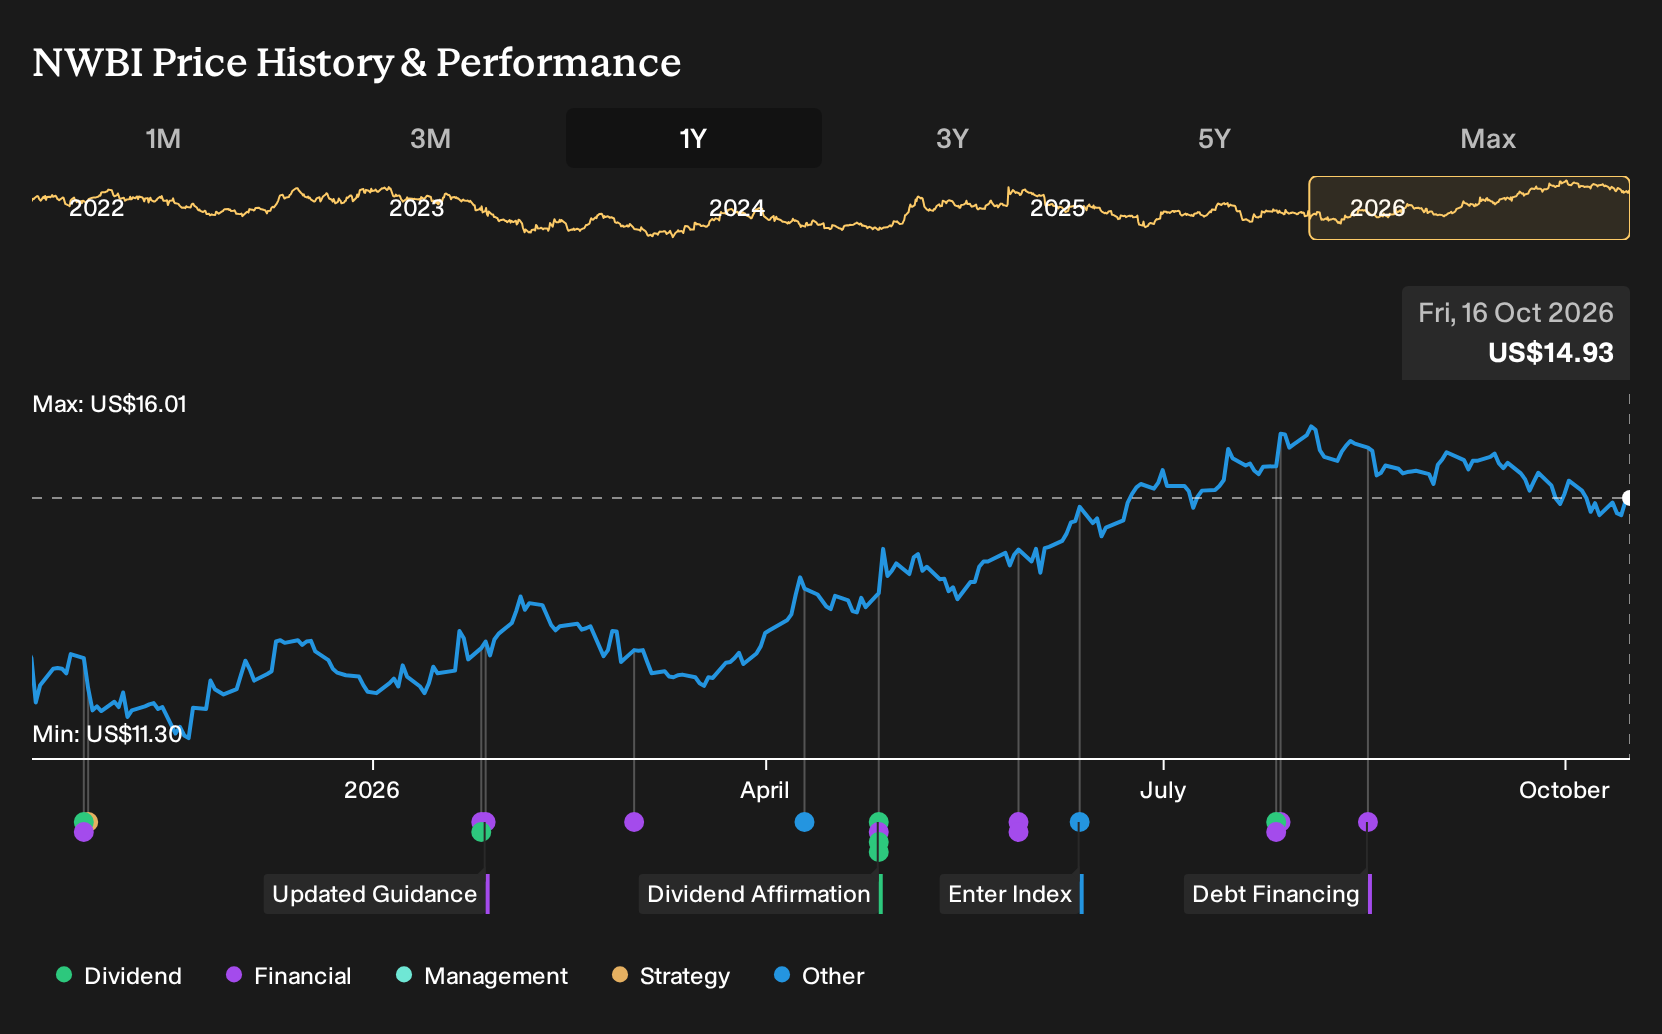
On revenue, the same 2029 framework assumes the bank reaches US$886.0 million. Those levels, together with the earnings projection, underpin analyst use of an 11.8x P/E multiple on 2029 earnings, compared with 14.4x today and 11.5x for the broader US Banks industry. The result is a consensus price target of US$16.29 against a recent share price of US$15.04, with individual targets stretching from US$15.00 to US$18.00.
For you as an investor, the takeaway is practical. The more the upcoming September 2026 earnings line up with this path on revenue growth, profitability, and credit quality, the more comfortable the market is likely to be that the 2029 script remains intact.
Northwest Bancshares' narrative projects US$886.0 million revenue and US$250.5 million earnings by 2029. This rests on 10.6% yearly revenue growth and an earnings increase of about US$97.6 million from US$152.9 million today.
Uncover why Northwest Bancshares' fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$16.29 to US$27.23, which shows how far apart private investors can be on Northwest Bancshares. Compare those opinions with upcoming earnings, where higher expenses or credit issues could matter more than any model, and explore multiple viewpoints before deciding how this story fits your portfolio.
Explore another Northwest Bancshares fair value estimate, including one that suggests as much as 82% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Northwest Bancshares research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Northwest Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northwest Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Northwest Bancshares?
Once you have a view on Northwest Bancshares, it can help to place that opinion in context by comparing it with other companies that match the type of risk, return profile, or income focus you want in your portfolio. The Simply Wall St Screener lets you do that quickly by filtering for factors that matter to you, from balance sheet strength to dividend yield or valuation.
- If capital preservation is a priority, start with sturdier businesses by reviewing a list of solid balance sheet and fundamentals (25 results) that can help anchor your portfolio when conditions get choppy.
- If income is your main goal, focus your research on a 8 dividend fortresses that could offer meaningful yield while you assess the underlying payout quality and consistency.
- If you want to hunt for mispriced opportunities, cast a wider net across a 20 high quality undiscovered gems that pair solid fundamentals with less crowded investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com