


Why Sunstone Hotel Investors Is Back in Focus
Sunstone Hotel Investors (SHO) is back under the spotlight as investors debate whether its current valuation reflects disciplined capital recycling and cash generation or leans too heavily on asset sales and buybacks.
This split in opinion is shaping how the stock is being framed in discussions about long term value creation. For readers, the question is less about headline moves and more about how the underlying playbook actually works.
Recent trading has tilted in Sunstone Hotel Investors' favor, with a 1-month share price return of 8.61% and a year-to-date share price return of 31.33%. The 1-year total shareholder return of 34.19% points to momentum that has built steadily rather than in a single spike.
Scan beyond Sunstone Hotel Investors and compare this playbook with a hand-picked 33 high quality undervalued stocks that also lean on cash generation and disciplined capital allocation.
Sunstone Hotel Investors has already delivered a strong run, yet the share price still trades below both its own intrinsic estimate and the latest analyst target. Is most of the easy upside gone, or is the valuation gap still meaningful?
Most Popular Narrative: 30% Overvalued
Sunstone Hotel Investors last closed at $11.99, slightly above the most followed fair value estimate of $11.96 that is based on an 8.24% discount rate and detailed cash flow assumptions. That small gap hides a much bigger tension between a high implied earnings multiple and a business expected to see revenue edge lower over time.
The analysts have a consensus price target of $11.96 for Sunstone Hotel Investors based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $13.0, and the most bearish reporting a price target of just $10.0.
See why 0 investors see Sunstone Hotel Investors as 0% overvalued.
Result: Fair Value of $11.96 (ABOUT RIGHT)
Still, Sunstone Hotel Investors carries real risk if storms or local disruptions affect concentrated resort markets, or if recycled capital fails to support portfolio earnings.
Find out about the key risks to this Sunstone Hotel Investors narrative.
Another View On Sunstone Hotel Investors' Valuation
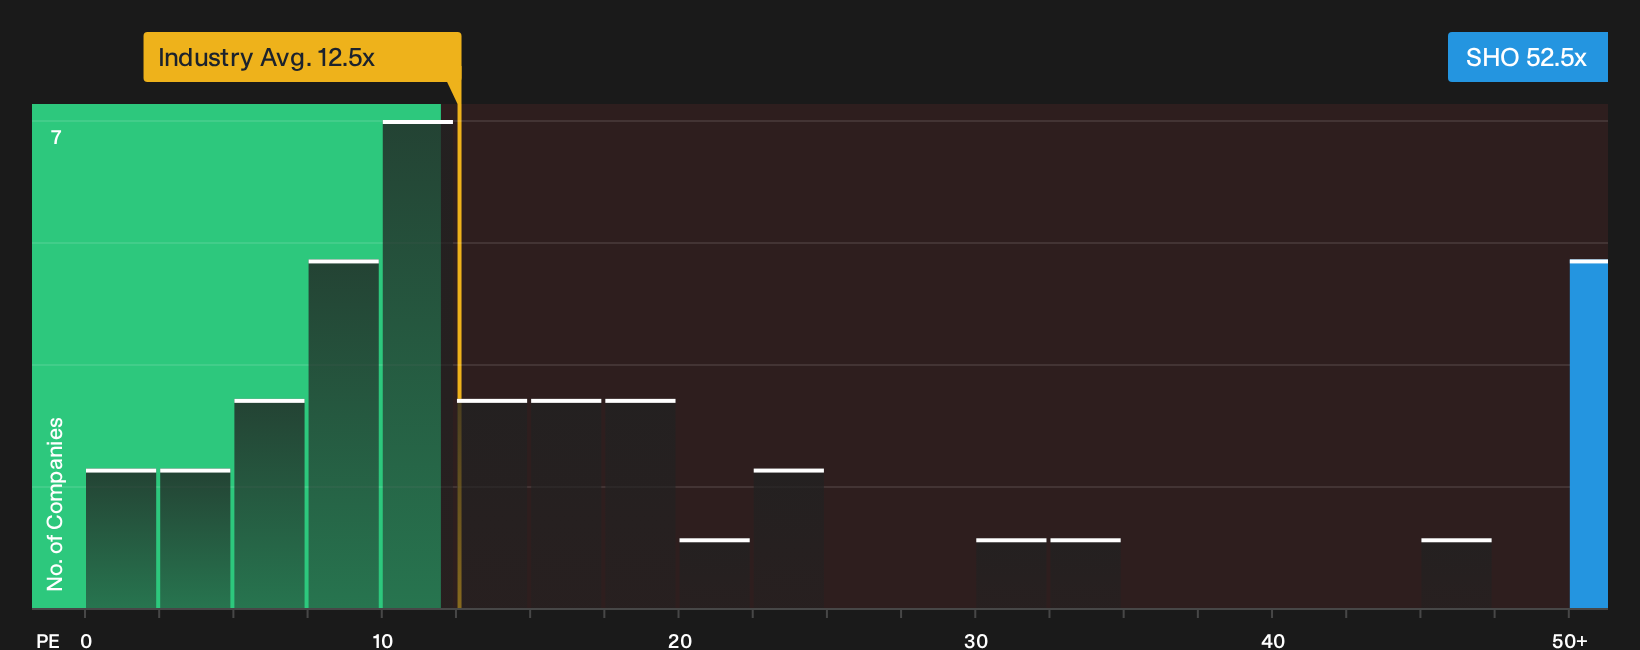
The story so far paints Sunstone Hotel Investors as roughly fairly priced, anchored to a consensus fair value of $11.96. Yet on a simple P/E lens, the stock trades at 52.5x, which is far above the global Hotel and Resort REITs average of 12.5x and also above its own fair ratio of 35.9x. That gap points to meaningful valuation risk if expectations cool or sector multiples compress.
Put differently, the market is already attaching a far richer earnings tag to Sunstone Hotel Investors than to peers, and even richer than the level our fair ratio suggests it could move toward over time. For anyone weighing the recent share price strength, the question becomes whether those premium assumptions feel like a cushion or a tightrope.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Sunstone Hotel Investors' story so far. If that leaves you on the fence, move quickly to inspect both the risks and the upside by checking the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Sunstone Hotel Investors?
If Sunstone Hotel Investors has you thinking harder about price versus quality, you can use that same lens to hunt for other opportunities before the market gets there first.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that filters for companies with financial strength and room to execute through different cycles.
- Spot potential value gaps by reviewing a curated 20 high quality undiscovered gems that surfaces quality businesses the broader market may not be focused on yet.
- Prioritise sleep-at-night holdings by checking a 32 resilient stocks with low risk scores that screens for companies with lower risk scores and more stable profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com