


- Frasers Property announced that Mr. Mirpuri, a global industrial and logistics real estate leader with over 23 years of experience across Asia and the USA, will join its Executive Leadership Team in Singapore from January 11, 2027, reporting to Group CEO Panote Sirivadhanabhakdi.
- His background in cross-border fund management, institutional capital partnerships and building large-scale logistics platforms across key Asian markets indicates a stronger focus on industrial and logistics capabilities within Frasers Property’s broader real estate portfolio.
- We will now look at how Frasers Property’s investment narrative could evolve as this logistics focused executive appointment comes into view.
Scan how Frasers Property’s logistics pivot compares with other real estate plays by reviewing our hand picked 196 high quality undervalued stocks that combine discounted prices with solid fundamentals.
What Is Frasers Property's Investment Narrative?
To own Frasers Property, you need to believe in a global, asset heavy real estate platform that can keep sweat equity high on a S$39.7b portfolio while juggling capital needs and interest costs. The short term story is still about execution across industrial and logistics, hospitality and residential, plus how well S$3,320.7m of revenue and S$172.2m of net income convert into cash to cover a 5% dividend that is not well supported by earnings. The Mirpuri hire points to an emphasis on industrial and logistics capabilities, but this is more about medium term positioning than an immediate operational catalyst.
The more immediate pressure points are simpler. The share price is down about 20% year to date, returns over 1 and 5 years lag both the Singapore market and local real estate peers, and interest payments are not well covered by earnings. This keeps funding risk front of mind in a capital intensive sector. Forecast revenue growth of 9.9% a year and modest earnings growth of 3.74% are helpful, and some models see a large gap between the S$0.90 price and estimated fair value. However, Frasers Property also trades on a P/E above the industry average, which indicates that the market is already being asked to pay up for that story.
Even so, there is a structural issue on the balance sheet that could sharply change how comfortable you feel about that valuation gap once ...
There's only one way to know the right time to buy, sell or hold Frasers Property. Head to Simply Wall St's company report for the latest analysis of Frasers Property's Fair Value.
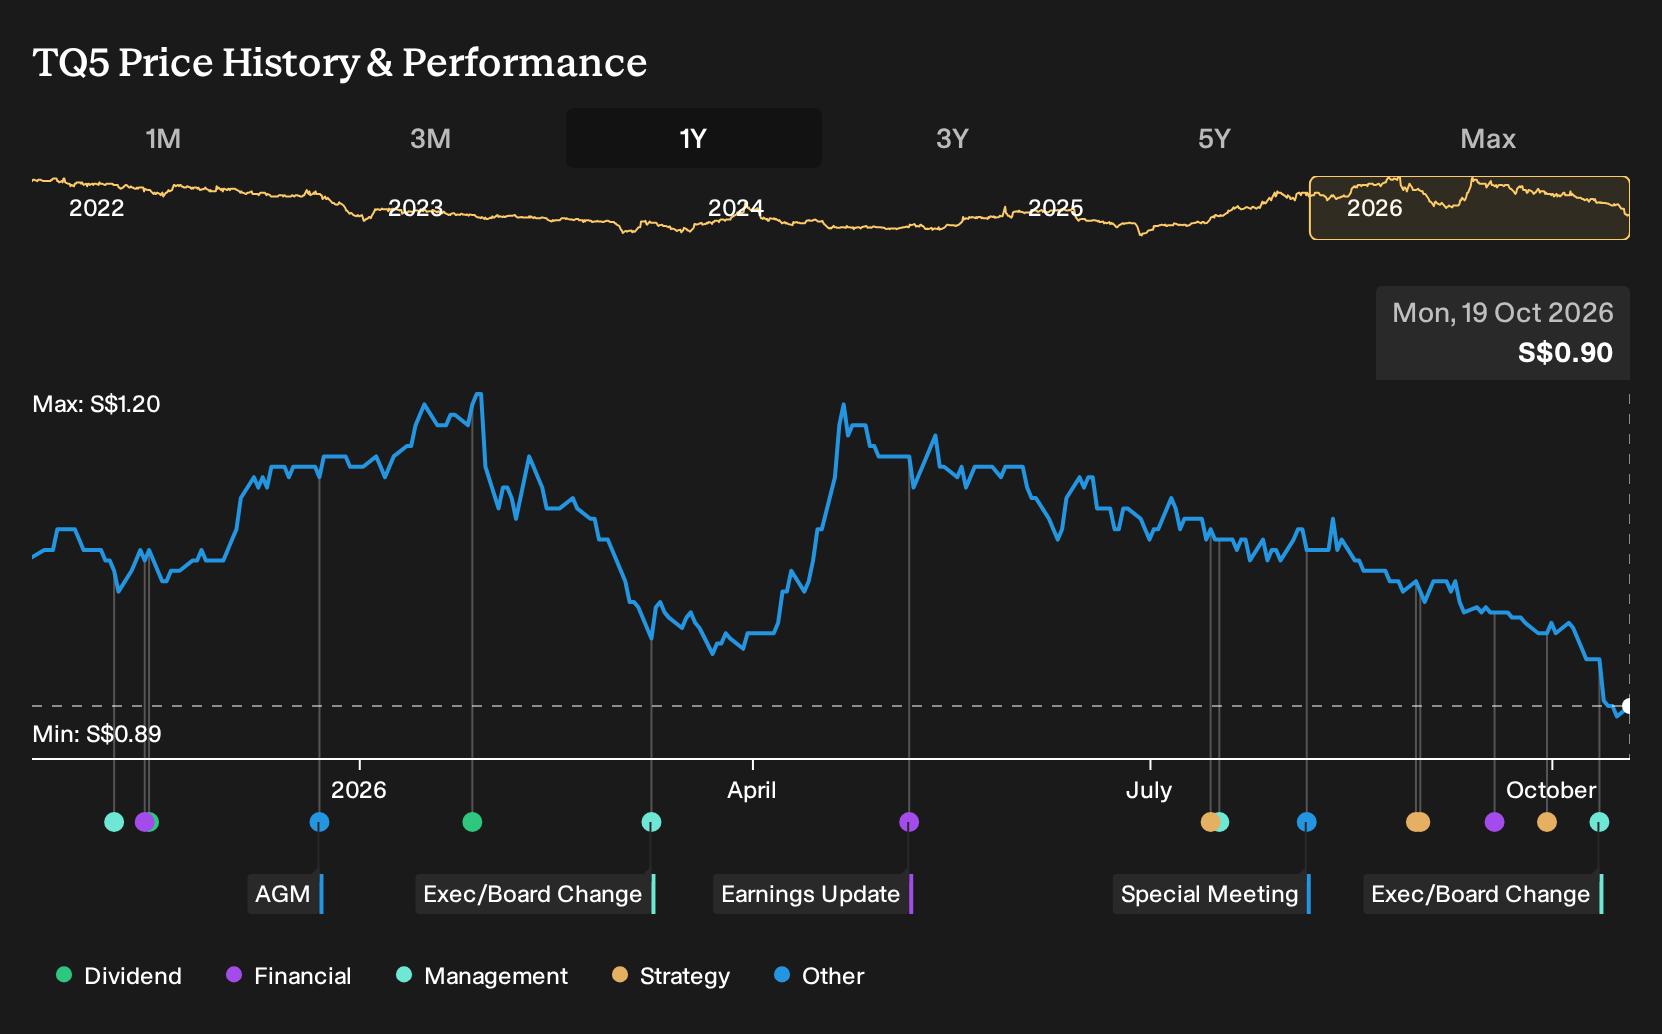
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between S$1.46 and S$2.73, which is a wide span for Frasers Property. That spread shows how far opinions can diverge. With Mr. Mirpuri’s logistics expertise yet to be reflected in these numbers, you are seeing only part of the story.
Explore another Frasers Property fair value estimate, including one that suggests potential upside of up to 204% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Frasers Property research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Frasers Property. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Frasers Property's overall financial health at a glance.
Looking For More Ideas Beyond Frasers Property?
If the Frasers Property story has sharpened your thinking about risk, income and valuation, it can be useful to compare it with other opportunities that match different objectives or risk levels.
- For investors who want strong balance sheets and resilient fundamentals, start with a list of solid balance sheet and fundamentals (203 results) that can help you focus on financially robust businesses first.
- If you are hunting for opportunities that the market may be overlooking, scan a 613 high quality undiscovered gems and see which companies combine quality metrics with relatively muted attention.
- When capital preservation matters most, narrow your search to a 231 resilient stocks with low risk scores and focus on stocks that score well on stability and downside risk measures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com