


Seagate Technology Holdings (STX) is back in focus after investors reacted to fresh interest in high-capacity storage tied to AI infrastructure ahead of the company’s upcoming quarterly earnings release.
That enthusiasm comes after a sharp reset in Seagate Technology Holdings’ share price, with the stock down 23.05% on a 30-day share price return and 25.90% over 90 days, even though the year-to-date share price return is 129.81% and the one-year total shareholder return is 210.03%.
Scan Seagate Technology Holdings’ peers that are also plugged into the AI infrastructure build out by running your eye over 55 AI infrastructure stocks.
After a 23.05% slide over 30 days, Seagate Technology Holdings now trades at a 58.46% discount to an intrinsic estimate and 68.57% below analyst targets. Is that caution grounded, or has sentiment swung too far?
Most Popular Narrative: 43% Undervalued
Against a last close of $660.81, the leading narrative on Seagate Technology Holdings frames a fair value of $1,158.73 and leans heavily on nearline storage scarcity and HAMR-driven cost advantages.
The arithmetic of that shows up in the supply gap. Nearline HDD supply is expected to fall roughly 300 exabytes short of demand in 2026, a 10 to 15% shortfall, widening to something like 400 exabytes in both 2027 and 2028. Blended nearline pricing has been running near $14.30 to $14.90 per terabyte against scenarios that put it meaningfully higher over the next two years.
See why 10 investors see Seagate Technology Holdings as 43% undervalued.
Result: Fair Value of $1,158.73 (UNDERVALUED)
Still, the Seagate Technology Holdings story can crack if Western Digital closes the HAMR gap faster than expected or if hyperscaler AI capex slows materially.
Find out about the key risks to this Seagate Technology Holdings narrative.
Another View: What Seagate’s P/E Is Telling You
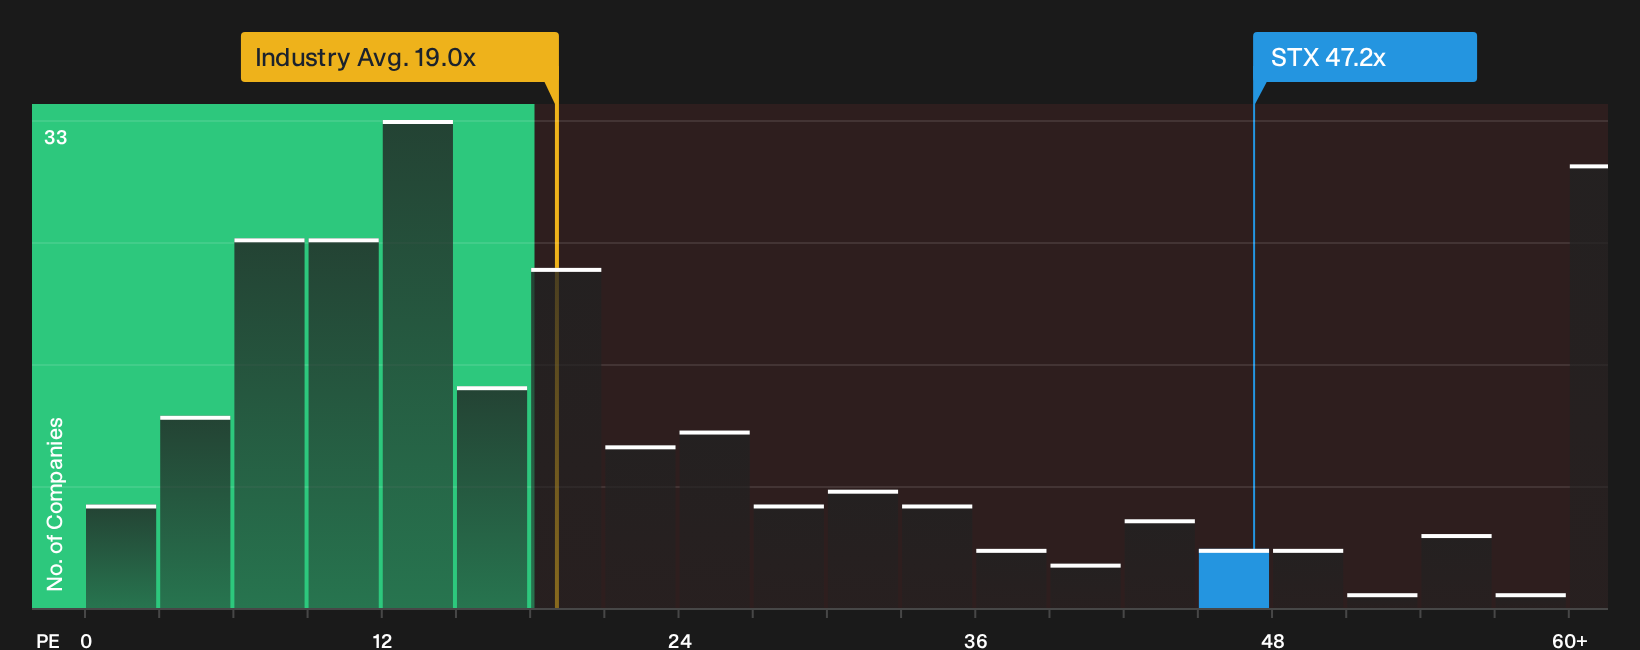
Seagate Technology Holdings screens very differently when you switch from intrinsic value estimates to simple earnings multiples. The stock trades on a P/E of 47.2x, versus 19x for the global tech industry and 21.2x for peers, while the fair ratio sits higher at 56.4x. That gap suggests investors are already paying a premium, even if some models still point to upside. The real question is whether you think Seagate has earned that kind of multiple risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on whether Seagate Technology Holdings is a bargain or a trap right now. Act while the data is fresh and weigh both sides using 3 key rewards and 3 important warning signs.
Looking for more Seagate Technology investment ideas?
If Seagate Technology Holdings has your attention, do not stop with one ticker. Cast a wider net now so you are not chasing opportunities after they move.
- Target potential mispricings and hunt for quality on sale with the 35 high quality undervalued stocks to filter for strong fundamentals at attractive entry points.
- Strengthen your income stream by scanning companies that prioritize reliable payouts using the 8 dividend fortresses tailored for high-yielding, resilient payers.
- Dial down portfolio stress and focus on staying power with the 32 resilient stocks with low risk scores designed to surface businesses with sturdier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com