


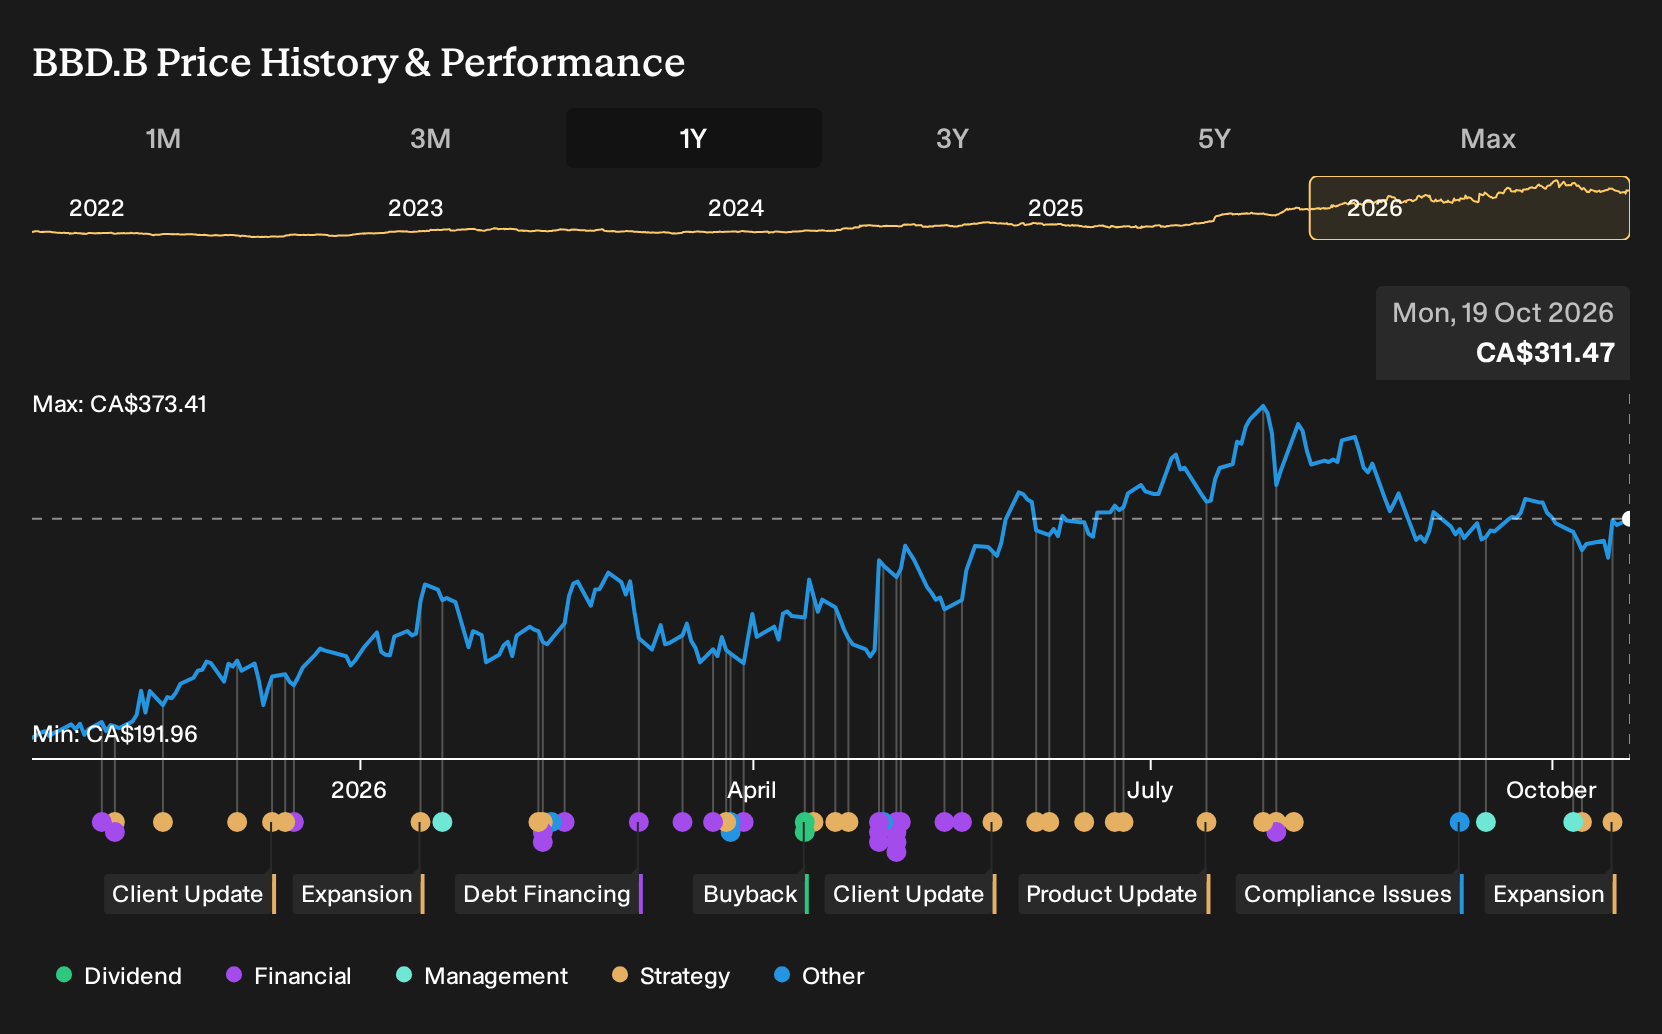
- Bombardier recently committed approximately $50 million to grow its Wichita operations and opened a new Line Maintenance Station in Sydney, expanding its training, maintenance and customer support footprint across North America and Asia Pacific.
- The new Wichita Learning Center and wider service build out indicate a stronger emphasis on recurring aftermarket work, workforce depth and operational resilience, rather than focusing solely on new jet deliveries.
- The next area of focus is how Bombardier's expanded Wichita training hub could influence the existing investment narrative around services and margins.
Scan for other service focused aerospace stocks that aim to turn recurring maintenance and training work into steadier cash flows with our hand picked list of solid balance sheet and fundamentals (7 results) list.
Bombardier Investment Narrative Recap
To own Bombardier, you need to believe the pivot toward higher margin services, premium business jets and defense work can offset its concentrated exposure to business aviation. The key short term swing factor is execution on the existing backlog and aftermarket ramp while carrying high debt and negative equity. The fresh Wichita and Sydney investments look operationally helpful, but do not on their own change that equation.
The biggest near term risk still sits in a potential air pocket in business jet demand or ongoing supply chain friction that keeps inventory and working capital elevated. Expanded training and maintenance capacity may ease the previous constraint that facilities were described as full, yet it also raises the bar on utilization and cash generation that investors will watch closely.
The Wichita Learning Center is the announcement that most directly connects to current catalysts. Bombardier has been leaning into services as a way to build recurring cash flow on a growing installed fleet. A dedicated in house training hub for technicians ties into that push by supporting more consistent staffing for heavy maintenance and Aircraft on Ground work.
For you, the question is whether this build out helps convert the strong services narrative into steadier margins and cash, while the firm still manages a high debt load and negative shareholders equity. If service sites remain near capacity and APAC demand supports the expanded Sydney and future Singapore footprints, that could support the services thesis, but the capital spend also increases execution risk if utilization softens.
Bombardier's current analyst narrative points to $11.8b in revenue and $1.2b in earnings by 2029, implying 6.7% yearly top line growth and an earnings increase of about $247m from $953.0m today.
Uncover how Bombardier's fair value indicates a 17% potential upside to its current price before the discount closes.
Exploring Other Perspectives
You might focus on Bombardier’s new Wichita Learning Center as a clear services win, yet the most bearish analysts were already worried about trade related hits to that services engine. They were only pencilling in about $11.4b of revenue and $1.1b of earnings by 2029. That is a softer path than the $11.8b and $1.2b consensus view. These lower forecasts show how sharply opinions can differ. Use the new service investments as a prompt to compare both narratives and decide which assumptions fit your own expectations.
Explore 4 other Bombardier fair value estimates, including one that suggests as much as 11% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Bombardier research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Bombardier. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bombardier's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bombardier?
If the Bombardier story has you thinking about how services, resilience and balance sheet strength show up in other parts of your portfolio, it can help to widen the lens. Use the Simply Wall St Screener to uncover other businesses that match the kind of risk and return profile you want, instead of relying on a single stock to carry the whole thesis.
- Target steadier compounding by reviewing companies that combine reasonable valuations with strong fundamentals through our 5 high quality undervalued stocks.
- If durability matters more to you than excitement, scan for companies with robust finances and cleaner leverage profiles using the 8 resilient stocks with low risk scores.
- For investors hunting for under followed opportunities with solid numbers behind them, sift through our hand picked 10 high quality undiscovered gems
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com