


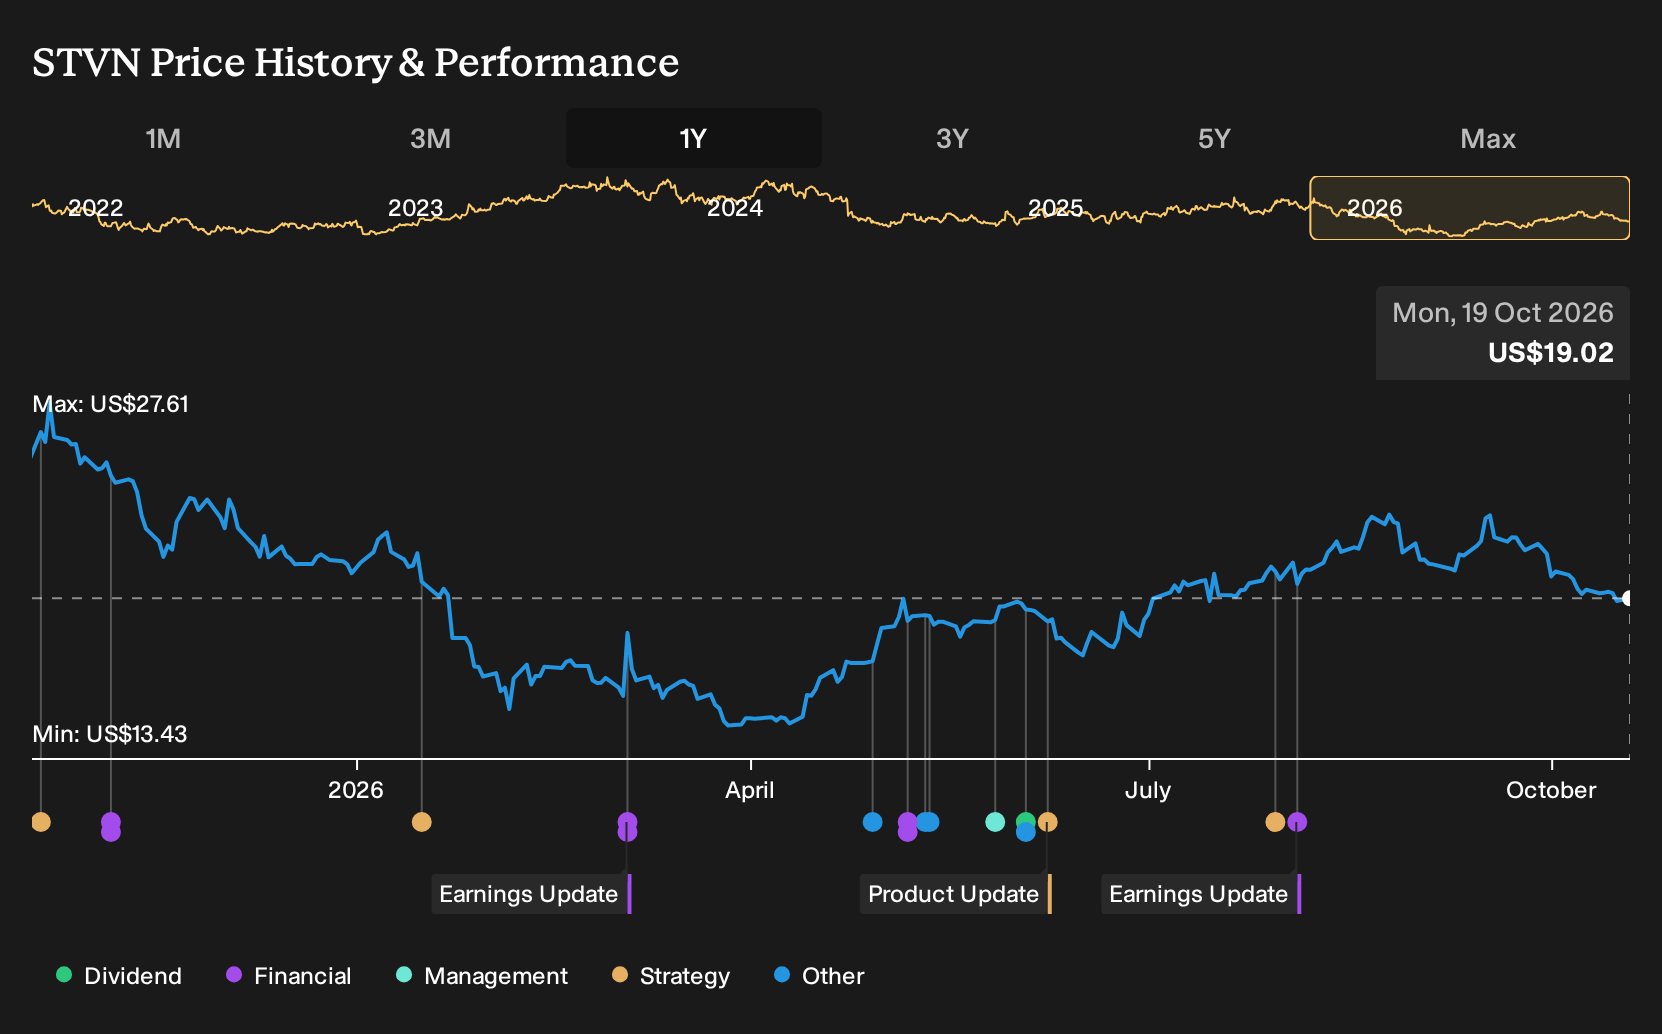
If you had looked only at Stevanato Group’s upbeat commentary on biologics, self-administration devices, and US onshoring back in late 2025, the story might have seemed straightforward. Holding Stevanato Group over the past year would have meant a 26.2% loss, including dividends. If you were weighing an investment then, how much weight would you have given early signs such as rising capital intensity and a softer Engineering backlog before committing fresh money?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Stevanato Group is not the only name tied to this theme. Zero in on 33 healthcare AI stocks and compare how each one is priced.
The Argument You Would Have Been Weighing Up On Stevanato Group
The shares cost US$24.44 at the start of the period. Anyone looking at Stevanato Group then had to choose between two well built stories about where the business might be heading.
The bullish case put Fair Value at US$28.35, based on the idea that rising use of biologics and self administration devices would support demand for high value containment and delivery products.
The bearish view anchored Fair Value at US$23, focused on the risk that tighter rules on plastics and single use medical packaging could raise compliance costs and affect profitability.
What The Results Changed For Stevanato Group
The Q2 2026 figures gave Stevanato Group partial support for the bullish story on biologics and self administration. Revenue reached €302.003 million, above the €280.037 million reported a year earlier, which lined up with demand for GLP 1 related devices and new pen platforms like Deora and Alina. Profit told a different story. Net income fell to €22.958 million and net margin slid from 10.6% to 7.6%, so the higher margin part of the thesis stayed unproven. The evidence cut both ways.
The lesson is simple. When a growth story leans heavily on margin expansion, do not just track sales or new products. Watch net income and the net margin line to see whether new capacity and higher value items are actually turning into better profitability.
What You Would Be Paying For In Stevanato Group Today
Today the Stevanato Group share price is US$19.02, and the selected Narrative places Fair Value above that level, based on how mix, biologics exposure and new facilities might shape earnings quality.
The core question is whether Fishers and Latina can reach the margins described in the Narrative, so the recent fall represents an execution test rather than a simple warning.
"The main factor that needs to go right is the successful ramp and margin improvement of the Fishers and Latina facilities, including cartridge and syringe capacity, so that higher value products translate into the earnings and cash generation the company is targeting."
One Narrative disagrees with today's price. → See where this Narrative says Stevanato Group should trade
Looking Beyond Stevanato Group
Stevanato Group leans on rising demand for complex therapies and devices. You could also look at businesses built around those same treatments.
As more specialized drugs reach patients, healthcare providers still need tools that diagnose, operate and monitor effectively. One large manufacturer concentrates on medicines and equipment for surgery, cardiovascular care and vision.
Its therapies target high medical need, including cancer, immune disorders and mental health. On the device side, it develops systems that support joint repair, heart procedures and advanced eye care.
Those areas can pull in capital and regulatory scrutiny, along with clinical risk. The interesting question is how a broad portfolio might handle those swings over time.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 26% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com