


- Trane Technologies recently announced a multi year agreement to serve as Kroenke Sports & Entertainment’s Climate Innovation partner and official HVAC and thermal management provider across venues including SoFi Stadium, YouTube Theater, Hollywood Park and Ball Arena.
- This partnership gives Trane Technologies deeper exposure to large venue infrastructure projects where energy efficient systems, digital services and real time emissions tracking are central to customer decisions and long term service relationships.
- We will now look at how Trane Technologies' investment narrative could be influenced by this expanded role across KSE venues.
Scan beyond Trane Technologies and this KSE deal to see which other infrastructure focused companies screen well for balance sheet strength and cash generation with our curated list of solid balance sheet and fundamentals (25 results).
Trane Technologies Investment Narrative Recap
To own Trane Technologies, you need to be comfortable with a story built on Commercial HVAC strength, a growing services mix and data center related demand. The short term swing factor remains how efficiently that US$12.1b backlog converts into revenue without eroding margins through pricing or regional mix pressure. The new Kroenke partnership likely helps long term brand and project visibility but does not materially change that near term catalyst.
The key risk still sits in concentration. If large non residential projects, including data centers, slow or are deferred, that same backlog could turn into a drag on growth and earnings. Margins also look sensitive to cost inflation and pricing execution, especially with current profit margins of 13.5% sitting below last year’s 13.9%.
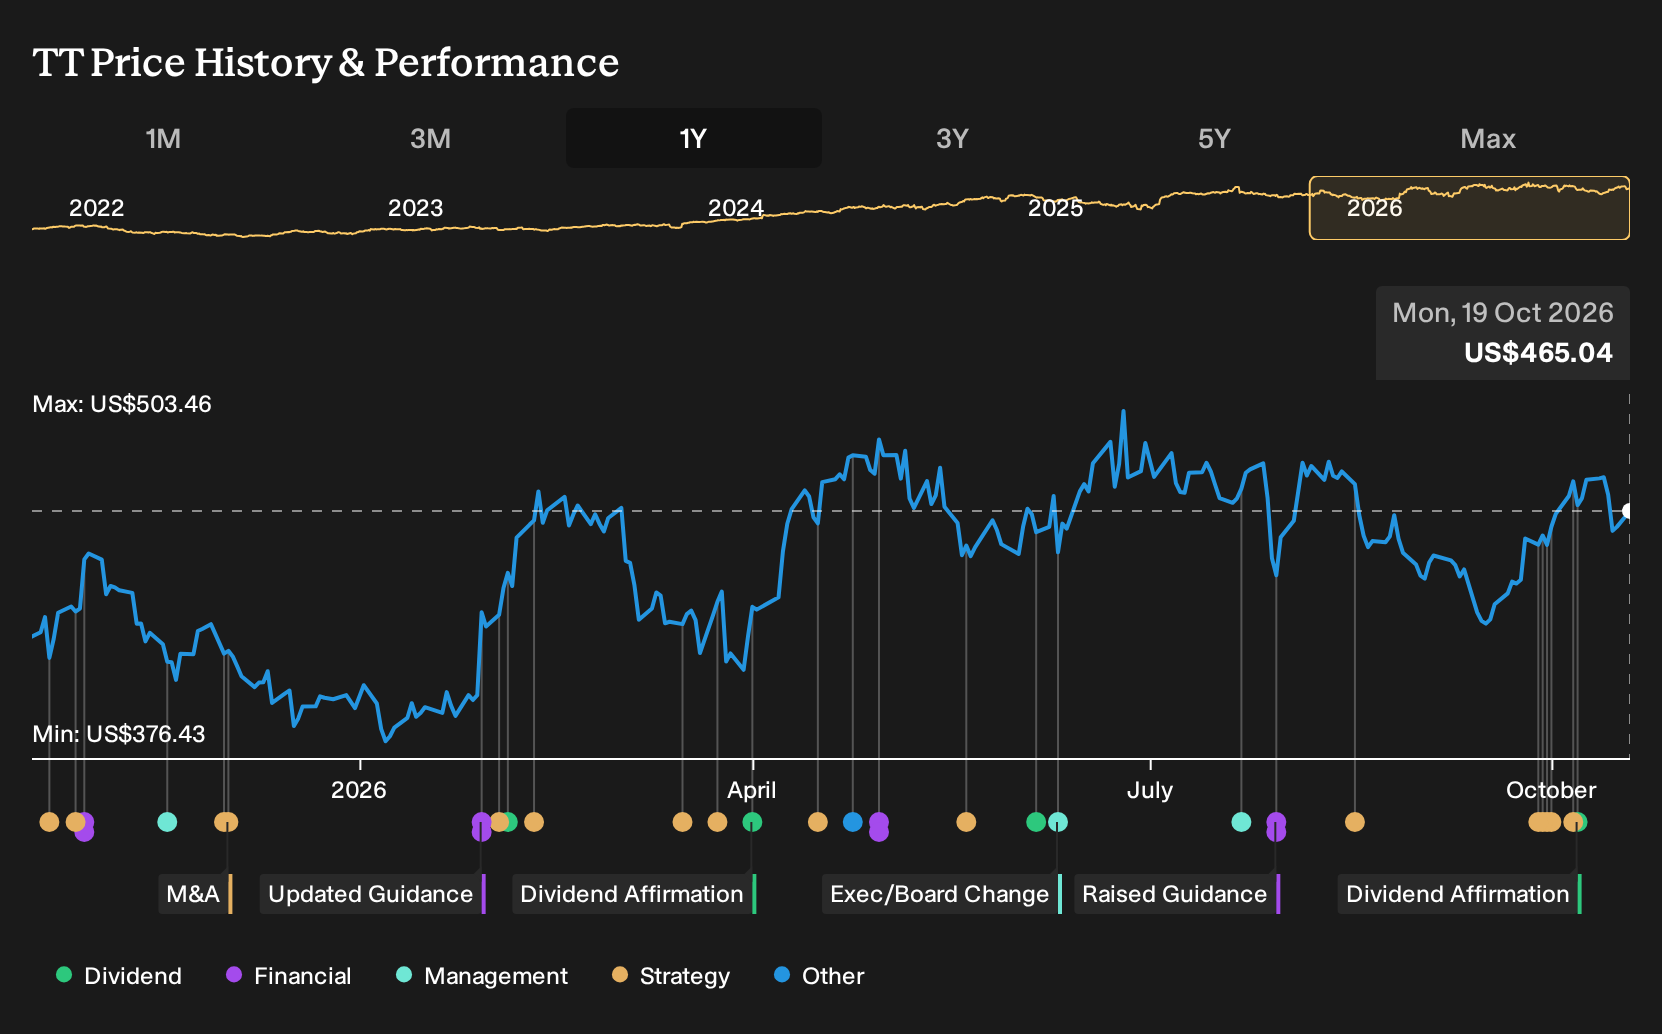
The fresh data point that ties closest to this story is the Board affirming a quarterly dividend of US$1.05 per share, or US$4.20 annualized, payable on December 31, 2026. Management is signalling confidence in cash generation, which matters when you are evaluating a business that leans hard on a large order book and expanding services.
For you as an investor, that payout sits alongside Trane Technologies’ push into venue infrastructure such as the KSE agreement and into higher value digital services. The dividend does not change the core catalysts built around Commercial HVAC, energy efficiency and data center cooling capacity, but it does raise the bar on maintaining healthy free cash flow through any slowdown in big project activity.
Trane Technologies is currently framed by analyst expectations that revenues reach US$29.5b and earnings reach US$4.7b by 2029, based on 10.0% yearly top line growth and an increase in earnings of about US$1.7b from US$3.0b today.
Discover why Trane Technologies' fair value indicates a 13% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Trane Technologies focuses squarely on margin pressure. The most cautious analysts were modeling revenue of about US$28.6b and earnings of roughly US$4.6b by 2029, prior to this Kroenke deal and the dividend affirmation. That is a more pessimistic story. Use it as a reminder that opinions can spread widely and that this new information may eventually reshape both bullish and bearish forecasts.
Explore 4 other Trane Technologies fair value estimates, including one that suggests there could be as much as 18% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider trusting your own analysis and instincts.
- A great starting point for your Trane Technologies research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Trane Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trane Technologies' overall financial health at a glance.
Looking For More Trane Technologies Investment Ideas?
If the Trane Technologies story has you thinking about portfolio balance, use screeners to surface other businesses with fundamentals that fit your style instead of relying on headlines or hunches.
- For investors who want quality at a sensible entry point, start with companies that combine resilient balance sheets and attractive valuations through our 35 high quality undervalued stocks.
- If stability matters more than excitement, focus on businesses that score well on resilience and risk, filtered through the 32 resilient stocks with low risk scores.
- If you prefer potential upside in less followed corners of the market while still caring about fundamentals, then the 20 high quality undiscovered gems is a useful hunting ground.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com