


Holding Vestas Wind Systems over the past year would have returned 51.2%, including dividends. If you had been weighing a purchase on 19 October 2025, you were staring at two published views that were miles apart: one arguing policy support could expand wind demand and another warning that tariffs and Chinese rivals could squeeze margins hard. With that split on record, which pressures and supports would you have focused on most before committing capital?
The move put Vestas Wind Systems in the middle of this trade. Scan 42 power grid technology and infrastructure stocks for other companies exposed to it.
The Argument You Would Have Had To Settle On Vestas Wind Systems
The shares cost DKK129 at the start of the period, and investors were being asked to choose between two sharply different stories for Vestas Wind Systems.
The bullish narrative pointed to policy support and grid reforms and said the stock was worth DKK141, a rough estimate of value if its assumptions played out, leaning on 7.6% revenue growth and profit margins rising toward 5.8%.
The bearish view put Fair Value at DKK60 and treated rising tariffs and lower cost Chinese rivals as the key risk that could keep profit margins closer to 3.8%.
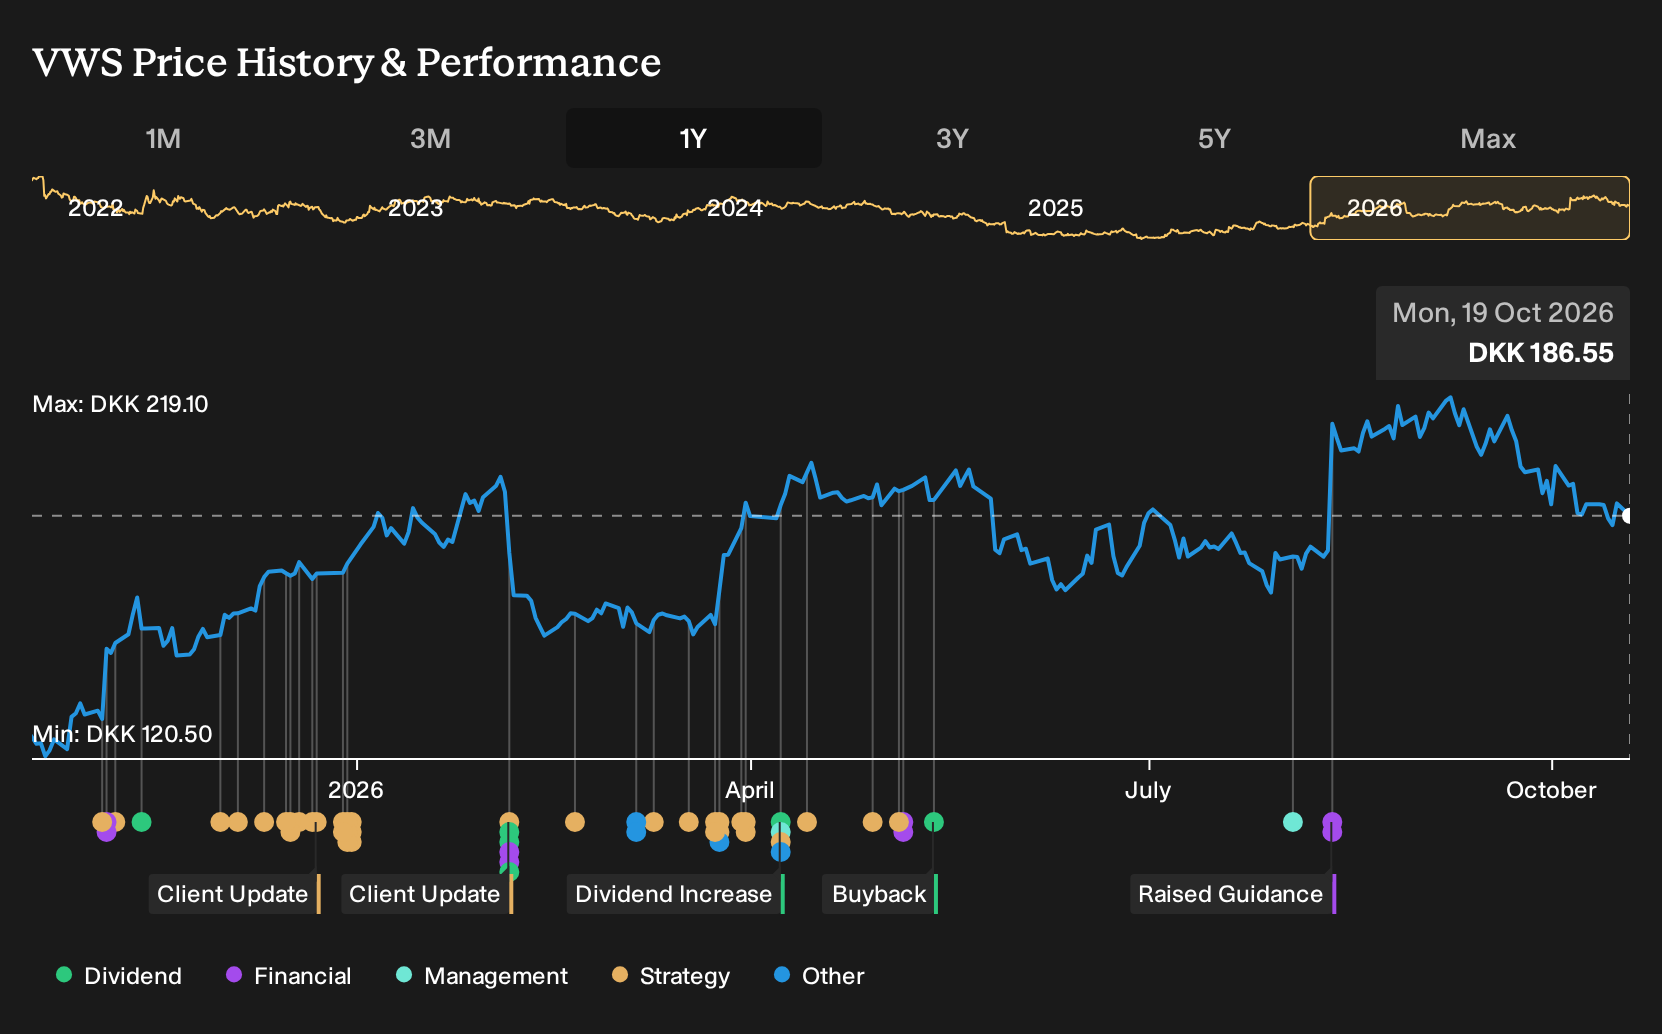
What The Evidence Did To The Vestas Wind Systems Debate
Fresh orders, product launches and contracts gave Vestas Wind Systems real-world backing for the demand story. Turbine deals in Canada, Peru, Bulgaria and Japan, plus the first 7.2 MW V182 order in Sweden, lined up with the supportive case that policy and project pipelines could feed the top line. Rising revenue, higher profit and a net margin moving from 0.9% to 5.9% in Q2 2026 reinforced that tilt toward the optimistic side.
The lesson is simple. When a thesis hinges on margin recovery as much as on order volume, you track both. For the next company on your list, test the story against reported contract wins, then check whether net margin actually moves toward the level the bullish or cautious case assumed.
What Vestas Wind Systems' 51% Run Already Assumes
Vestas Wind Systems now trades at DKK187 after a 51.2% gain over the past year. The selected Narrative places its Fair Value below that level, arguing that the current price already bakes in a relatively smooth margin and cash flow story.
The Narrative centres on offshore technology risk, service profitability and the strain these could put on cash returns. For today’s valuation to hold up, a buyer would need to believe offshore issues like blade failures remain contained enough for margin recovery and capital distributions to progress together.
"The current valuation implies that Vestas Wind Systems is priced for a smooth path to double digit EBIT margins and sustained high capital returns that leave little room for earnings disappointments or offshore setbacks. Although Vestas Wind Systems is increasing offshore deliveries and reporting better manufacturing and installation efficiency, the recent blade failure at the He Dreiht project highlights that unresolved technology and execution risk could trigger additional remediation work, higher warranty usage and potential project penalties that weigh on EBIT margins and earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 36% below our estimate - uses expanded headset and intercom range to address drone mission communication needs.
- Company 2 - 27% below our estimate - rolls out smaller stores and online channels to increase earnings efficiency per peso.
- Company 3 - 50% below our estimate - turns early overseas clinical use into ongoing demand for vascular intervention products.
Those are three of them. See every one of the 199 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com