


Why Cleveland-Cliffs' Latest Results Matter For Investors
Cleveland-Cliffs (CLF) just posted third quarter earnings that shifted the story from red ink to profit, with higher sales, positive net income and better earnings per share compared with last year.
The update on the first nine months of 2026 also showed higher revenue and a much smaller loss than the prior year period, giving investors fresh numbers to reassess the stock.
The latest results landed alongside a sharp move in the shares, with Cleveland-Cliffs' 1-day share price return of 16.34% and 90-day share price return of 52.43% pointing to rapidly building momentum, even as the 1-year total shareholder return is still down 12.86%.
Scan how Cleveland-Cliffs' earnings rebound compares with other potential turnaround plays by checking our handpicked list of 35 high quality undervalued stocks.
The sharp jump in Cleveland-Cliffs' share price sits between two stories. Is this mainly a catch up to the earnings rebound, or a burst of optimism that outran the fundamentals?
Most Popular Narrative: 12% Overvalued
Cleveland-Cliffs last closed at $14.10 while the most followed narrative pegs fair value at $12.60, so the recent rally sits above that anchor and puts more weight on execution against the key earnings drivers.
The main factor is continued execution on cost reductions, footprint optimization, and DOE-backed projects so that lower unit costs and a higher value-added steel mix show through consistently in earnings and cash flow.
DOE backed investment at Middletown Works and the Butler Works grain oriented electrical steel expansion, together totaling up to US$1.2b of projects with grant support, are aimed at more efficient and higher value production that can lift Cleveland-Cliffs revenue mix and operating margins over time.
See why 59 investors see Cleveland-Cliffs as 12% overvalued.
Result: Fair Value of $12.60 (OVERVALUED)
Still, the Cleveland-Cliffs story depends heavily on continued tariff protection and on avoiding fresh input cost shocks that could erode the recent earnings recovery.
Find out about the key risks to this Cleveland-Cliffs narrative.
Another View On Cleveland-Cliffs' Valuation
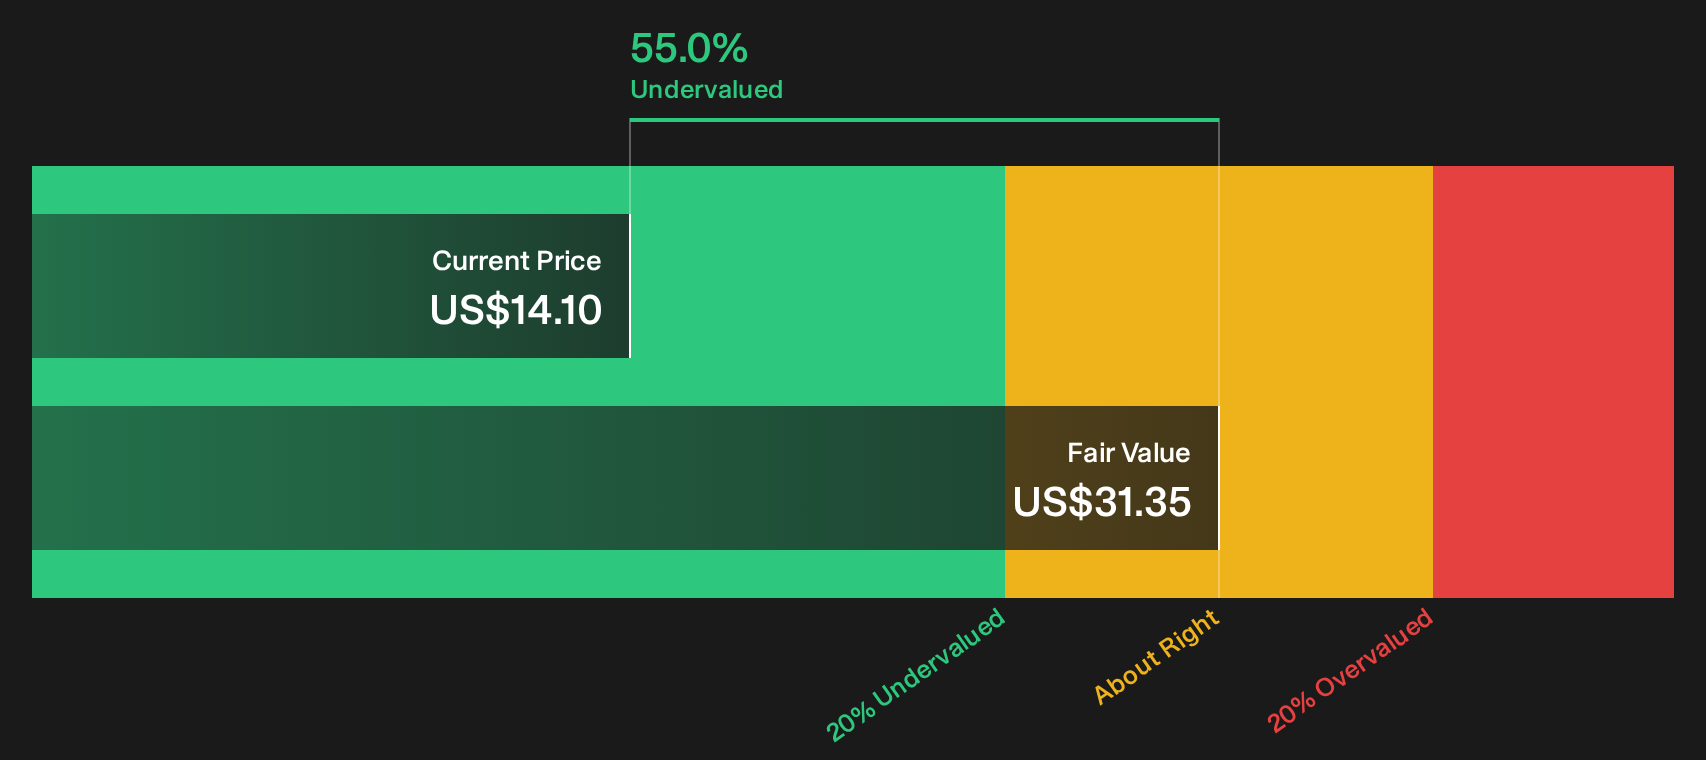
The analyst-led narrative tags Cleveland-Cliffs as overvalued around a fair value of $12.60, yet the SWS DCF model points in the opposite direction. That cash flow based approach suggests the shares trade about 55% below an estimated value of $31.36, which implies a very different margin of safety. Which story do you think deserves more weight?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of optimism and concern around Cleveland-Cliffs feels familiar, treat it as your cue to review the data yourself, act promptly, and weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Cleveland-Cliffs?
If Cleveland-Cliffs sharpened your focus today, do not stop here. Broaden your watchlist now and give yourself more quality options for the next move.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations through the 35 high quality undervalued stocks.
- Anchor your portfolio with businesses that aim for resilience and stronger balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities with robust fundamentals before the crowd notices through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com