


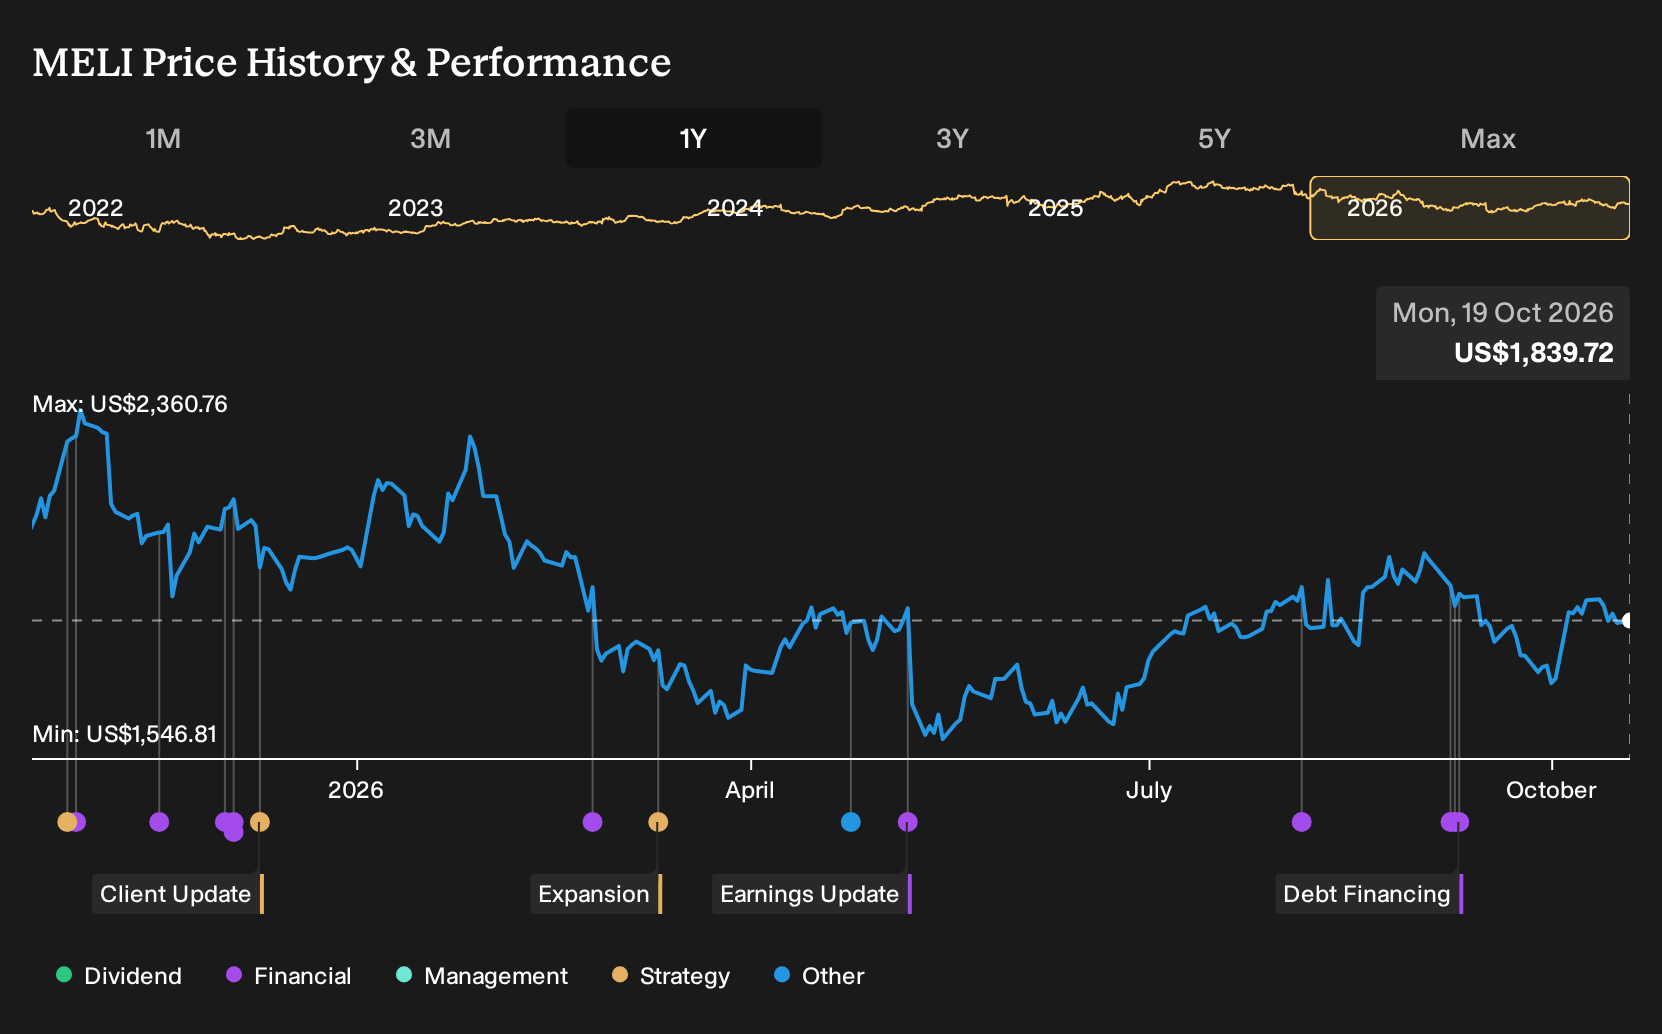
- MercadoLibre recently rolled out one-hour delivery in São Paulo and moved into selling prescription medicines, while reporting strong Q2 revenue alongside weaker operating income and thinner margins, and raising US$1b in long term notes to support logistics and credit initiatives.
- The push into ultra fast delivery and prescription drugs in Brazil adds new cost and execution demands. At the same time, margin pressure and debt funded investment make the balance between growth and profitability more important for MercadoLibre’s long term business profile.
- We will look at how MercadoLibre’s investment narrative holds up as one hour delivery in São Paulo ramps and strains profitability.
Compare MercadoLibre’s push into ultra fast delivery and credit with other high conviction e-commerce and fintech plays by scanning our hand picked 20 high quality undiscovered gems that are still off most investors’ radar.
MercadoLibre Investment Narrative Recap
To own MercadoLibre, you need to buy into a simple idea: heavy investment in logistics, free shipping and credit eventually supports healthier unit economics across both commerce and fintech. The one hour delivery push in São Paulo and entry into prescription drugs increase near term cost intensity, but do not fundamentally change that thesis.
The near term swing factor is whether revenue growth and user engagement stay strong enough for margins to stabilise after recent compression from 8.5% to 5.3%. The biggest current risk is that rising logistics and credit costs, layered on a higher debt load, keep profitability subdued for longer than expected.
The most relevant recent move tied to this news is the US$1b long term notes issuance. That extra funding directly connects to logistics and credit expansion, which are exactly where one hour delivery and Mercado Credito push operating risk higher and make execution quality more important.
For catalysts, that capital raise gives MercadoLibre room to keep building out its fulfillment network and credit book without immediately cutting back on free shipping or marketing. The flip side is clear: higher leverage and a growing loan portfolio mean any deterioration in credit quality or weaker cash generation from logistics could pressure returns on that US$1b and weigh on future flexibility.
MercadoLibre’s current consensus narrative points to revenues of US$75.8b and earnings of US$5.2b by 2029, which aligns with analysts assuming roughly 29.1% yearly revenue growth and an increase in earnings of about US$3.3b from US$1.9b today.
Uncover why MercadoLibre's fair value indicates a 23% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on MercadoLibre’s credit and ecosystem flywheel. Before this one hour delivery and prescription move, they were modeling revenues of US$82.6b and earnings of US$6.1b by 2029, compared with the US$75.8b and US$5.2b that the baseline group used. Your view might shift as this news gets fully priced into those forecasts.
Explore 17 other MercadoLibre fair value estimates, including one that suggests as much as 90% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MercadoLibre research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MercadoLibre. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MercadoLibre's overall financial health at a glance.
Looking For More Ideas Beyond MercadoLibre?
Once you have a view on MercadoLibre, it can help to widen the lens and compare it with other businesses that fit different risk, income, and quality profiles. The Simply Wall St Screener lets you quickly filter the market down to a focused shortlist that matches what you are actually looking for.
- If you want a shot at mispriced quality, start with a focused group of 35 high quality undervalued stocks that combine strong fundamentals with more conservative pricing.
- For investors who care most about capital resilience, narrow your search to a 32 resilient stocks with low risk scores that screens for steadier balance sheets and lower risk scores.
- If income is a priority, build your watchlist around a 8 dividend fortresses that targets companies offering 5%+ yields with an emphasis on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com