


DoorDash (DASH) just secured FAA Part 135 air carrier certification, clearing the way for its own DoorDash Air drone delivery program and putting aerial logistics directly on the radar for anyone tracking the stock.
Recent moves show how that certification fits into a broader push by DoorDash to widen its reach, from adding Macy's and other retailers to opening a new hub in India and extending rewards into restaurant reservations alongside DashPass. Despite these efforts, the share price return over the past year has declined 11.95% year to date, and the total shareholder return over one year is down 27.07%. The three year total shareholder return of 158.70% signals longer term momentum that investors are still weighing against current risks and valuation.
Scan how DoorDash’s drone push compares with other delivery and commerce platforms by running your filters against 20 high quality undiscovered gems focused on logistics, local services, and last mile efficiency.
DoorDash now has a drone certificate, a fast growing non U.S. footprint, and a stock that has fallen double digits this year. Do those pieces still justify the current price or skew the odds toward caution?
Most Popular Narrative: 24% Undervalued
DoorDash’s most followed thesis anchors on a fair value of $256.26 per share, which sits well above the recent $193.53 close and presents today’s drone, grocery, and international moves as part of a much larger earnings story.
Record performance of DashPass and Wolt+ subscriptions, including a recent period where DoorDash added more paid DashPass subscribers in one year than in the prior two years combined, supports a growing base of recurring, higher margin revenue and higher gross profit per MAU that can compound into earnings growth.
See why 79 investors see DoorDash as 24% undervalued.
Result: Fair Value of $256.26 (UNDERVALUED)
Still, the DoorDash story can be knocked off course if regulatory penalties spread beyond the US$131.5 million New York settlement or if online grocery affordability limits its ability to raise prices.
Find out about the key risks to this DoorDash narrative.
Another View: DoorDash Through The P/E Lens
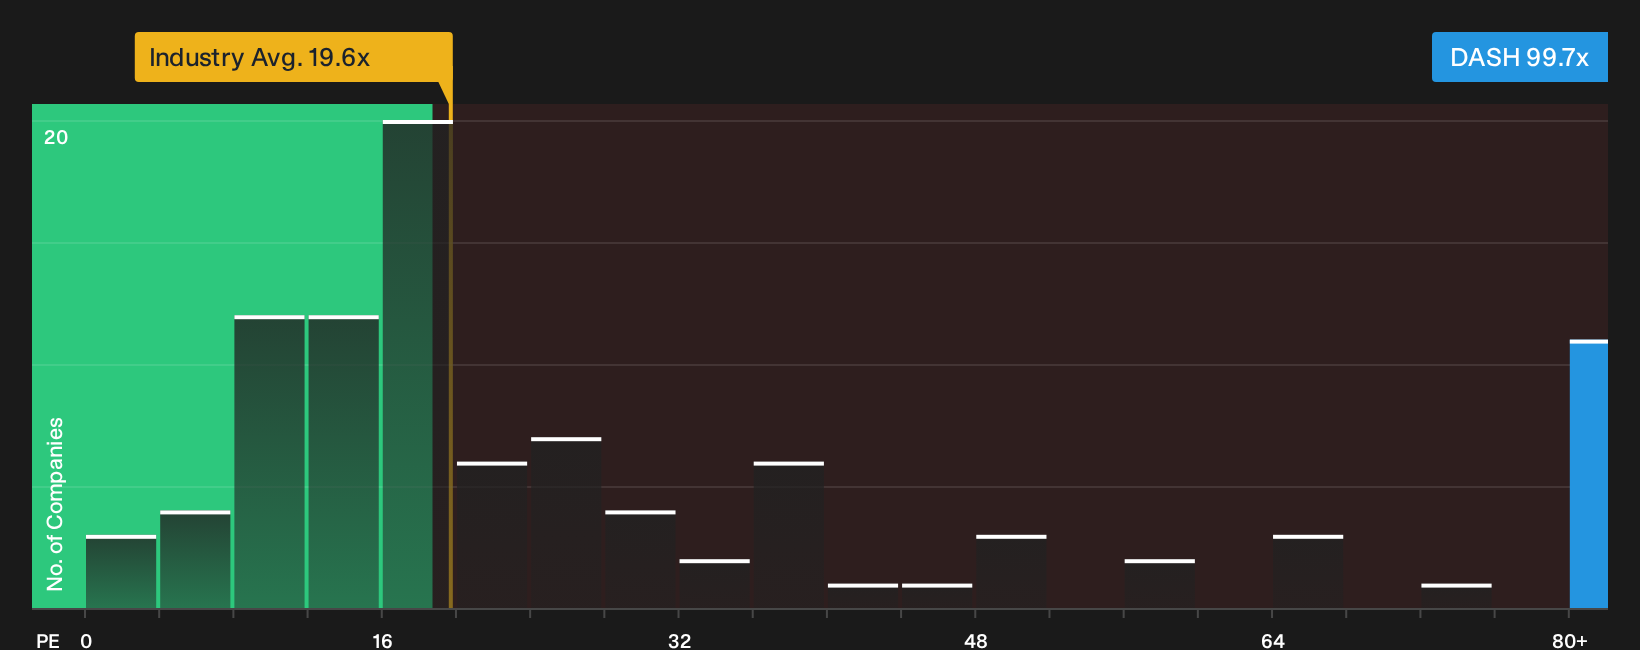
The first fair value story paints DoorDash as undervalued, yet the simple P/E check reads very differently. The stock trades on about 99.7x earnings versus a fair ratio of 46.6x, the US Hospitality group at 19.6x, and peers near 30x. That gap raises a blunt question for you: is this a premium you are comfortable paying for the current growth story, or a valuation risk that deserves a wider margin of safety?
To stress test that, focus on how this rich multiple compares with our fair ratio view and with sector and peer levels. Then ask what would need to happen for the P/E to compress toward those anchors without eroding your thesis. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these rarely stay unresolved for long, so use the gap between the drone story and the valuation debate to review the numbers yourself and move quickly while the DoorDash thesis is still in flux. To weigh both sides of the argument in one place, start with 4 key rewards and 1 important warning sign.
Looking for more DoorDash style investment ideas?
Do not stop with DoorDash. Use this moment to widen your watchlist and pressure test your thesis against other opportunities that fit different risk and return profiles.
- Target potential mispricing by scanning companies that combine quality fundamentals with valuation support using the 35 high quality undervalued stocks.
- Fortify your income stream by focusing on businesses that prioritise regular cash returns to shareholders through the 8 dividend fortresses.
- Dial down portfolio stress by concentrating on financially resilient businesses screened through the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com