


EMCOR Group has delivered a striking long term share price run, and with the stock now around US$716.79 the obvious question is whether that level still lines up with the earnings the business produces. After such a move, the issue for you is not just where the price has been, but what the current valuation implies about the profit stream ahead.
- Over the past 5 years EMCOR Group has returned very close to 5x an initial investment, which raises the question of how much of its earnings strength may already be reflected in the current P/E.
- The company’s model in mechanical, electrical and facilities services can support relatively steady earnings tied to long term projects, so pricing today may hinge on how reliable investors think those profit streams are.
- The analysts covering EMCOR Group have run their own numbers. See what analysts think EMCOR Group's shares could be worth.
The stock’s next move may depend on whether EMCOR Group’s current share price can be squared with the earnings power that investors are paying for today.
If you want to test this same earnings driven valuation question beyond EMCOR Group, line it up against a wider field using the 35 high quality undervalued stocks
Is EMCOR Group Still Cheap on Earnings?
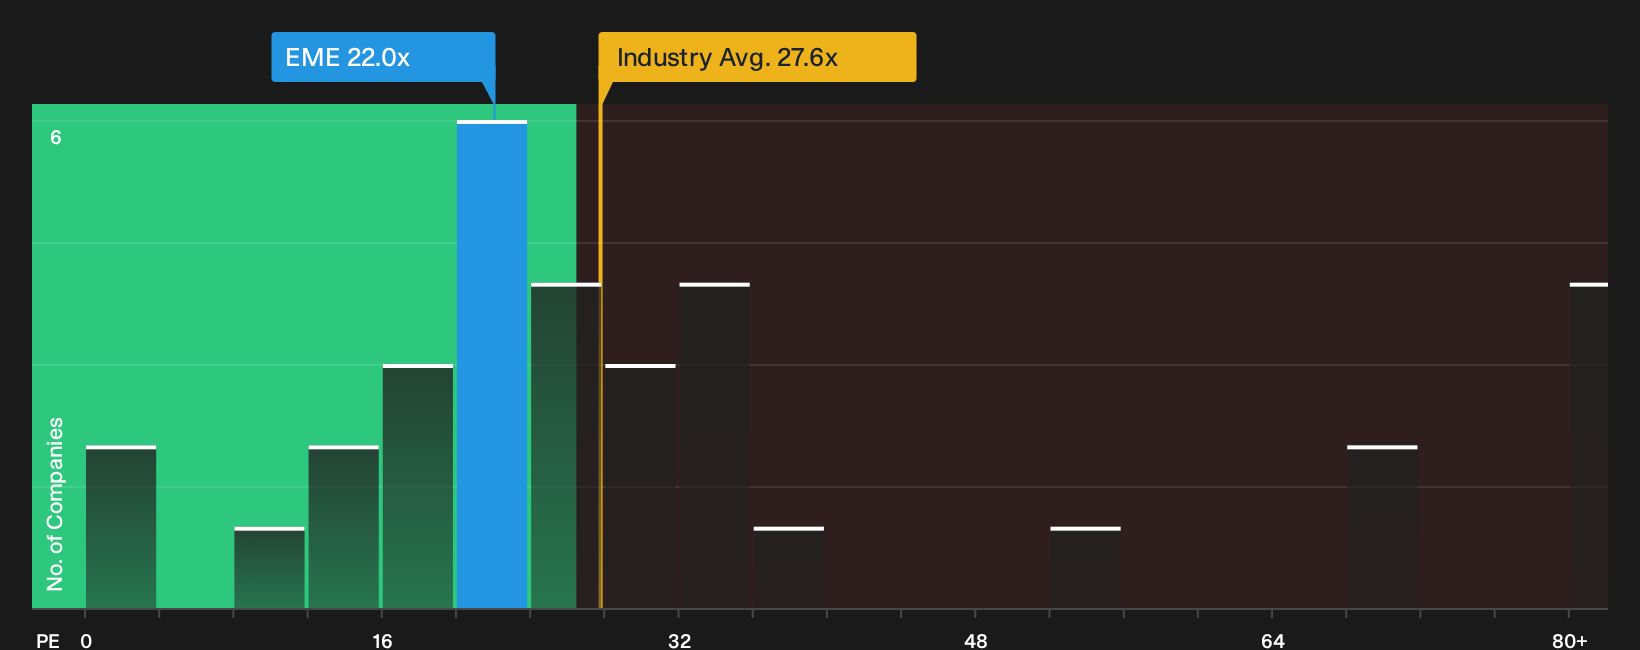
The P/E ratio fits EMCOR Group well because earnings are a core reference point for contractors with long duration service work. On this measure, the stock trades at about 22.0x current earnings, which is below the wider construction industry on roughly 27.6x and also under a broader peer set near 41.6x. For an investor, that means the market is assigning a lower price tag per dollar of EMCOR Group’s profit than it does for many comparable businesses.
A fair value model that blends the firm’s growth profile, margins, size and risk suggests EMCOR Group could justify a higher P/E than where it trades today. The present multiple therefore sits below that tailored reference point, which indicates the market is not paying up fully for the earnings profile implied by the model. The question for you is whether the quality and resilience of those profits match what that higher ratio assumes, or whether the current discount is a more appropriate reflection of risk. Explore the numbers behind EMCOR Group's P/E valuation.
The EMCOR Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where EMCOR Group's P/E puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to unfold for the stock to be worth materially more or materially less than today’s price, and they sit on the Community page alongside investor discussion. Each Narrative ties a fair value to a particular storyline about EMCOR Group's possible catalysts and pressures, so you can track over time which version of events seems closest to reality.
One of the top community narratives on EMCOR Group: 31% undervalued
Expanding AI and cloud data center construction pipelines, reflected in very strong network and communications revenue growth and larger mechanical and electrical content per site…
Discover why this Narrative puts EMCOR Group at 31% undervalued.
EMCOR Group’s valuation still hinges on one unresolved piece
The numbers only show what the business earns today, while the people who set priorities and how they are rewarded can shape what those earnings look like in the future. See who runs EMCOR Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com