


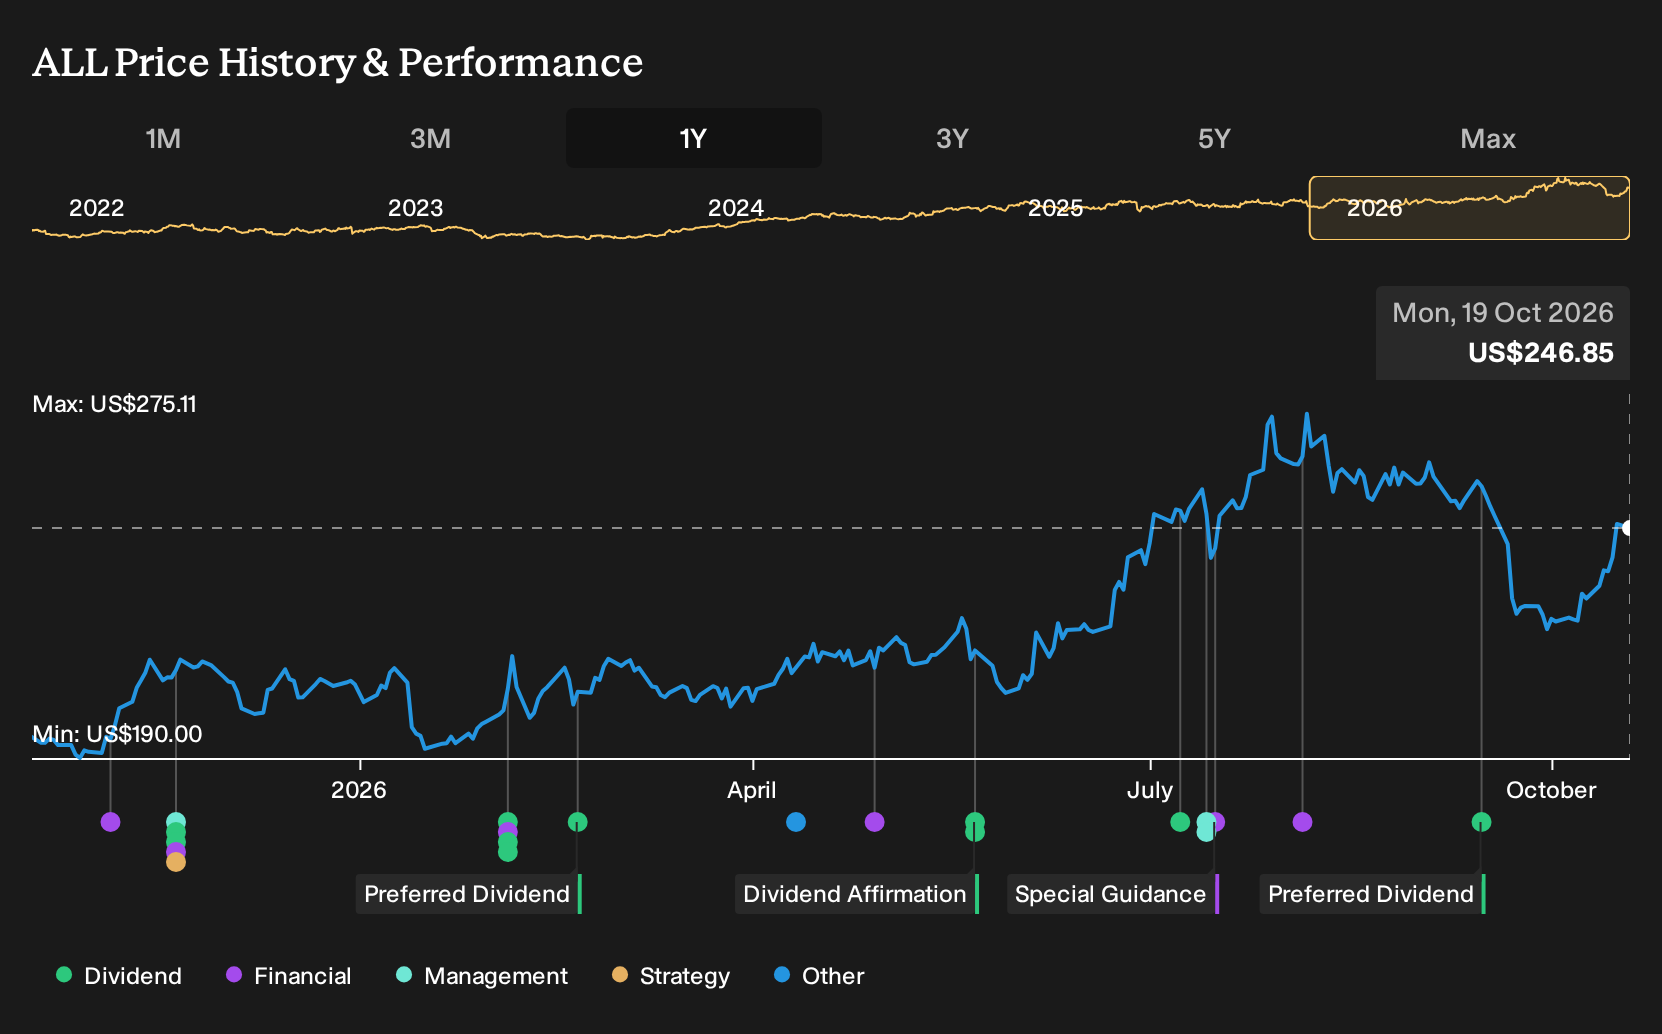
- Allstate is heading into its next earnings report with a recent record of outperforming expectations, including an average surprise of 49.71% over the last two quarters and a current positive Earnings ESP of 3.38%, tied to the November 4, 2026 release.
- Beyond headline profits, Allstate is also expanding its data capabilities as subsidiary Arity moves to acquire most assets of transportation intelligence provider INRIX, aiming to deepen insight into how people, vehicles and roads interact.
- This article examines how Allstate's earnings surprise potential shapes the investment narrative and what that could mean for investors.
Scan how Allstate's setup compares with other potential movers by checking a hand picked group of 35 high quality undervalued stocks that may also be primed for their next catalyst.
Allstate Investment Narrative Recap
To own Allstate, you need to believe this insurer can keep turning its data heavy model and underwriting discipline into steady profitability while living with weather, legal and competitive shocks. The key near term swing factor remains catastrophe experience and how well pricing, reinsurance and state level exposure management keep combined ratios in check.
The recent earnings surprise pattern and positive Earnings ESP highlight potential near term upside to reported results, but they do not change the core risk that large storms and regulatory pushback can quickly pressure margins. If catastrophe losses stay high or rate actions face tighter scrutiny, the path to more stable earnings becomes harder.
The Arity agreement to acquire most INRIX assets is one of the more operationally relevant updates for Allstate. It concentrates on a simple idea: better data on how people and vehicles move can feed underwriting, pricing and claims models across auto and mobility related protection products over time.
For catalysts, that matters because Allstate already leans on more than 250 analytical models and its ALLIE AI ecosystem to manage loss and expense ratios. The INRIX platform could extend those tools into richer traffic and road condition insight. However, integration risk, regulatory scrutiny of data use and execution on monetising telematics at scale remain key watchpoints.
Allstate's current earnings of US$13.2b are set against analyst forecasts for earnings of US$3.9b by 2029. This implies an earnings decline of US$9.3b, alongside an assumed 2.7% yearly revenue growth rate that would take revenue to US$76.0b in the same year.
Uncover why Allstate's fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One contrasting angle focuses less on Allstate’s tech buildout and more on slower core growth. The most cautious analysts were pencilling in revenue of about US$72.7b and earnings of roughly US$3.9b by 2029. That outlook was set before the INRIX deal and fresh earnings surprise signals, so some views may shift as new data lands.
Explore 5 other Allstate fair value estimates, including one that suggests as much as 21% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Allstate research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Allstate. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Allstate's overall financial health at a glance.
Looking For More Investment Ideas Beyond Allstate?
Once you have a view on Allstate, it often helps to set it alongside other opportunities that match your preferred style, risk level and income needs. The Simply Wall St Screener lets you do exactly that by filtering the market down to a focused shortlist in a few clicks.
- If capital preservation is your priority, start with sturdier balance sheets and compare Allstate against a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- If you care most about consistency and lower volatility, narrow your search to a 32 resilient stocks with low risk scores and see which businesses line up with your comfort zone.
- If you want to widen the opportunity set beyond Allstate, scan a 20 high quality undiscovered gems that pairs solid fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com