


Enliven Therapeutics (ELVN) recently confirmed final alignment with the U.S. Food and Drug Administration on the ENABLE-2 Phase 3 trial design for relcobatinib in previously treated chronic myeloid leukemia.
Enliven Therapeutics has had a choppy few months, with the share price down 21.74% over 30 days and 28.77% over 90 days, even after a 3.70% one-day share price gain left it at US$38.70. That sits against a strong backdrop, with year to date share price return of 149.03% and a 3-year total shareholder return of 202.34% signalling momentum that has been building over a longer horizon. The recent confirmation of the ENABLE-2 Phase 3 design and the October 2026 appointment of Kristine Ball to the board help explain why investors are weighing both growth potential and execution risk more sharply in the current price.
Scan biopharma names facing similar late-stage clinical catalysts to Enliven Therapeutics by running the curated 20 high quality undiscovered gems, which focuses on under-the-radar companies with strong underlying fundamentals.
Given Enliven Therapeutics now trades around US$38.70 against analyst estimates clustered near US$74.62, the real focus shifts to where fair value plausibly sits between recent volatility and the implied upside.
Most Popular Narrative: 48% Undervalued
The most followed narrative on Enliven Therapeutics pegs fair value around $73.90, almost double the last close of $38.70. This puts the spotlight squarely on whether the ENABLE program can justify that gap.
The differentiated safety and tolerability profile of ELVN‑001, with 6% of 161 treated patients discontinuing due to adverse events and low rates of severe hematologic and arterial occlusive events, aligns with long term CML treatment needs and may support better persistence on therapy, which directly affects lifetime revenue per patient and potentially supports stronger margins.
See why 1 investors see Enliven Therapeutics as 48% undervalued.
Result: Fair Value of $73.90 (UNDERVALUED)
Still, the narrative around Enliven Therapeutics hinges on clinical execution and future profitability assumptions, so any trial setback or weaker margin outcome could quickly challenge that 48% undervalued view.
Find out about the key risks to this Enliven Therapeutics narrative.
Another View: What Enliven Therapeutics’ P/B Says
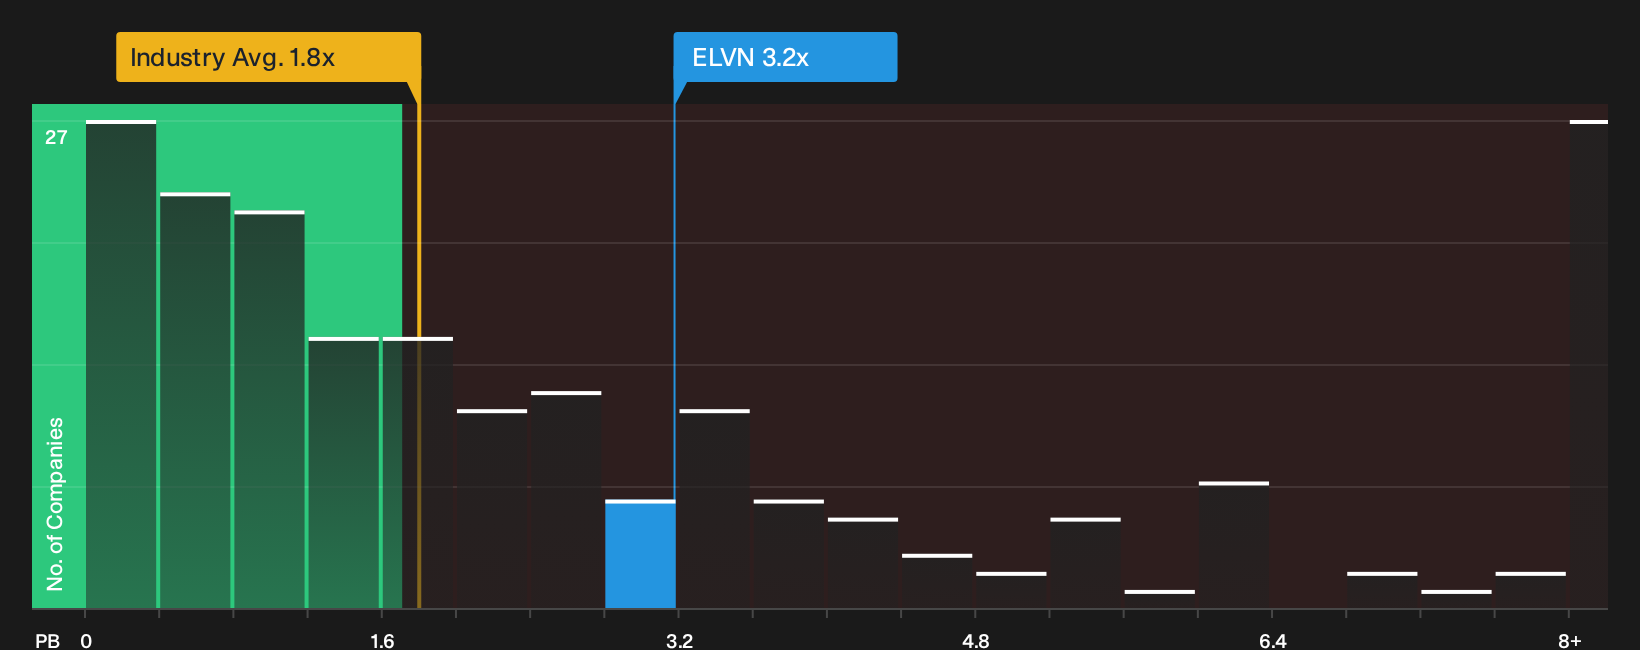
The first narrative leans heavily on long range earnings forecasts. A simpler lens looks at Enliven Therapeutics on price to book. The shares trade around 3.2x book value, which is richer than the broader US Pharmaceuticals group at 1.8x and still below the 8x level seen across closer peers. That mix suggests investors are already paying a premium to the sector while the peer set prices in much more optimism, so the question becomes whether you see more risk in the premium shrinking or in the peer gap closing.
To pressure test that view against hard numbers, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Enliven Therapeutics can either paralyze you or encourage you to examine the numbers yourself. Use the detailed breakdown of 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Enliven Therapeutics?
If you stop with Enliven Therapeutics, you risk missing other setups that could fit your goals even better, so cast the net a little wider.
- Target potential mispricings by scanning a curated pool of quality opportunities through the 35 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with strong finances using the list of solid balance sheet and fundamentals (25 results).
- Seek steadier compounding by filtering for companies with robust cash generation through the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com