


Fresh commentary around Vtech Holdings (SEHK:303) has zeroed in on its relatively low P/E multiple, with investors weighing how global expansion plans and manufacturing shifts might influence perceived undervaluation and future profit resilience.
Recent trading tells a mixed story for Vtech Holdings. The stock has a 30 day share price return of 5.33% but is still down 15.60% year to date. The 3 year total shareholder return of 46.07% points to much stronger long run progress as investors reassess the low P/E and the risks around its global expansion and manufacturing shift.
Compare Vtech Holdings' low P/E setup with a curated 200 high quality undervalued stocks list that is also being priced cautiously despite solid fundamentals.
Bulls point to Vtech Holdings' low P/E and solid 3 year return, while bears flag execution risk in its global expansion and manufacturing shift. Which case does the current valuation actually support next?
Most Popular Narrative: 18% Undervalued
Vtech Holdings last closed at HK$51.95, while the most followed narrative pegs fair value at about HK$63.55. This indicates that the gap between price and implied worth is not trivial and hinges on how credible its global restructuring story really is.
Accelerated relocation and expansion of manufacturing capacity outside China (Malaysia, Mexico, Germany) is expected to structurally reduce exposure to tariffs, improve supply chain resilience, and optimize capacity utilization, positioning VTech to defend or even expand margins despite ongoing global trade uncertainties.
See why 4 investors see Vtech Holdings as 18% undervalued.
Result: Fair Value of HK$63.55 (UNDERVALUED)
Still, tariffs that disrupt Vtech Holdings' factory relocation, or a faster shift away from traditional toys and cordless phones, could quickly weaken that undervaluation story.
Find out about the key risks to this Vtech Holdings narrative.
Another View: What Vtech Holdings' P/E Is Really Saying
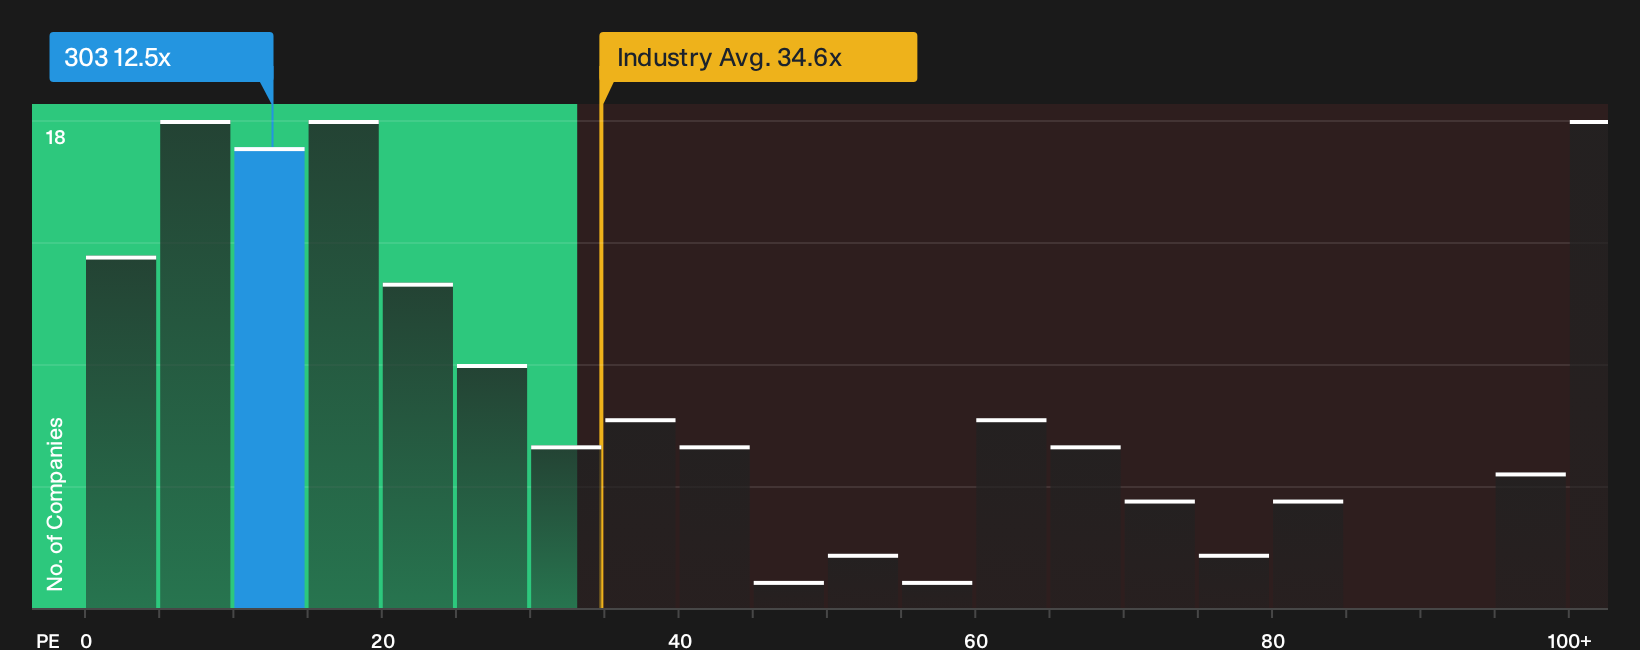
That 18% gap between Vtech Holdings' share price and the HK$63.55 fair value narrative leans on future assumptions. The current P/E of 12.5x looks cheap next to Asia communications peers at 34.6x, yet the fair ratio of 7.7x implies the stock might already be priced quite generously.
If the market drifts closer to that fair ratio rather than peer levels, valuation risk tilts the other way for anyone relying only on the low headline P/E. The real question is whether Vtech's global restructuring and product mix are strong enough to justify staying above that 7.7x anchor.
To see what the numbers say about this price in more detail, investors can review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Vtech Holdings is clearly divided. This is exactly why it pays to move quickly, test the numbers yourself, and weigh both sides of the story using the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Vtech Holdings?
If Vtech Holdings has you thinking harder about value and risk, do not stop at a single ticker. Broader research can reveal alternatives that suit your goals.
- Target potential value outliers by scanning a curated 200 high quality undervalued stocks that highlights businesses with solid fundamentals priced with caution.
- Prioritise resilience by reviewing a 231 resilient stocks with low risk scores that focuses on companies with more measured risk profiles.
- Hunt for under-the-radar opportunities through a 613 high quality undiscovered gems that surfaces quality stocks many investors may be ignoring.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com