


- Cronos Group recently reinstated its limited-edition Caramel Green Apple SOURZ by Spinach edibles and Sweet Green Apple 1g vape, expanding these seasonal products into the SOURZ Fully Blasted 10-pack and the Spinach vape line in Canada.
- The return of a flavor that has already gained traction within Cronos Group’s top-selling edible multipack and leading vape brand highlights how product variety and format choices can influence demand for higher-margin cannabis categories.
- This article examines how Cronos Group's broader investment narrative is shaped by the Caramel Green Apple product relaunch.
Scan how Cronos Group’s limited-edition flavor strategy compares with other cannabis plays by reviewing a curated group of 10 high quality undiscovered gems that are building brands with strong fundamentals.
Cronos Group Investment Narrative Recap
For Cronos Group to make sense in a portfolio, you need to think the branded cannabis engine keeps building, with GrowCo capacity, international medical channels, and higher margin vapes and edibles doing the heavy lifting. The Caramel Green Apple return reinforces that thesis thematically, but on its own it does not materially change the near term setup.
The key near term swing factor is still execution on scaling supply and controlling operating costs so that profitability holds up if pricing tightens. The biggest risk remains any disruption to cultivation ramp or regulatory changes in core markets like Canada and Israel that could limit access or pressure margins.
Among the recent context points, the focus on expanded access to international medical cannabis markets is most relevant here. If Cronos Group can pair sticky, seasonal Canadian brands like SOURZ and Spinach vapes with distribution into places such as Israel, Germany, or Switzerland, the mix could lean further toward higher priced channels.
That said, this opportunity sits beside real execution risk. Delays in GrowCo capacity, higher compliance costs, or slower medical patient onboarding could all blunt the benefit. The green apple seasonal run is a small operational proof point. The more significant catalyst is still turning that broader international and premium product strategy into durable free cash flow.
Cronos Group Consensus Set Up Behind The Green Apple Relaunch
Cronos Group's narrative projects $316.7 million revenue and $28.7 million earnings by 2029. This assumes 20.9% yearly revenue growth and an earnings decline of $41.3 million from $70.0 million today.
The limited Caramel Green Apple run slots into a much bigger consensus story around Cronos Group. Analysts are effectively pricing in a branded cannabis platform that can sustain 20.9% annual top line expansion while accepting far thinner profitability than today. The target model ties higher volumes and broader distribution to lower margins, not richer ones.
Earnings forecasts make that clear. Profit today of $70.0 million is expected to step down to $28.7 million by 2029, even as revenue is projected to reach $316.7 million. Margin compression from 39.1% to 9.1% is doing a lot of the work in that bridge, which means efficiency and mix become as important as simple sales growth.
Valuation expectations ask a lot as well. To line up with the consensus price target, the stock would need to trade on a P/E of 50.9x those 2029 earnings, compared with 17.9x today and 12.4x for the broader Canadian pharmaceuticals group cited in the report. That gap implies investors would be paying a premium multiple for a business where headline profitability is forecast to shrink rather than rise.
The Caramel Green Apple comeback matters inside that framework because it points to how Cronos Group might try to square those numbers. Seasonal flavors, multipacks and vapes are higher margin categories today, so every successful flavor drop nudges the mix toward products that support the earnings line, even if the consensus still anticipates margin pressure overall. The more that SOURZ and Spinach keep consumers loyal across formats, the easier it becomes to defend premium pricing inside a crowded cannabis shelf.
Revenue assumptions in the analyst model lean on more than Canadian edibles and vapes. GrowCo capacity, medical channels in markets like Israel, and potential exposure to places such as Germany or Switzerland all feed into that $316.7 million revenue marker. The Caramel Green Apple relaunch is a small test of whether Cronos Group can build repeatable, exportable brands that show up on those international shelves when regulations allow.
There is a tension baked into the forecasts. Analysts expect revenue to climb at a healthy double digit rate while profit margins compress sharply and the stock moves to a much richer earnings multiple. For readers tracking the Caramel Green Apple cycle, the key question is whether repeated, high engagement product launches can soften that margin squeeze or whether competitive and regulatory pressures keep profitability closer to the consensus path.
Share count expectations add another wrinkle. Analysts assume the number of shares outstanding will decline by 3.78% a year over the next three years. If buybacks continue and brand launches like Caramel Green Apple support cash generation rather than drain it, per share metrics could look better than headline earnings trends suggest.
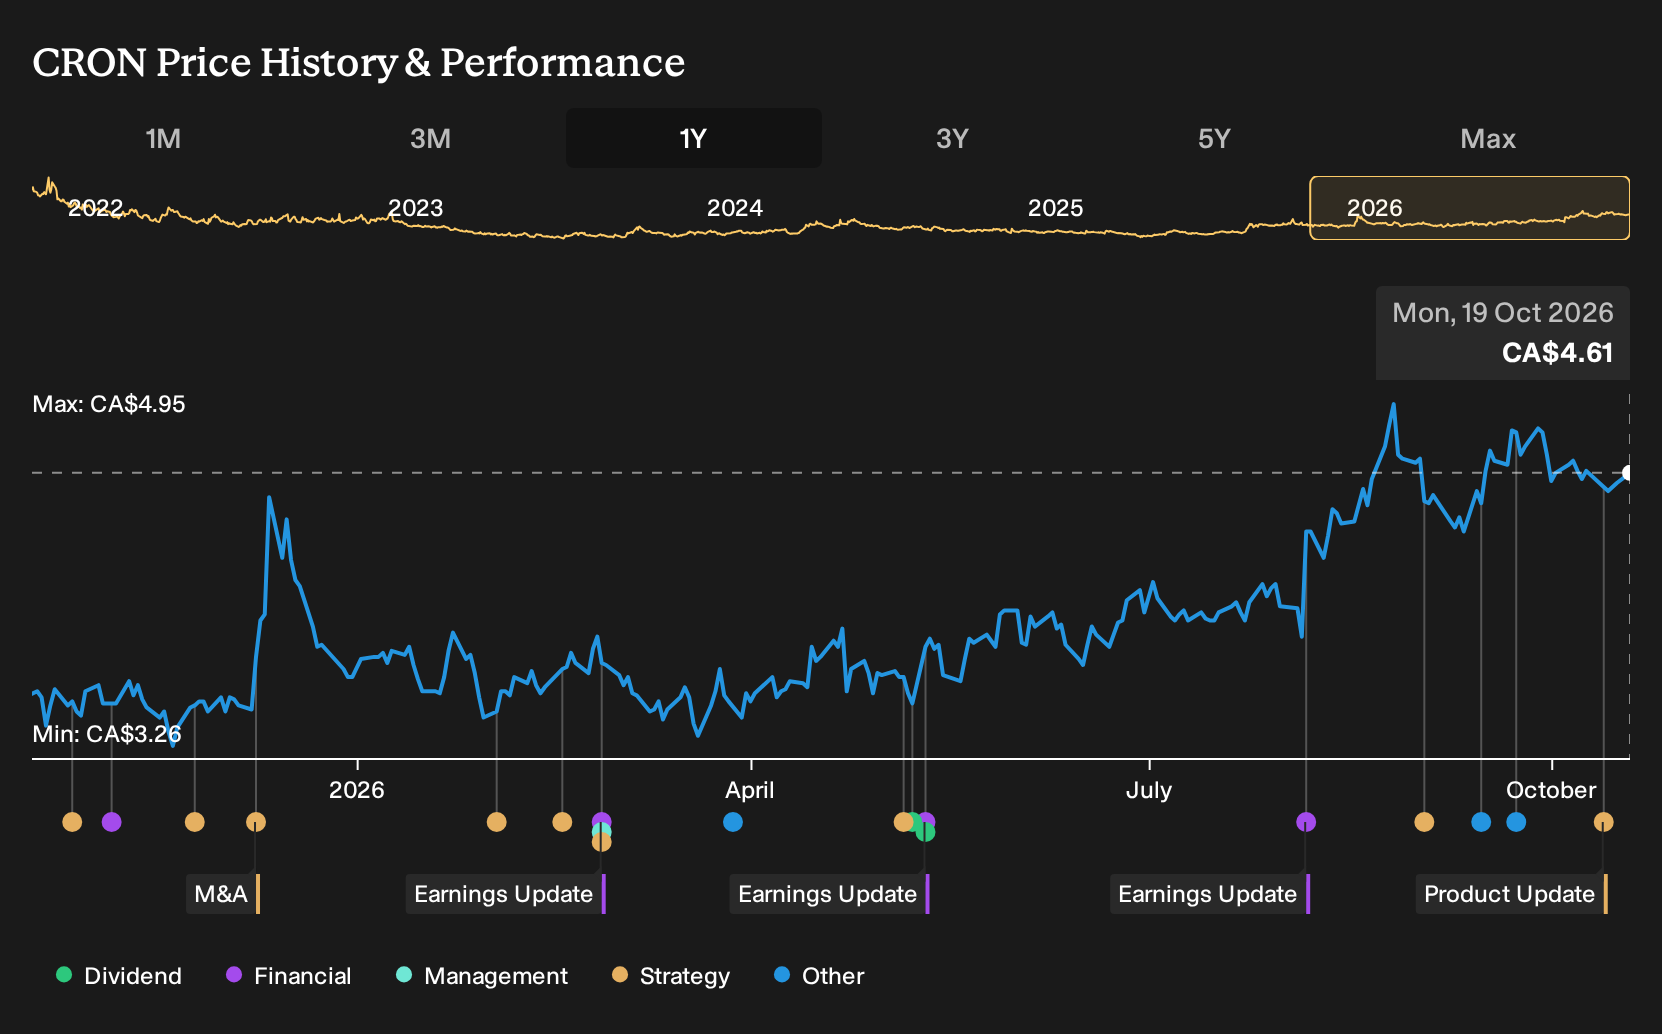
Against that backdrop, the analyst price target of CA$5.24, set against a current share price of CA$4.81, implies only an 8.2% uplift in the report. That narrow gap signals that, on average, the covering analysts view Cronos Group as roughly in line with their assumptions rather than deeply mispriced. For anyone weighing the Caramel Green Apple story, the real work lies in deciding whether those revenue, margin and P/E expectations feel conservative, aggressive, or about right given how the cannabis market has evolved by late 2026.
Discover why Cronos Group's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You also need to weigh a very different angle. The most bearish analysts worry that tighter global cannabis rules could cap Cronos Group’s addressable market. This is why they only penciled in $182.7 million of revenue and $64.4 million of earnings by 2029 before this Caramel Green Apple news. Views clearly span a wide range, so treat this launch as a fresh data point and explore both the upbeat and cautious forecasts for yourself.
Explore 3 other Cronos Group fair value estimates, including one that suggests there could be as much as 25% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cronos Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cronos Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cronos Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cronos Group?
If the Caramel Green Apple relaunch has you rethinking where Cronos Group fits in your portfolio, it can help to compare it with other businesses that have very different risk and return profiles. The Simply Wall St Screener gives you a quick way to line up Cronos Group against other stocks that match the kind of balance sheet strength, income potential, or upside you want to focus on next.
- If capital preservation comes first for you, scan 8 resilient stocks with low risk scores that score well on stability and can help anchor a more volatile basket of cannabis and growth stocks.
- For readers hunting for mispriced opportunities, review 5 high quality undervalued stocks where solid fundamentals and attractive valuations line up in the same place.
- If dependable income is a priority, sort through 3 dividend fortresses that combine higher yields with balance sheet strength to support regular payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com