


- Fiserv has rolled out its Commerce Hub platform globally and added Klarna to the offering, giving merchants a single connection to local payment methods, acquiring services and flexible pay over time options across online and in store channels.
- The combination of a unified cross border payments hub and Klarna integration points to Fiserv focusing more on omnichannel demand and value added services, which are relevant for recurring software style revenue and operating leverage over time.
- We will review how Fiserv's investment narrative is affected by Commerce Hub's global reach and Klarna integration across channels.
Scan how Fiserv is leaning into payment infrastructure, then size up other processors and platforms through our hand picked 55 AI infrastructure stocks, which are building the pipes behind global digital commerce.
Fiserv Investment Narrative Recap
To own Fiserv, you need to believe that recurring payment and banking software can offset recent pressure in Merchant Solutions and Financial Solutions, and that execution on One Fiserv and Project Elevate actually shows up in margins. The big near term swing factor is whether revenue stabilises after recent quarterly declines or whether weakness lingers into new guidance cuts.
The main risk remains that softer client demand and slower Clover growth keep organic revenue flat or lower, which would make cost savings harder to realise cleanly. Commerce Hub’s global launch and the Klarna tie up support the long term platform story, but they do not materially change the near term revenue and guidance overhang yet.
The Fulton Bank roll out of CashFlow Central is the clearest operational link to the current Commerce Hub story. Both speak to Fiserv trying to deepen its role as infrastructure behind client cash flow and payments, whether that is for a stadium, a merchant or a regional bank. You are seeing the same playbook across different customer types.
CashFlow Central also connects directly to the catalysts analysts care about, such as higher value software usage, better data, and stickier Financial Solutions relationships. The risk is complexity. Each new integrated hub and venue deployment adds moving parts, which can amplify execution issues if client onboarding slows or if operating costs do not track the plan under Project Elevate.
Fiserv's narrative projects US$21.3b revenue and US$3.1b earnings by 2029. This implies fairly flat revenue over the next few years and an earnings increase of about US$0.3b from US$2.8b today.
Uncover how Fiserv's fair value indicates a 24% potential upside to its current price before the market closes that gap.
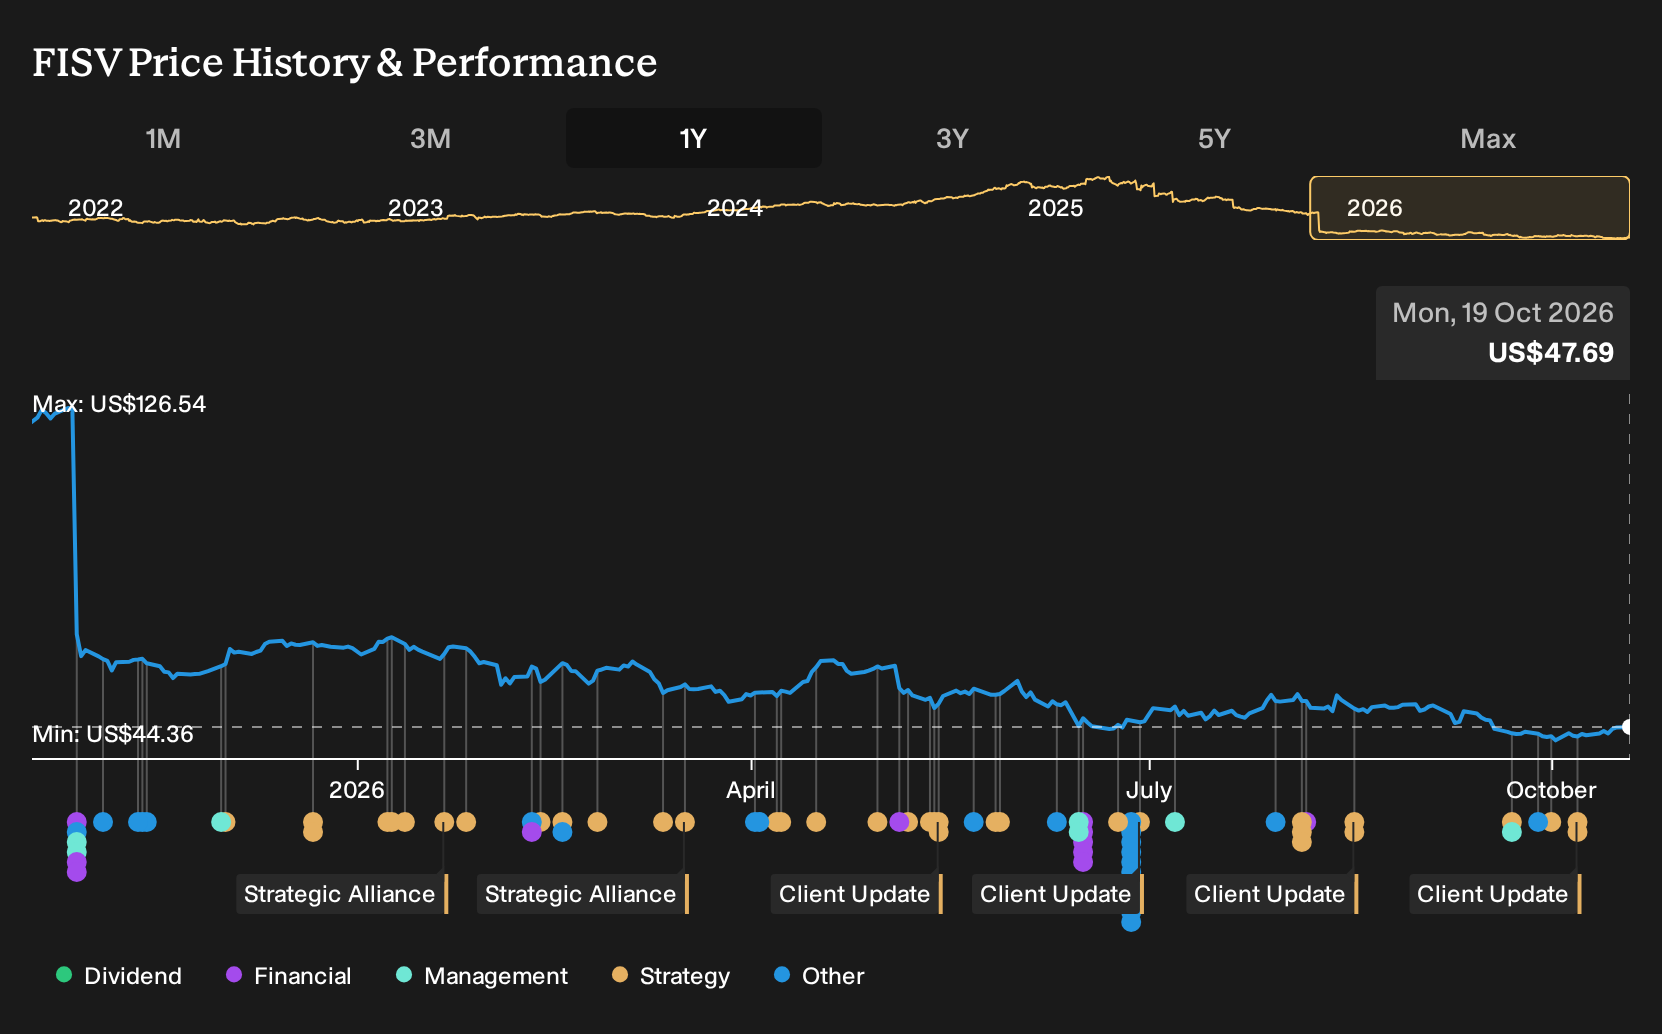
Exploring Other Perspectives
One alternate view zooms in on margin pressure instead of Commerce Hub’s upside. The most cautious Fiserv analysts were modelling revenue of about US$20.0b and earnings near US$2.2b by 2029, well below consensus. That paints a tougher story on pricing and competition, which fresh deals like Fulton and Hard Rock might eventually reshape.
Explore 13 other Fiserv fair value estimates, including one that suggests there could be as much as 16% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Fiserv research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fiserv. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fiserv's overall financial health at a glance.
Looking for more Fiserv-sized investment ideas?
If the Fiserv story has sharpened your thinking about payment infrastructure and recurring software, you can apply the same lens to a wider watchlist by using targeted screens on Simply Wall St.
- For investors who want quality and a margin of safety, filter for companies that currently look attractively priced with 35 high quality undervalued stocks.
- If resilience matters most to you, focus on businesses with stronger balance sheets and cleaner fundamentals through the list of solid balance sheet and fundamentals (25 results).
- When you are hunting for under the radar opportunities, scan the 20 high quality undiscovered gems that pair quieter profiles with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com