


- Wintrust Financial reported third quarter 2026 net interest income of US$621.6 million and net income of US$239.05 million, with basic earnings per share from continuing operations of US$3.42.
- For the first nine months of 2026, Wintrust Financial’s net interest income reached US$1.798 billion and net income was US$700.14 million, indicating a larger earnings base across the year to date.
- We will now examine how Wintrust Financial’s investment narrative aligns with this quarter’s higher net interest income and earnings performance.
Wintrust Financial Investment Narrative Recap
For a shareholder in Wintrust Financial, the core belief is that a Midwest focused lender with community banking roots, specialty finance and wealth management can keep compounding earnings through a growing base of loans and deposits. The latest quarter, with US$621.6 million in net interest income and US$239.05 million in net income, supports that operating thesis without radically changing it.
The key short term swing factor is how funding costs and loan yields play off each other as competition in commercial and commercial real estate lending pressures pricing. The biggest risk still sits in credit quality and exposure to commercial real estate and office loans. Any deterioration from the currently reported stable environment could quickly affect provisions and reported profit.
The most relevant update is the third quarter 2026 earnings release itself. Wintrust Financial reported higher net interest income versus the same period a year earlier, along with higher net income and basic earnings per share from continuing operations of US$3.42 compared to US$2.82. Diluted earnings per share from continuing operations reached US$3.37 compared to US$2.78.
Over the first nine months of 2026, the bank reported US$1.798 billion in net interest income and US$700.14 million in net income. For you, the link to catalysts is straightforward. A larger earnings base gives management more room to keep investing in technology, digital banking and branch expansion, while any pressure from loan repricing, premium finance yields or higher expenses remains a live operational risk to watch each quarter.
Wintrust Financial's current analyst narrative points to revenues of US$3.5b and earnings of US$1.1b by 2029, built on an assumed 8.6% yearly revenue growth rate and an earnings increase of about US$252.1m from the US$847.9m of earnings today.
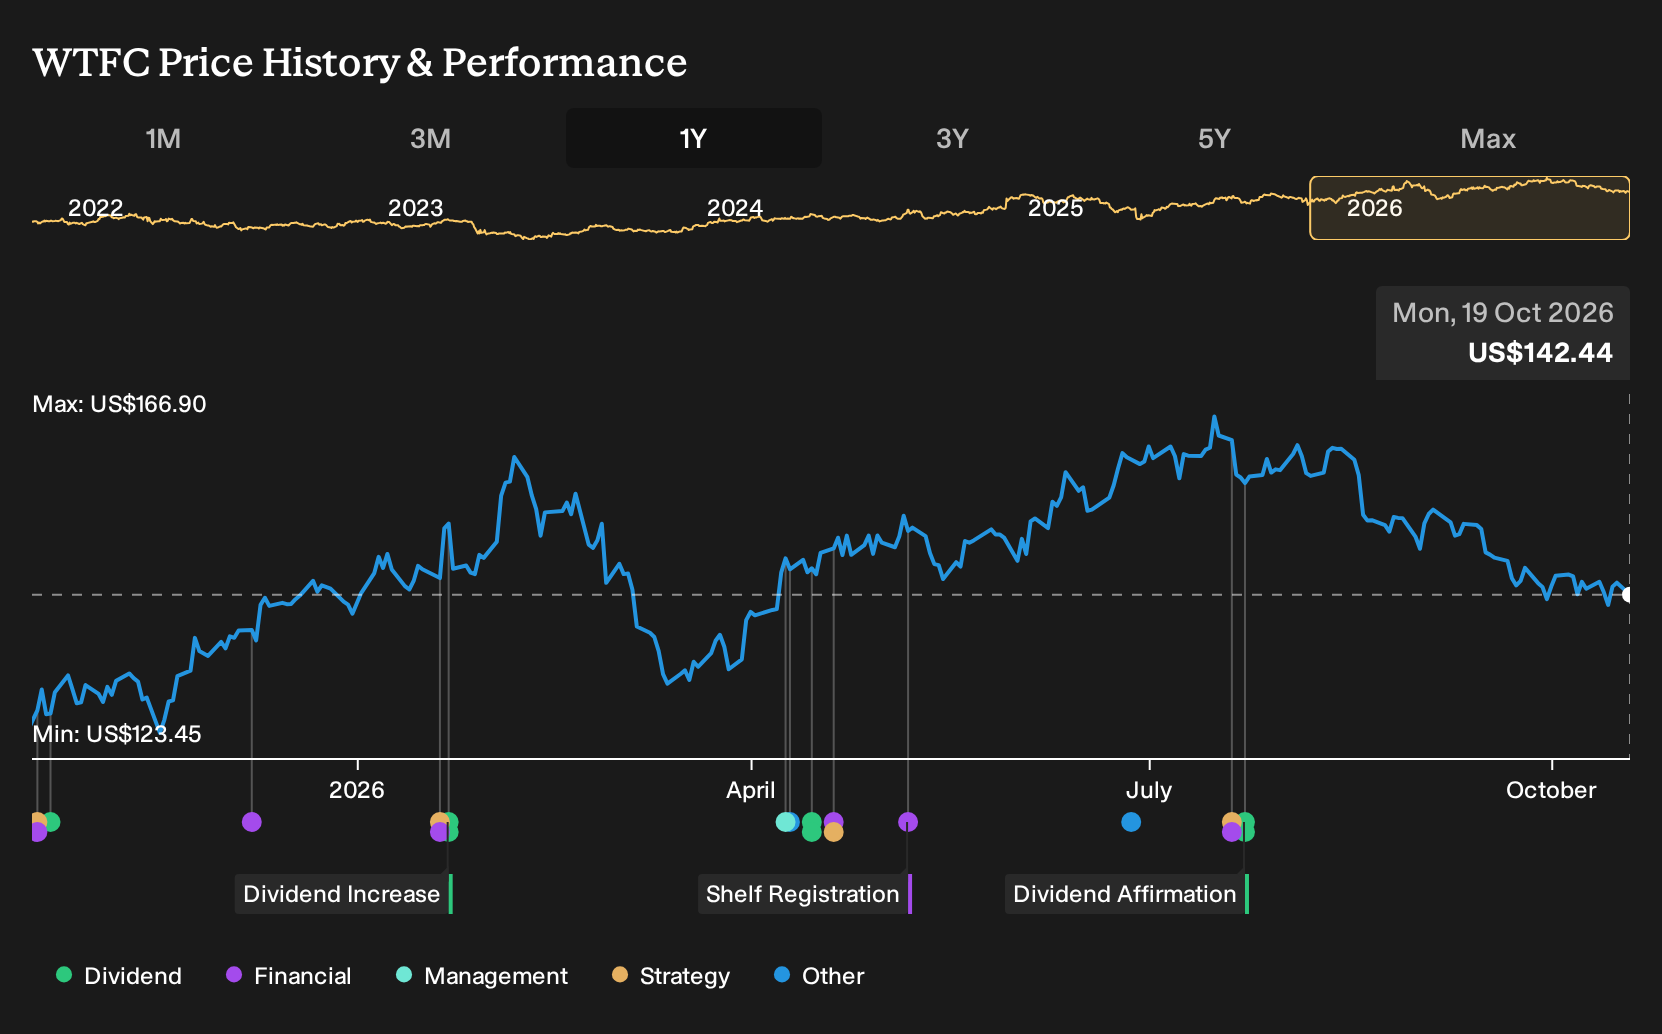
Uncover why Wintrust Financial's fair value indicates a 24% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$176 and US$230 per share, which hints at a wide valuation band even within a tiny sample. You are weighing those pre earnings views against risks around loan pricing, credit quality and tech spending. Expect opinions to differ and consider exploring several angles.
Explore another Wintrust Financial fair value estimate, including one that suggests it could be worth just $176.20!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Wintrust Financial research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Wintrust Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wintrust Financial's overall financial health at a glance.
Looking for more investment ideas beyond Wintrust Financial?
Once you have formed a view on Wintrust Financial, it can help to compare those conclusions with other companies that share similar qualities in earnings strength, balance sheet resilience or income potential. The Simply Wall St Screener is built for exactly that kind of side by side research.
- If capital preservation is high on your list, start with companies that pair measured risk profiles with consistent fundamentals by scanning 32 resilient stocks with low risk scores.
- For investors focused on quality at a reasonable price, look through businesses that combine solid cash generation with appealing valuations using the 35 high quality undervalued stocks.
- Income seekers can widen their watchlist by reviewing companies that offer robust yields with a focus on consistency through the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com