


- Qiagen recently rolled out new AI capabilities across its Ingenuity Pathway Analysis suite, including the IPA Investigator assistant and the QIAGEN Discovery Platform, to help researchers query complex biological and genomic data in natural language and automate parts of drug discovery workflows while keeping the underlying scientific evidence visible.
- The focus on combining AI with curated biological and clinical knowledge suggests Qiagen is trying to deepen the value of its bioinformatics tools rather than only prioritize faster throughput, which matters for how sticky these platforms may become in real world research settings.
- We will look at how Qiagen's investment narrative is shaped by this AI driven expansion of its genomic and bioinformatics platforms.
Find peers pursuing similar AI driven research tools by scanning the curated 33 healthcare AI stocks, which may be building the next wave of data heavy healthcare platforms alongside Qiagen.
Qiagen Investment Narrative Recap
To own Qiagen, you need to believe its mix of molecular diagnostics, automation and bioinformatics can continue generating mid single digit revenue growth while funding ongoing product work. The near term swing factor still looks tied to uptake of platforms like QIAstat Dx and the broader consumables base, against a backdrop where life science funding remains uneven.
The biggest operational risk remains weak academic and government budgets that could leave higher margin instruments underutilized and slow adoption of new systems. The fresh AI features inside Qiagen Digital Insights appear incremental to this near term setup, helpful for strengthening the bioinformatics story but not a clear, immediate catalyst on their own.
Among recent developments, the earlier expansion of automated sample preparation systems such as QIAsymphony Connect, QIAsprint Connect and QIAmini looks most relevant to this AI rollout. Management flagged about US$20m of extra revenue in the second half of 2026 tied to these platforms, which offers a tangible reference point for how new technologies can appear in reported results.
Layering IPA Investigator and the QIAGEN Discovery Platform on top of that automation push creates a clearer workflow narrative, from sample preparation into analysis and decision support. The operational question is whether customers under funding pressure commit to this fuller stack, because slower instrument upgrades or cautious software budgets would limit how much the AI driven tools contribute to utilization and margins.
Qiagen's analyst narrative points to revenues of US$2.5b and earnings of US$561.2m by 2029, based on forecast top line growth of 6.0% per year and an earnings increase of about US$151.9m from current earnings of US$409.3m.
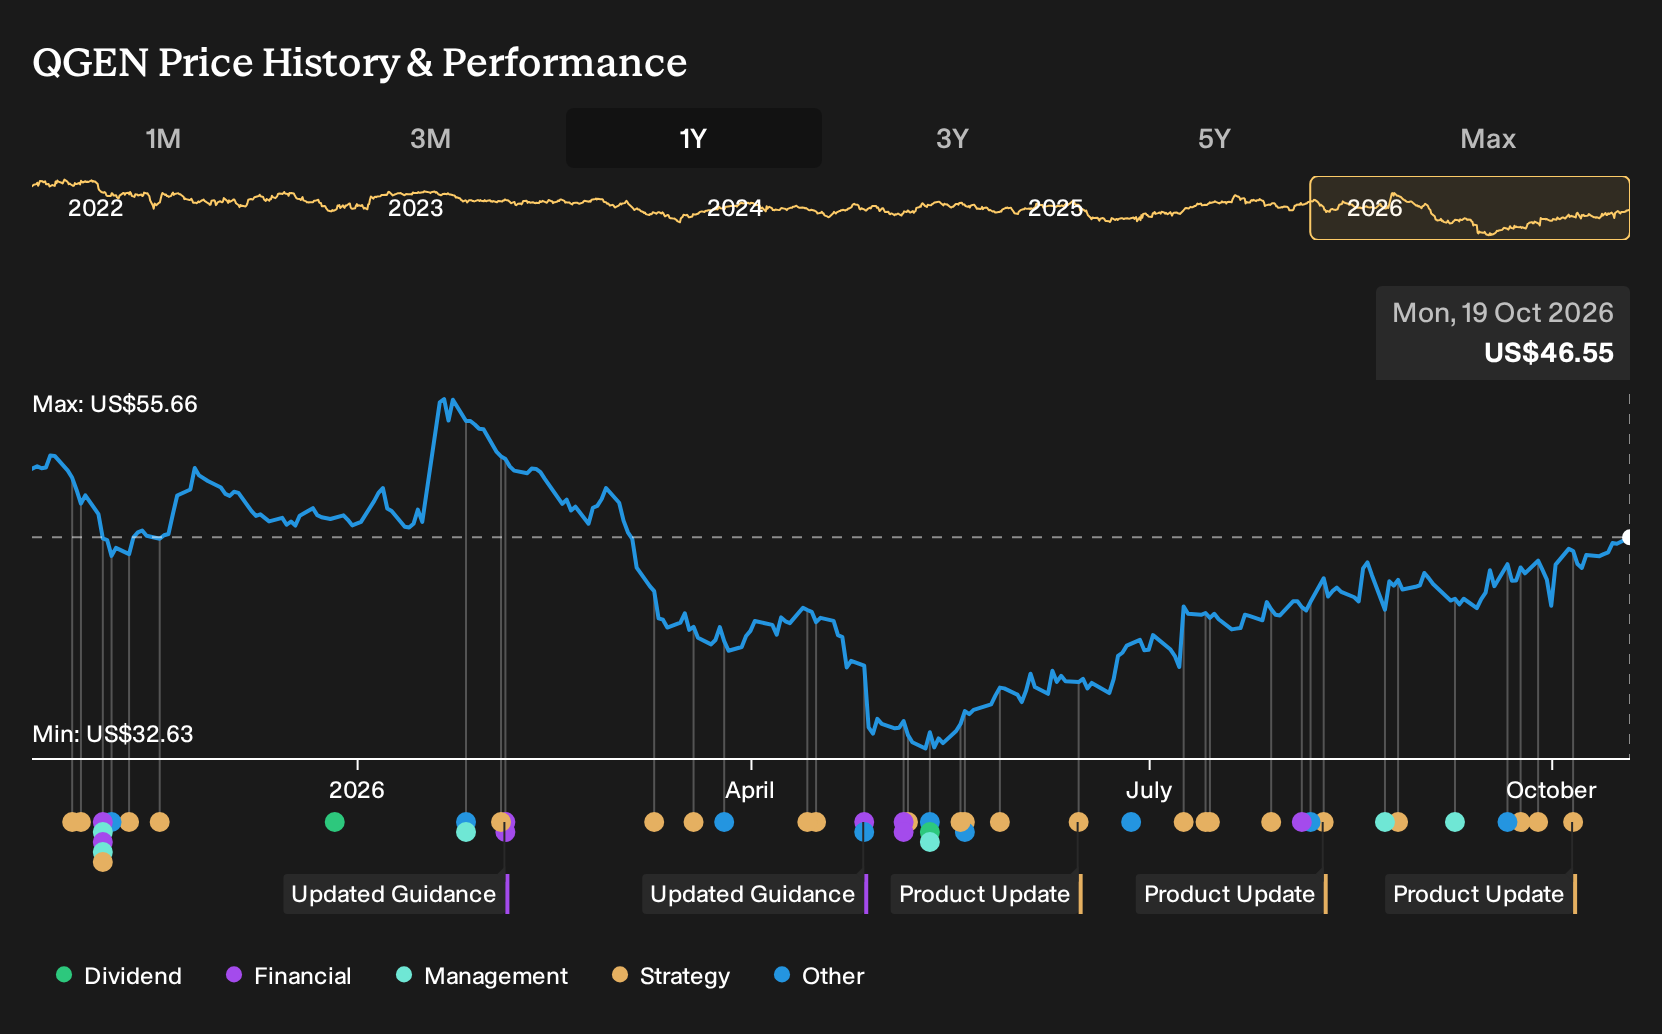
Uncover how Qiagen's fair value indicates a 3% potential upside to its current price before the valuation gap closes.
Exploring Other Perspectives
One alternate angle assigns more weight to QuantiFERON as a potential swing factor than to Qiagen’s new AI launch. The most optimistic analysts were already forecasting revenues of about US$2.5b and earnings of roughly US$588.0m by 2029, compared with today’s US$409.3m baseline. You can treat this AI rollout as a fresh reason to revisit those competing stories.
Explore 4 other Qiagen fair value estimates, including one that suggests as much as 207174% upside from the current price!
The Verdict Is Yours
Don’t just follow the ticker. Dig into the data and build a conviction that’s truly your own.
- A great starting point for your Qiagen research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Qiagen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qiagen’s overall financial health at a glance.
Looking For More Investment Ideas Beyond Qiagen?
Once you have a handle on Qiagen, it can help to compare its setup with other companies that share similar qualities or very different risk profiles. The Simply Wall St Screener lets you line up those contrasts in a structured way rather than relying on headlines or hunches.
- If you care most about quality at a sensible entry point, scan a focused set of 35 high quality undervalued stocks that pair stronger fundamentals with more modest pricing.
- For readers who put balance sheet strength first, filter for a list of solid balance sheet and fundamentals (25 results) that may better handle funding swings or tougher credit markets.
- When you want to widen the research funnel and spot less crowded opportunities, run a search across 20 high quality undiscovered gems that could complement a position in Qiagen.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com