


Interest rate decisions are back in the spotlight, with the Fed, PCE inflation data and even the Bank of Japan all helping to reset how investors think about income and risk. Cash now pays something again, so any dividend stock has to justify its place. This article explores three high-quality dividend stocks exposed to these macro shifts and shows where income investors might want to lean in or step back.
The three stocks highlighted next are a small sample, with the full screen surfacing 10 more dividend payers with similarly detailed stories that are not covered here.
If you want to go straight to the source and identify, compare, and analyze the highest-conviction income ideas for your own watchlist, head into the High-Quality Dividend and Income Stocks screener.
Marzetti (MZTI)
Marzetti gives the screener a classic consumer staples anchor, with branded sauces, dressings and frozen breads that can help support reliable dividends when income investors are weighing steady cash returns against higher bond and cash rates.
Marzetti generates about US$1.0b from Retail products such as New York Bakery breads and Marzetti salad dressings and roughly US$927 million from Foodservice sauces and frozen breads for restaurant chains, and the group is valued at about US$2.9b.
While Marzetti is investing in modern manufacturing assets, SAP S/4HANA systems and supply chain productivity programs, the planned closure of facilities and impairment charges highlight execution risk that could offset efficiency gains and restrict the pace of gross margin and operating margin improvement.
What happens to Marzetti’s income appeal ultimately hinges on how one unseen pressure shapes the balance between pricing power and volume resilience.
That pressure point is exactly where income potential and execution risk collide, and the full narrative for Marzetti shows how Marzetti could turn today’s reset into a longer term dividend story.

VICI Properties (VICI)
VICI Properties is built for income investors, with long-term triple-net leases on casinos and resorts that line up neatly with a screener focused on reliable cash distributions and balance-sheet resilience when rates stay higher for longer.
VICI Properties is a US$26.0b experiential REIT that earns about US$4.1b from real estate investment activities in the United States, collecting rent from gaming, hospitality and leisure assets such as Caesars Palace and MGM Grand on the Las Vegas Strip.
Given the present uncertainty and unrest in the United States and its immigration and tourism policies, growth at VICI may be penalized during the next couple of years. The impact may be more pronounced in the next year, and then taper to a level slightly above the broader economy’s growth rate after that.
What really matters is whether one underappreciated funding pressure tightens just as those long leases and high cash payout expectations are tested.
When that funding squeeze hits, the full narrative for VICI Properties shows how VICI Properties could turn lease length and payout pressure into an accelerating income story for patient holders.

John B. Sanfilippo & Son (JBSS)
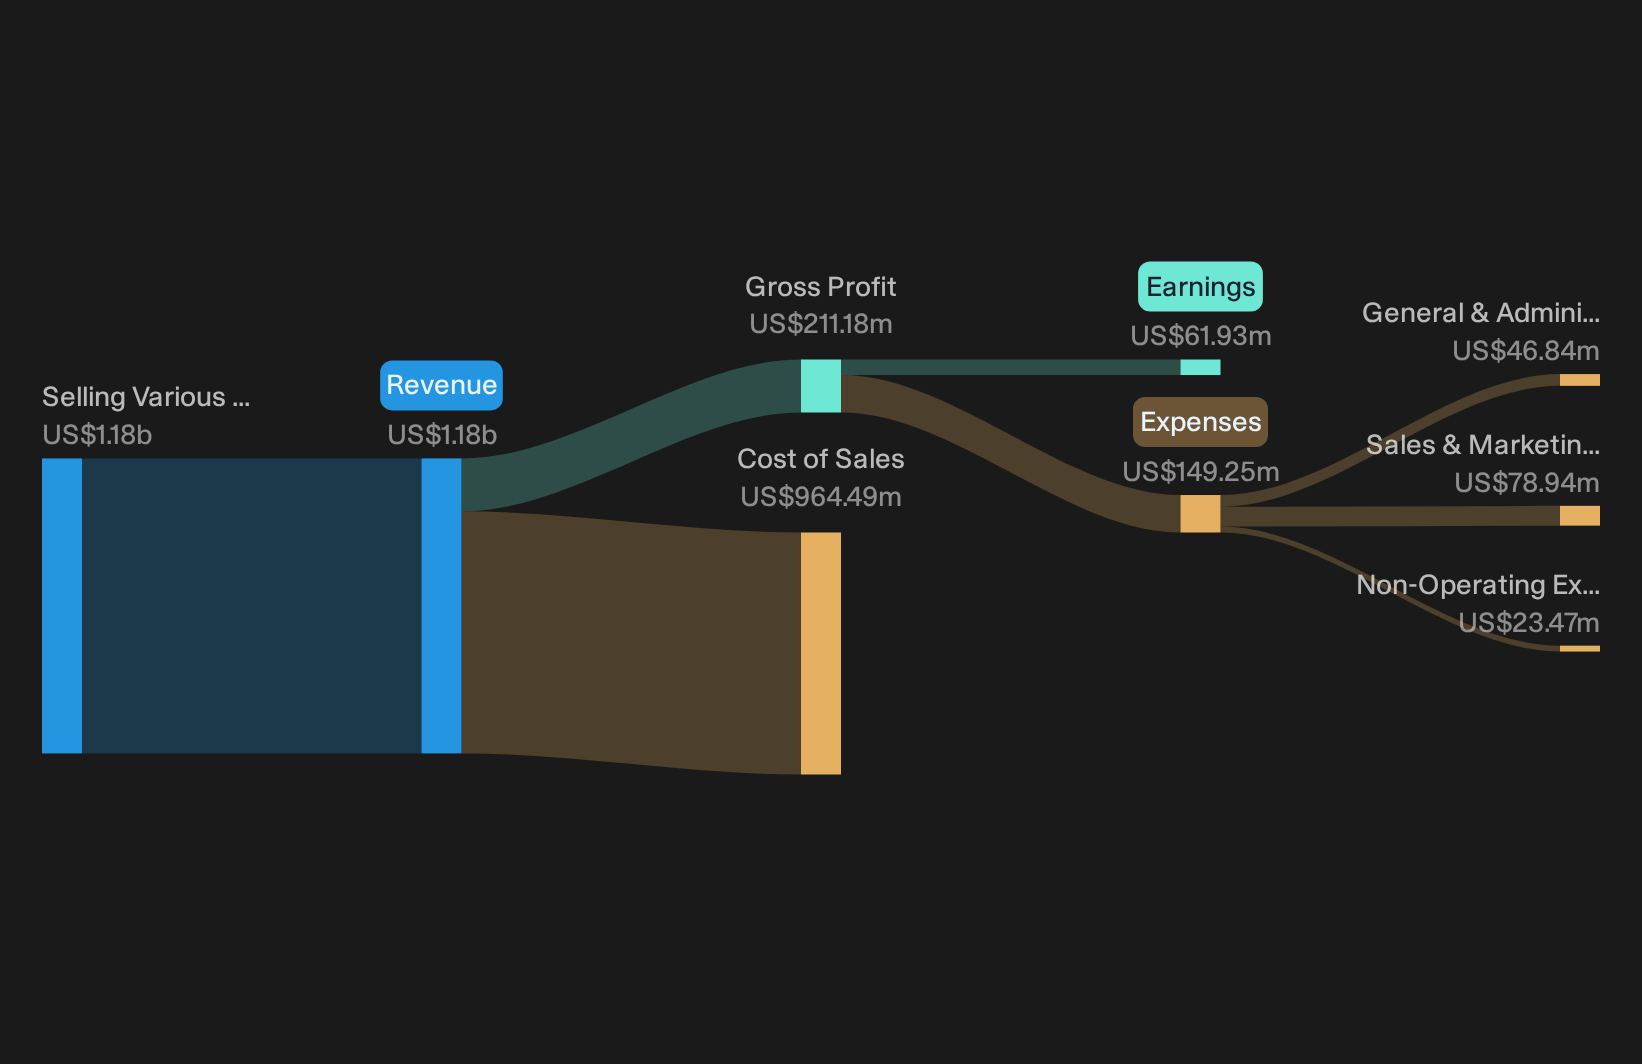
John B. Sanfilippo & Son is a US$781 million nut and snack producer that fits this dividend-focused screener as a cash-generative staple business, earning about US$1.2b from selling various nut, nut-related products and bars across branded, private label and ingredient channels.
For income investors looking beyond utilities and pipelines, John B. Sanfilippo & Son offers a different kind of cash engine, tied to everyday snacking and ingredient demand rather than rate-sensitive assets. This context helps explain why its next phase of growth matters.
New snack and protein bar production lines in the expanded Illinois footprint are scheduled to come online by year end, which is expected to position JBSS to capture growth in better for you, high protein and energy bar segments and to support higher margin earnings as capacity utilization scales.
What ultimately shapes the income story is how one unresolved cost and pricing pressure plays out against those higher value products.
That cost equation is exactly what the full narrative for John B. Sanfilippo & Son unpacks, showing how Marzetti-style staples and new bar capacity could accelerate or stall JBSS as an income engine.
Seeking Fresh Alternatives Beyond Dividends
New ideas move first, then prices follow. Some of the sharpest breakouts often come from lists that stay under the radar for now, so do not delay, get in early.
- Track where the next wave of AI momentum might be forming by scanning hand-picked 38 profitable AI stocks that aren't just burning cash curated for revenue, discipline and staying power, while enthusiasm is still building.
- Front run potential supply pinch points by reviewing a curated 32 best rare earth metal stocks. These specialist miners may draw increased attention when conditions change.
- Position ahead of possible grid upgrade spending by zeroing in on rigorously filtered 42 power grid technology and infrastructure stocks, while valuations still reflect earlier demand assumptions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com