


Why QBE Insurance Group Is Back On Investors’ Radar
QBE Insurance Group (ASX:QBE) is drawing fresh attention after Castle Insurance shifted part of its underwriting portfolio away from the insurer, just as recent share performance reignites questions about valuation and returns.
Recent trading tells a story of renewed interest in QBE Insurance Group, with a 1 month share price return of 10.94% and a year to date share price gain of 30.99%. The 5 year total shareholder return of 164.30% points to momentum built over a longer stretch, even as portfolio changes like Castle Insurance’s move prompt investors to reassess how much of that performance reflects durable underwriting economics versus changing risk perceptions.
Compare QBE Insurance Group's run with a curated set of other insurers and compounders by scanning our 4 high quality undervalued stocks that currently pair valuation support with balance sheet strength.
QBE Insurance Group now trades above the A$24.94 analyst target while some intrinsic value work still points to a near 50% discount. Is the market right or are the valuation models closer to fair value?
Most Popular Narrative: 6% Overvalued
QBE Insurance Group last closed at A$25.95, a touch above the most followed fair value estimate of A$24.47 that is built on a 7.18% discount rate and analyst revenue and margin forecasts.
QBE's expanding presence and strong relationships in key global and emerging markets enable it to capitalize on increasing wealth and asset growth, driving sustainable premium and revenue growth through geographic and product diversification.
Heightened frequency and severity of natural catastrophes, coupled with growing customer risk aversion, are increasing demand for specialty and catastrophe coverage; QBE's balanced, diversified portfolio, prudent reinsurance strategy, and active mix management are expected to support premium growth and protect underwriting margins even as market conditions fluctuate.
See why 57 investors see QBE Insurance Group as 6% overvalued.
Result: Fair Value of A$24.47 (OVERVALUED)
Still, softening premium rate momentum and large loss volatility, including exposure to extreme weather events, could quickly challenge the current QBE Insurance Group fair value story.
Find out about the key risks to this QBE Insurance Group narrative.
Another Take On QBE Insurance Group’s Valuation
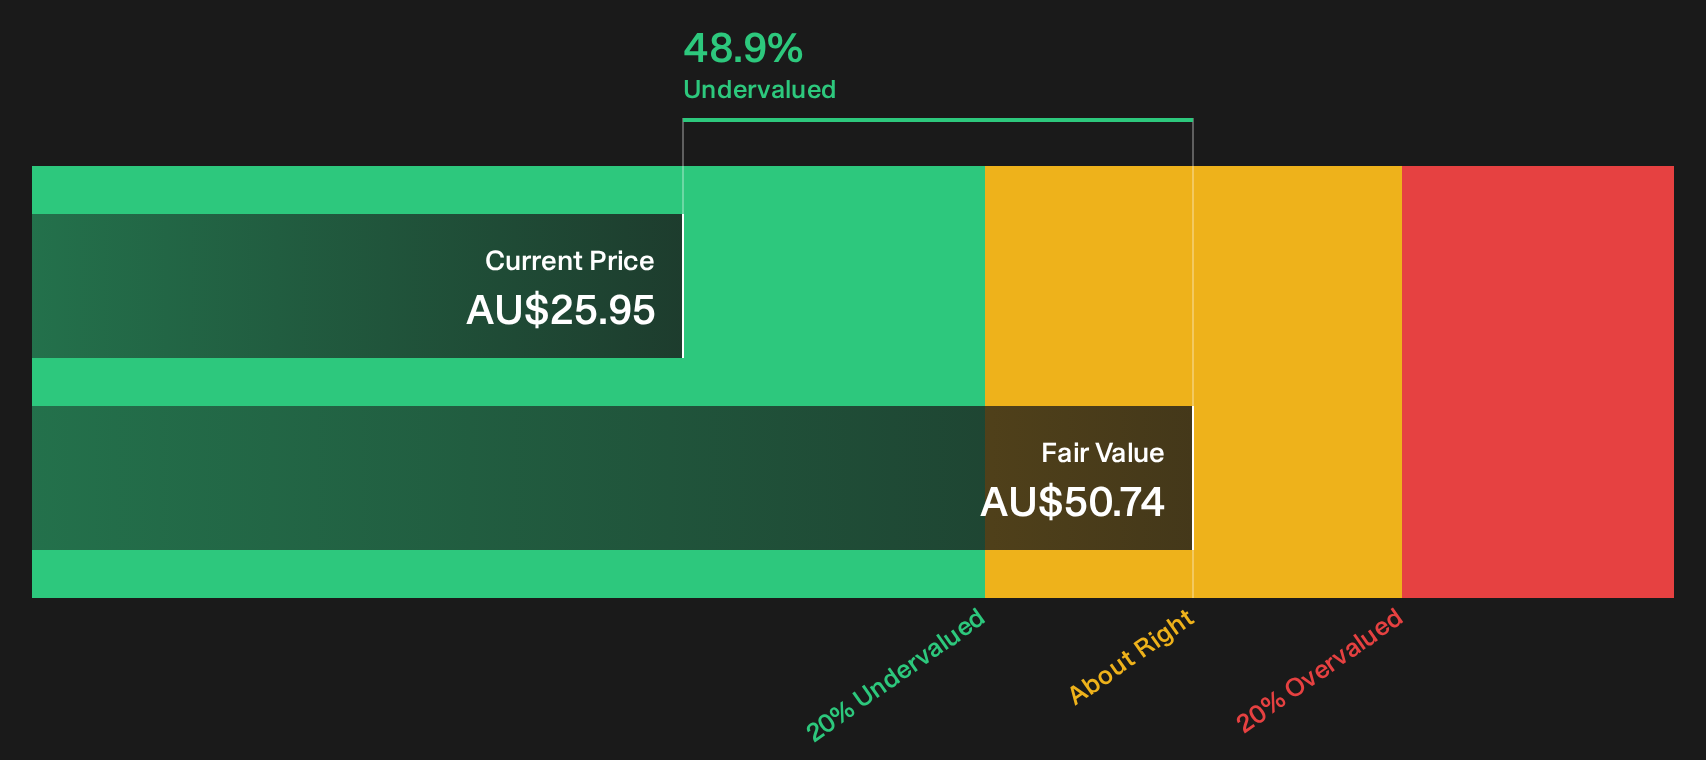
Analysts see QBE Insurance Group as 6% overvalued at A$25.95 versus their A$24.47 fair value, yet our DCF model points to a very different picture, with QBE trading at roughly a 49% discount to an intrinsic value of A$50.74. Which risk set do you trust more: consensus forecasts or cash flow maths?
To unpack how that gap emerges from the cash flow work, run through the SWS DCF model details in the latest report, then pressure test the assumptions against your own expectations for QBE Insurance Group.Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on QBE Insurance Group's value and risk profile so far. Use the data, move quickly, and weigh both the 2 key rewards and 1 important warning sign.
Ready For More Ideas Beyond QBE Insurance Group?
If QBE Insurance Group has you rethinking what value looks like today, do not stop here. Fresh ideas often sit just one screener away.
- Target reliable cash generators and let the yield work for you through the 5 dividend fortresses.
- Hunt for quality at a discount by scanning the 15 high quality undiscovered gems before the crowd pays attention.
- Prioritise resilience and sleep easier at night by filtering for the 6 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com