


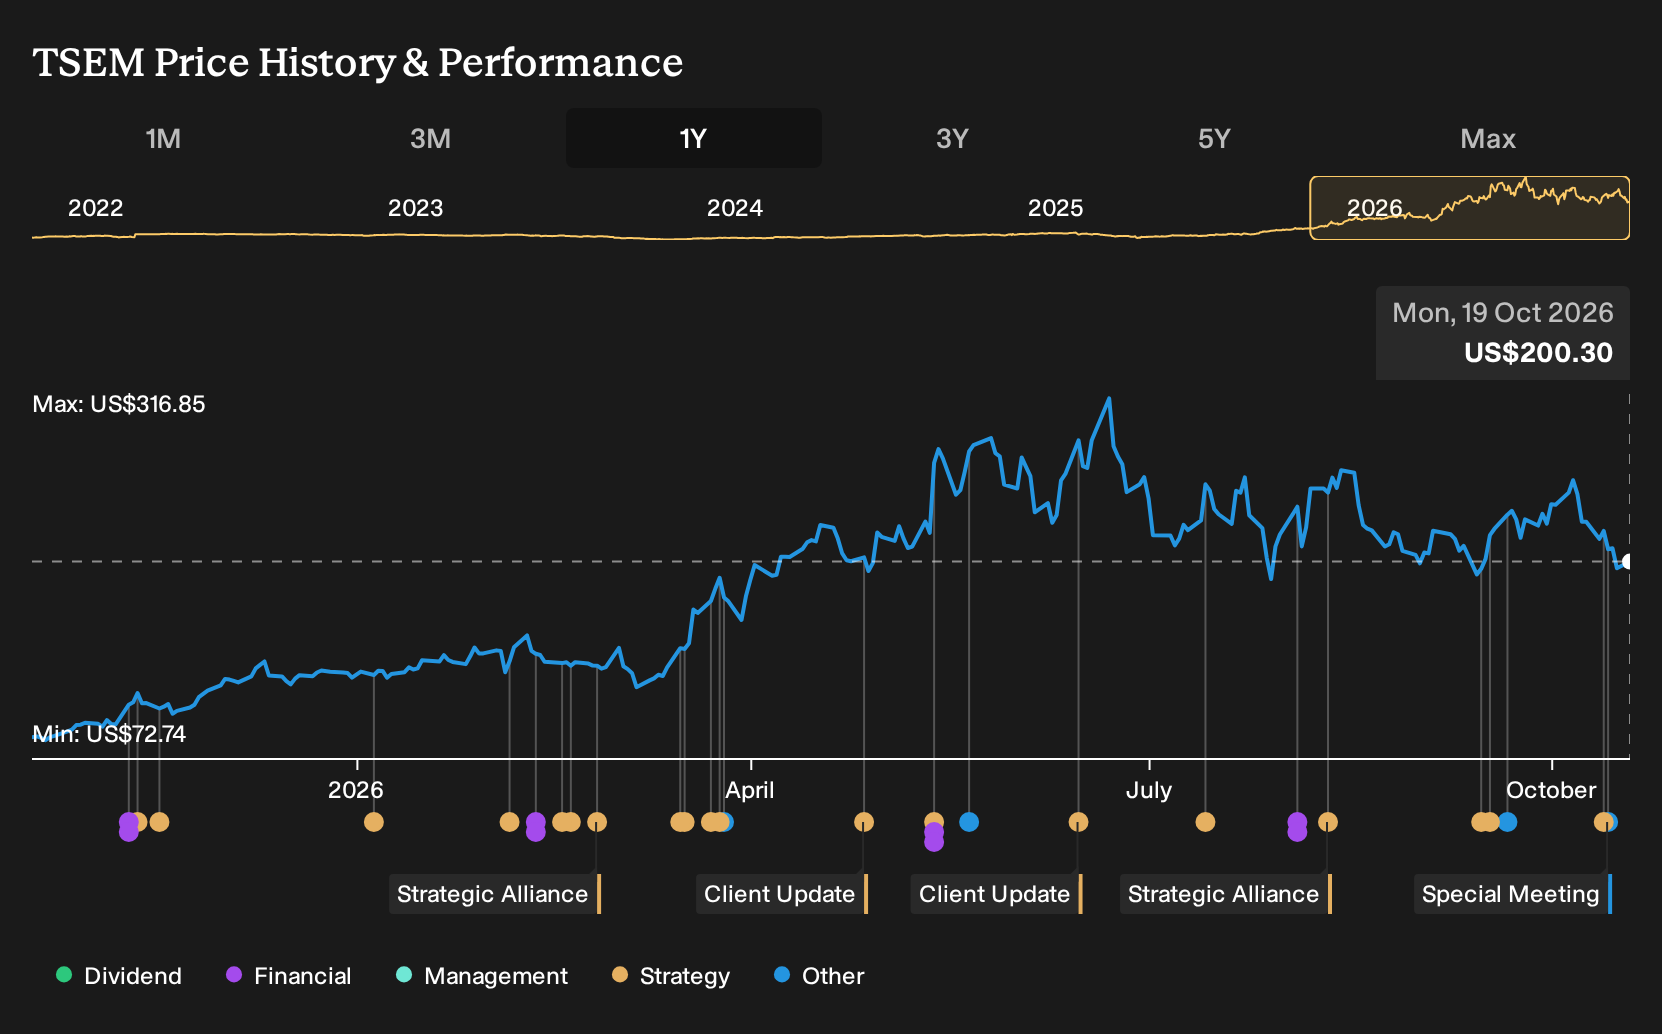
- In October 2026, Semtech announced an expanded multi year agreement with Tower Semiconductor to secure dedicated silicon germanium capacity across Tower’s fabs in the United States, Israel and Japan for AI data center optical interconnect components.
- The deal locks in long term SiGe production for Semtech and positions Tower Semiconductor’s geographically diversified fab network as a key supplier to AI data center optical interconnect programs.
- We will now look at how Tower Semiconductor’s investment narrative could be shaped by this dedicated SiGe capacity for AI interconnects.
Scan how Tower Semiconductor’s secured SiGe capacity fits into the broader AI buildout by reviewing a curated group of 55 AI infrastructure stocks powering data center connectivity and compute demand.
Tower Semiconductor Investment Narrative Recap
To own Tower Semiconductor, you need to be comfortable with a foundry that is spending heavily to align its fabs with silicon photonics, SiGe and 300mm RF demand tied to AI infrastructure. The main thesis is that contracted silicon photonics volumes and design wins eventually fill that expanded footprint and keep margins supported while this mix shift continues.
The Semtech capacity deal fits into that thesis by tying a long standing customer to Tower’s SiGe lines across three regions. It points to near term demand visibility but does not remove the main risk right now, which is underutilization if broader wafer demand or RF mobile and 300mm transitions lag those investment plans.
The Semtech announcement is closely linked to Tower Semiconductor’s roughly US$920m program to expand silicon photonics and SiGe capacity across existing 200mm and 300mm fabs, alongside the larger 300mm build in Japan. A dedicated multi year SiGe commitment from a key optical interconnect client connects to that capex plan in a very direct way.
For shareholders, the operational question is whether these contracted and reserved flows, including silicon photonics agreements and capacity reservation payments, are sufficient to keep new lines busy and support the margin mix that Tower is targeting. If wafer loading or RF and power migrations underperform while the stock still trades on a high P/E, valuation compression risk remains a central concern.
Tower Semiconductor's narrative projects US$4.2b revenue and US$1.3b earnings by 2029. This assumes 35.3% yearly revenue growth and an earnings increase of about US$1.0b from US$289.6m today.
Uncover how Tower Semiconductor's fair value indicates a 56% potential upside to its current price before that discount narrows.
Exploring Other Perspectives
Some of the most optimistic analysts see this Semtech capacity move through a different lens. You might focus on utilization risk, while their pre news models were already leaning into a Tower Semiconductor scenario with US$4.2b revenue and US$1.4b earnings by 2029. That kind of gap shows how widely opinions can differ and why fresh information like this agreement could eventually tilt those forecasts in new directions.
Explore 3 other Tower Semiconductor fair value estimates, including one that suggests as much as 56% potential increase from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on careful analysis and your own judgment.
- A great starting point for your Tower Semiconductor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tower Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Tower Semiconductor's overall financial health at a glance.
Looking for more Tower Semiconductor style ideas?
If the Tower Semiconductor story has you thinking about how to build a broader watchlist around quality, value and resilience, the Simply Wall St Screener can help you scan for companies that fit those themes in a structured way.
- For investors who want potential mispricing on their side, review a curated set of 35 high quality undervalued stocks that pair fundamentals with attractive valuations.
- If balance sheet strength is your first filter, start with a list of solid balance sheet and fundamentals (25 results) that can handle shocks better than highly leveraged peers.
- When you prefer steady compounding over drama, consider a lineup of 32 resilient stocks with low risk scores that screen well on a range of risk factors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com